How to Apply for a Student Loan to Get a Higher Education & Make Career

Student Loan

How to apply for a Student Loan doesn’t come randomly in anyone’s mind. Getting into a good college is only half the battle. The other half starts the moment you realize a B.Tech at a decent private university now costs ₹8–15 lakh, an MBA at a tier-2 B-school can run past ₹12 lakh, and a master’s abroad easily crosses ₹40 lakh once you add living costs. 

If you don’t have that sort of money lying around, a Student Loan is the only realistic option — and how to get one usually determines how much of that money actually gets deposited into your account, and how much you end up overpaying in interest over the next 10 years. 

This guide walks through the process as it actually works in India in 2026, not the version that shows up in a bank’s marketing brochure.

How to Apply for a Student Loan Through the Vidya Lakshmi Portal

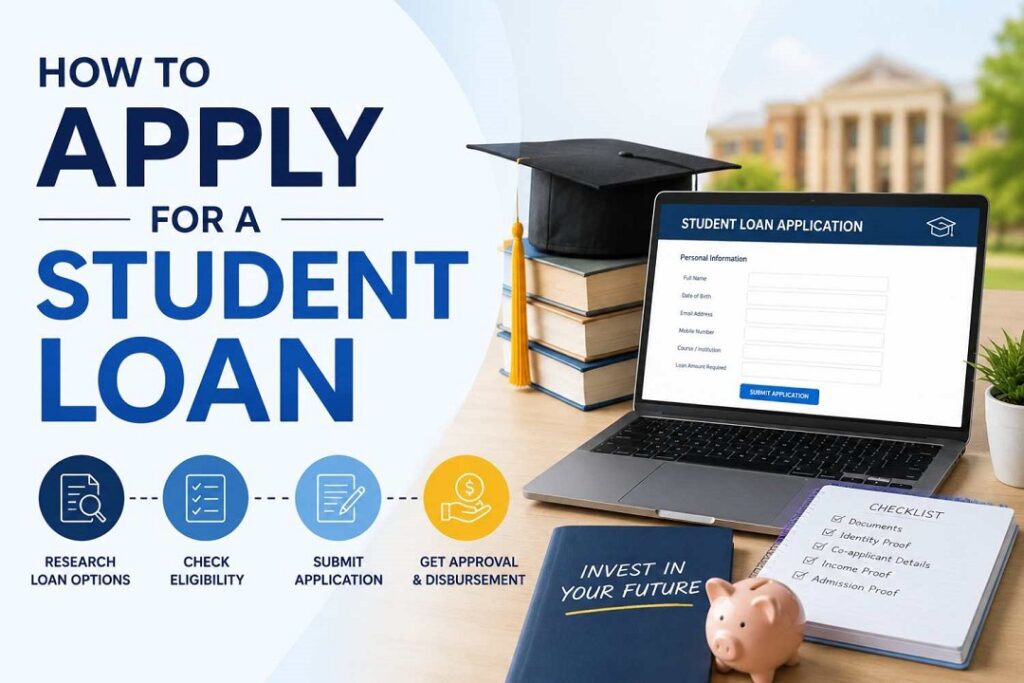
Almost every organized education loan in India now runs through the Vidya Lakshmi portal, a government-backed single window that connects more than three dozen banks and well over 100 loan schemes to one common form. Instead of visiting five bank branches and filling five different applications, you fill one — the Common Education Loan Application Form (CELAF), prescribed by the Indian Banks’ Association and accepted by every participating lender.

The process, in order:

  • Register on the portal with your email ID and a mobile number, ideally the one linked to your Aadhaar, since OTP verification runs through it.
  • Fill the CELAF in sections — personal details, course and institution details, cost breakdown, and your co-applicant’s financial information.
  • Upload KYC documents, academic transcripts, and your admission letter in the required digital format.
  • Use the “Search and Apply” tab to filter loan schemes by amount, interest rate, and whether you’re studying in India or abroad.
  • Shortlist and apply to a maximum of three banks in one go — a sensible mix is usually one public-sector bank (lower rate, slower processing) and one private bank or NBFC (faster, more flexible).
  • Track status from your dashboard. If a bank marks your application “on hold,” it means they want more documents — check the remarks column rather than waiting for an email.

The portal is also linked to the National Scholarship Portal, so if you qualify for a central or state scholarship, you can apply for it in the same sitting.

Where the PM Vidyalaxmi Scheme Fits In

Layered on top of Vidya Lakshmi since 2024–25 is the PM Vidyalaxmi Scheme, a Central Sector Scheme aimed specifically at students who’ve secured admission — through merit-based or open competitive selection — into a Quality Higher Education Institution (QHEI). The official list currently runs past 800 institutions and keeps expanding as new NIRF-ranked colleges get added, so don’t assume your college qualifies; check the current QHEI list on the portal before you plan around this scheme.

What it actually gets you:

  • No collateral, no guarantor for eligible loans. Some official sources describe this as applying to the entire loan regardless of amount; others cap the collateral-free portion at ₹7.5 lakh, after which the bank may ask for security on the balance. This detail genuinely varies by bank in practice — confirm it directly with your chosen lender before you apply, don’t assume either version.
  • A 75% government credit guarantee on loans up to ₹7.5 lakh, which is what makes banks comfortable lending without collateral in the first place.
  • Interest subvention during the moratorium period (course duration plus one year) — full interest subsidy if annual family income is up to ₹4.5 lakh, and a 3% subsidy if family income falls between ₹4.5 lakh and ₹8 lakh, both capped at loans up to ₹10 lakh.
  • Above ₹8 lakh family income, you still get the collateral-free structure and credit guarantee — you just pay the bank’s normal interest rate with no subsidy.

To claim the subvention, you submit an “intent” declaration on the portal along with income proof from an authorized state government authority — it isn’t automatic just because you’re eligible.

Eligibility Criteria You Need to Meet For Student Loan Across Indian Banks

Setting PM Vidyalaxmi aside, general education loan eligibility across Indian banks looks fairly consistent:

  • You need to be an Indian national with confirmed admission to a recognized, full-time regular course — part-time and distance programs are excluded by most lenders, though a few NBFCs make exceptions.
  • A co-applicant, almost always a parent or guardian, is required by nearly every bank once the loan crosses a modest threshold (often ₹4 lakh), and their income and credit history factor directly into how much you’re sanctioned.
  • For merit-based schemes like SBI’s Scholar Loan or PM Vidyalaxmi’s QHEI route, your entrance exam rank or admission channel matters as much as your family’s finances — these schemes exist precisely to reward the admission, not the collateral.
  • There’s no universal age cap, but banks do informally weigh whether you’re likely to complete the course and start repaying within a reasonable working-age window.

Documents to Keep Ready Before You Apply

Missing paperwork is the single most common reason applications sit in limbo for weeks. Have these ready before you start the CELAF, not after:

  • Admission letter and the institution’s official fee/cost structure
  • Mark sheets for 10th, 12th, and any prior degree
  • Identity proof — Aadhaar and PAN at minimum
  • Co-applicant’s income proof: recent salary slips or ITR, and the last six months of bank statements
  • Collateral documents, if your loan amount or scheme requires security
  • Passport and visa copy, if you’re studying abroad

Keep names spelled identically across every document — a mismatch between your Aadhaar and your admission letter is a small thing that causes real delays.

How Much Will It Cost You Across Every Sector Banks

Interest rates on Indian education loans in 2026 span a wide range depending on lender type:

  • Public-sector banks (SBI, PNB, Bank of Baroda, Union Bank, Canara Bank) generally price standard education loans between roughly 8% and 10.75% p.a., floating, tied to each bank’s repo-linked or external benchmark rate. As of mid-2026, the RBI repo rate itself sits around 6.25% — the actual benchmark moves at each monetary policy review, so treat any quoted rate as a starting point to verify, not a fixed number.
  • SBI’s Scholar Loan, reserved for students admitted to premier institutes like IITs, IIMs, and NITs, runs noticeably lower — roughly 6.9% to 7.65% p.a. — compared to its regular Student Loan Scheme at around 9.4% to 9.9%.
  • Private banks and NBFCs (HDFC Credila, Avanse, and similar) typically charge 9.5% to 16% p.a. Rates are higher, but sanction and disbursal are usually faster, and many offer larger unsecured amounts.
  • Most public banks give a 0.5% interest concession to girl students — worth asking about explicitly, since it isn’t always advertised upfront.
  • Several lenders, including SBI and PNB, offer a 0.5–1% rate discount if you pay simple interest during the moratorium period instead of letting it accumulate. Skipping this is the single most expensive mistake students make: unpaid interest during your study years gets added to the principal, so your EMI ends up calculated on a bigger loan than you actually borrowed.

Claiming the Section 80E Tax Benefit Once You Start Repaying

Once repayment begins, Section 80E of the Income Tax Act lets you deduct the entire interest component of your EMI from taxable income — not the principal, just the interest, but with no upper cap, which is unusual among Indian tax deductions.

A few conditions determine whether you actually qualify:

  • The deduction is available for a maximum of eight consecutive years, starting from the year you begin paying interest, or until the interest is fully repaid, whichever comes first.
  • It only applies if you’ve opted for the old tax regime — under the new regime, this deduction isn’t available at all, so run the comparison before you file.
  • The loan must come from a recognized bank, financial institution, or an approved charitable institution. A loan from an employer, a relative, or an informal lender does not qualify, no matter how similar the repayment terms look.
  • You can claim it for a loan taken for yourself, your spouse, your children, or a legal ward — and it applies whether the course was pursued in India or abroad.
  • You’ll need an interest certificate from your lender each financial year, clearly splitting principal from interest, to actually file the claim.

How To Avoid Application Rejection

A few patterns show up again and again in rejected or delayed applications: 

  • Applying to just one bank instead of shortlisting two or three through Vidya Lakshmi and comparing offers side by side
  • Assuming your college is on the PM Vidyalaxmi QHEI list without checking the current portal listing
  • Letting moratorium interest pile up instead of paying it as simple interest each quarter
  • Submitting documents where your name, date of birth, or address doesn’t match exactly across your Aadhaar, admission letter, and bank KYC. 

Each of these is fixable in an afternoon but only if you catch it before submission, not after a bank has already put your file on hold.

Select the Reliable Option for Student Loan

If you’ve been admitted to a QHEI on the current PM Vidyalaxmi list and your family’s annual income is under ₹8 lakh, start there through the Vidya Lakshmi portal — the interest subvention alone can save you lakhs over the loan’s life, and it’s the closest thing to free money in this entire process. 

If your institution isn’t on that list, or your loan requirement crosses ₹10 lakh, shortlist two or three public-sector banks, compare their post-moratorium rates head-to-head, and ask each one directly what your EMI looks like once the subsidy or discount period ends. Not the headline interest rate but that one question is where most students get blindsided.

Conclusion 

The paperwork for Student Loan application is simpler once you have your documents in order, have compared lenders and know the government schemes that apply to you. Vidya Lakshmi portal provides students a one-stop shop to apply for education loans and also compare the loans, while PM Vidyalaxmi can help eligible students by lightening their financial load through interest support and collateral-free loans. 

Before you accept any offer, look beyond the stated interest rate. Check the terms of the moratorium (temporary period in which you don’t have to start paying the regular EMI), your eligibility for subsidy, the amount you need to repay, the amount of collateral required and the total interest you will pay. A bit of comparison before signing can make a big difference to your finances after you graduate.
Leave a Comment

Your email address will not be published. Required fields are marked *

NTA NEET UG Result 2025 Out – Click Here to Check Your Score Now!

NTA NEET UG Result 2025 Out

NEET UG Result 2025 is officially announced, you can check your scores from the link mentioned in the article. Candidates who were given an examination with the hope of admission to the medical university must be eager to see the result. Check the result by entering the registration number and password. The result is also available on the official NTA website. The candidates who succeed also check the official website consistently.

It is officially declared by the Indian system of medicine for admission in medical institutions for medical education, it is mandatory to take the entrance exam. Based on the score you can get admission to a medical university. The exam offers many undergraduate programs like BAMS, BUMS, MBBS, etc.

Exam NameNational Eligibility cum Entrance Test
Conducting bodyNational Testing Agency
NTA NEET UGIt is an entrance exam for students who want admission to a medical university for a medical degree.
Topper listClick Here
Result LinkClick Here
Official websiteClick Here

Read More 👉 NEET PG 2025 Admissions Exam Date Out – Check Eligibility, Syllabus & Apply Online Now!

Steps to download NTA NEET UG Result 2025

  • Open the official website or click on the Result Link in this article.
  • Enter the necessary details such as registration number, password, and DOB for accessing your result.
  • Your result will be displayed on the screen.
  • If it does not appear it may be because of a rush on the website.
  • Try to reload the page and enter your details again.
  • Check the details twice if there is no mistake, your result will be displayed.
  • Take a printout for an offline copy of the result.

Eligibility Criteria for the NEET UG Examination

Education12th completed with science stream
Minimum marks: 50%
Minimum age17 years
Maximum ageNo limit
NationalityNo restrictions for non-citizens of India

Conclusion

The wait is over for the students who appeared in the NEET UG exam because NTA has officially released the NEET UG Result 2025, you can check from the direct link. The candidates who succeed in achieving their goal with good scores are now eligible to hold a medical degree. If not, you can attempt next year for the NEET UG Examination with more preparation.

Best Government Jobs in Karnataka in 2025

If you are looking for a government job in Karnataka, then 2025 can be a very good year for you. There are many such options in Best Government Jobs in Karnataka in 2025 which not only give good salary but also give job security and respect. Whether you are 12th pass or graduate, Karnataka government releases jobs in different departments for candidates of every level.

Many big departments like KPSC (Karnataka Public Service Commission), Karnataka Police, PWD, Forest Department continue recruitment every year. Below we have made a list of top 15 government jobs in Karnataka, in which you have been given details of job title, department name, eligibility and official website. You can apply in these according to your qualification.

Best Government Jobs in Karnataka in 2025

S.No.Job TitleDepartment/OrganizationEligibilityOfficial Website
1Karnataka Administrative Service (KAS) OfficerKarnataka Public Service Commission (KPSC)Graduate degreehttps://kpsc.kar.nic.in
2Deputy Superintendent of Police (DSP)Karnataka Police DepartmentGraduate, Physical Standardshttps://ksp.gov.in
3Assistant EngineerKarnataka Public Works DepartmentEngineering Degree (Civil/Electrical)https://kppwd.karnataka.gov.in
4Junior EngineerKarnataka Urban DevelopmentDiploma/Engineering in relevant fieldhttps://urban.karnataka.gov.in
5Forest Range OfficerKarnataka Forest DepartmentGraduate in Forestry/Biologyhttps://aranya.gov.in
6Lecturer (Engineering/Science)Karnataka State Higher EducationPostgraduate Degree + NET/SEThttps://karnatakavidhana.gov.in
7Staff NurseKarnataka Health & Family WelfareDiploma/Degree in Nursinghttps://karunadu.karnataka.gov.in
8Revenue InspectorKarnataka Revenue DepartmentGraduatehttps://karnataka.gov.in
9Taluk AccountantKarnataka Revenue DepartmentGraduatehttps://karnataka.gov.in
10Assistant Section OfficerKarnataka SecretariatGraduatehttps://kpsc.kar.nic.in
11Village AccountantKarnataka Revenue Department12th Passhttps://karnataka.gov.in
12Police ConstableKarnataka Police Department12th Pass + Physical Standardshttps://ksp.gov.in
13Assistant Executive EngineerKarnataka Urban DevelopmentEngineering Degree (Civil/Mechanical)https://urban.karnataka.gov.in
14Food Safety OfficerKarnataka Food Safety DepartmentGraduate with Science backgroundhttps://fssai.gov.in
15Assistant Public ProsecutorKarnataka Law DepartmentLLB Degree + Registered Advocatehttps://karnataka.gov.in

Your Credit Score Ignores 90% of Your Financial Life — What Your First Credit Card Changes 

Credit Score

Once your first credit card is approved, you probably think that you are eligible for loan or finance. But you’re wrong because your credit score matters and it is built from repayment history not from your financial status or expenses. There are four active bureaus (CIBIL, Experian, Equifax, CRIF High Mark) in India and they all sit between 300 and 900 score. 

And it doesn’t know your salary, your savings account, your mutual fund SIPs, or the fact that you’ve never once missed a rent payment. It tracks exactly one thing closely: how you’ve handled borrowed money. 

That gap between what the score sees and what your financial life actually looks like is where most first-time cardholders get caught off guard.

What Your Credit Score Measures in Your Financials

A score is built almost entirely from repayment behavior. FICO, the US model most bureaus borrow their logic from, publishes its weighting: payment history (about 35%), credit utilization (about 30%), length of credit history (about 15%), credit mix (about 10%), and new credit inquiries (about 10%). 

It breaks it down, the ingredients look roughly like this:

  • Payment history — whether you’ve paid EMIs and card bills on time. This carries the heaviest weight, often estimated at around 30-35%.
  • Credit utilization — how much of your available credit limit you’re actually using. Maxing out a card, even if you pay it off in full, can quietly hurt you. 
  • Length of credit history — how long your oldest active account has been open. This is exactly why closing your first credit card years later can lower your score instead of helping it. 
  • Credit mix — a blend of secured loans (car, home) and unsecured ones (credit cards, personal loans) reads better than having only one type. 
  • New credit inquiries — every time you apply for a loan or card, a “hard inquiry” gets logged, and too many in a short window signals risk to lenders. 

CIBIL doesn’t publish its exact formula, but the underlying behavior it rewards and punishes is the same. None of this touches your bank balance. It only starts once you’ve borrowed something — a loan, an EMI, a credit card and shows how consistently you paid it back.

Read More 👉 Best App To Get Instant Loan Without Salary Slip

The 90% of Credit Score Never Sees Your Financial Life

Your salary doesn’t appear on your first credit card report. Neither does your savings balance, your fixed deposits, your stock or mutual fund portfolio, property you own, freelance or side income, or rent you’ve paid on time for years (unless you’ve specifically enrolled in one of the newer rent-reporting services, which are still rare in India). Utility bills and UPI spending don’t count either, since none of that is borrowed money. 

This cuts both ways. Someone with a strong income and zero loans can be “credit invisible” — no score at all, simply because they’ve never borrowed. Someone drowning in personal debt but paying the minimum on time every month can carry a technically decent score while their actual finances are falling apart. The number reflects repayment discipline, not net worth.

Why This Number Still Runs Your Financial Life

Even though it’s a narrow measurement, it’s the one lenders trust most. A home loan applicant with a score above 750 might get an interest rate a full percentage point lower than someone below 650 — on a 20-year loan, that gap alone can add up to lakhs of rupees in extra interest. 

Your score also decides which credit cards you qualify for and what limit you’re offered, and in some sectors — finance, banking, occasionally government roles — employers run a credit check as part of background verification. 

Landlords in a few metro markets have started asking for credit reports too. None of that is about how much you earn. It’s entirely about whether you’ve paid back what you owed, on time, before.

The Mistakes That Wreck a First-Time Cardholder’s Score

Paying Only the Minimum Due

The minimum due usually around 5% of the outstanding bill — keeps your account technically current, but the remaining balance starts accruing interest immediately, typically in the range of 3 – 3.5% a month, which works out to somewhere near 36–42% annualized. It’s one of the most expensive ways to borrow money that exists, and the balance compounds faster than most first-time users expect.

Maxing Out the Limit

Spending close to your full limit every month signals risk to lenders, even if you clear the bill in full. Keeping usage under roughly 30% of your available limit protects the score far more than people assume — this is often a bigger factor than the actual bill amount.

Applying for Multiple Cards in the First Year

Every new application triggers a hard inquiry, and each one dents the score slightly while sitting on your report for a couple of years. Several applications close together read to lenders as credit hunger, not creditworthiness.

Missing the Due Date, Even Once

A single day late usually just costs a late fee. But once a payment crosses roughly 30 days overdue, it typically gets reported to the bureau and that single entry can move the score sharply and stay visible for years.

Closing the Card Too Early

Shutting down  your first credit card within the first year shortens your average credit age, which is one of the more underrated factors in the score. A longer, active history — even on a card you barely use — tends to help more than starting fresh with a new one.

Read More 👉 How to Apply for an Education Loan Online

The Right Way to Spend From Your First Card

Treat it like a debit card with a receipt trail, not free money. Pick one or two recurring expenses — a mobile recharge, one subscription, fuel and route them through the card on autopay. This builds a steady, low-risk repayment pattern without tempting you into overspending. 

Pay the full statement balance every cycle, not the minimum. Check your statement monthly for errors or unfamiliar charges. Avoid withdrawing cash on the card entirely — interest usually starts from the day of withdrawal with no grace period, on top of a flat fee near 2.5–3%. 

And think twice before converting purchases to EMI, even “no-cost” ones; the discount you’d have gotten on the outright price is often quietly folded back into the total.

How Fast Can a Credit Score Really Move?

Scores don’t jump in percentages — there’s no such thing as a score rising “by 90%.” They move in points, and how fast depends on which factor you’re fixing. 

Utilization moves quickest: pay down a high balance before your statement date, and the next reporting cycle, usually 30 to 45 days later, can reflect a meaningful jump, sometimes 50 or more points on the 900-point scale, because utilization updates almost as fast as your balance does. 

Payment history moves slower and compounds instead: one on-time payment barely registers, but six to twelve months of consistent on-time payments builds a track record lenders actually trust. Bureau errors — a closed loan still showing as open, a paid card marked as defaulted, can also produce a fast correction once flagged, sometimes within a single reporting cycle. 

For someone starting with a thin or nonexistent credit file, a workable, lender-friendly score in six to twelve months of disciplined use is a realistic target. Overnight is not.

Before Cardholder Swipe That First Time

Pull your free annual report from the bureau and note your starting number before you spend a single rupee. Set autopay for the full statement amount, not the minimum, and add a separate calendar reminder a few days before the due date as backup. 

Pick one recurring bill to run through  your first credit card and leave the rest alone for now. Then check the number again in three months, not three weeks — that’s roughly how long it takes the system to actually reflect what you did.

Read More 👉 Business Ideas for Students With Zero Investment — Easy Startup Guide

Conclusion

Your financial health doesn’t increase your Credit Score and it is important to maintain that score. It’s a way for lenders to understand how responsibly you’ve handled borrowed money, not how much you earn, save, invest, or own. 

For a first-time cardholder, utilization should be lower, pay the statement balance on time, do not fill unnecessary applications, be patient and give time for your credit history to grow. Treat your first credit card as a tool for building trust with lenders, so when you actually need a bigger loan or good credit, you can get it easily. 

IDBI Bank Specialist Officer Recruitment 2026: Check Every Detail Before Apply

IDBI Bank Specialist Officer Recruitment 2026

IDBI Bank has officially announced the IDBI Bank Specialist Officer Recruitment 2026 in which Professionals who are looking for fresh opportunities in India’s leading private sector banks can apply. They are recruiting experienced candidates for multiple posts across multiple departments, including Information Technology, Audit, Legal, Risk Management, Infrastructure, and Security.

Candidates are shortlisted based on their qualifications, relevant work experience, and performance in the interview unlike the other banking recruitments where the selection process includes a written examination.

IDBI Bank released the notification on 10 July 2026 and the online application window opened on 14 July 2026 but only until 26 July 2026. That’s a short runway, so if this role fits your background, the smart move is to stop scrolling other job portals and get your documents in order today.

Event IDBI Bank Specialist Officer Recruitment Dates
Applications open14 July 2026
Last date to apply26 July 2026
Total vacancies31 Specialist Officer posts
Selection modeNo written exam — screening, GD/Interview, medical test

What This IDBI SO 2026 Recruitment Is Actually For

IDBI Bank is hiring 31 Specialist Officers across four functional areas: Audit (Information Systems), Infrastructure Management Department (Premises), Legal, and Security. The posts span three grades — Deputy General Manager (Grade D), Assistant General Manager (Grade C), and Manager (Grade B), which tells you this is a lateral entry drive built for people who already have domain experience, not fresh graduates hoping to break into banking.

That distinction matters more than most people realize. A lot of aspirants see “Bank Specialist Officer” and assume it works like the IBPS SO exam, complete with online tests and months of mock-paper practice. This one doesn’t. IDBI Bank is screening candidates directly on qualifications and verified work experience, then moving shortlisted applicants straight to Group Discussion and Personal Interview.

Post-Wise Vacancy Overview

Functional AreaGradeWho Should Apply
Audit – Information SystemsManager / AGM / DGMIT, Computer Science, or Cyber Security background with IS audit experience
Infrastructure Management (Premises)Manager / AGM / DGMCivil or Electrical Engineers with infrastructure or project management experience
LegalManager / AGM / DGMLaw graduates with relevant banking or corporate legal experience
Security OfficerManager (Grade B)Candidates with a background in security operations, often ex-defence or law enforcement

Eligibility Criteria: Age, Qualification & Experience

Age requirements vary by post and grade, generally falling between 25 and 45 years as on 1 July 2026, with the usual government-mandated relaxations for reserved categories. What’s worth flagging is that age relaxation applies only to the IS Audit, IT & MIS, and Risk Management posts — it doesn’t extend to the Security Officer (Grade O) category, so double-check your eligibility window against the specific post you’re targeting rather than assuming a blanket rule applies.

On the qualification side, IDBI Bank has kept things fairly specific to each domain. 

  • For Audit-IS roles, you’ll need a B.E./B.Tech in Information Technology, Computer Science, Electronics, or a closely related discipline, ideally paired with certifications and hands-on audit experience. 
  • For IMD-Premises, a Civil or Electrical Engineering degree with real infrastructure project exposure is the baseline. 
  • Legal posts expect a law degree along with courtroom or corporate legal experience relevant to banking. 

And here’s something candidates often overlook: experience gained purely through internships, training programs, apprenticeships, graduate trainee roles, or contractual and outsourced payroll arrangements will not be counted. IDBI Bank wants confirmed, full-time professional experience, not project stints.

Selection Process: No Written Exam, But No Shortcuts Either

The absence of a written test doesn’t mean the process is easier — it just shifts where the pressure sits. IDBI Bank’s Specialist Officer selection unfolds in four stages, and each one filters harder than the last.

Preliminary Screening comes first, where the bank shortlists applications based on declared age, educational qualifications, and work experience. This is where an incomplete or vaguely worded application gets quietly dropped, so precision in how you describe your experience actually matters here.

Document Verification follows, checking every declared detail against your original certificates. Anything that doesn’t match on paper becomes a problem at this stage, which is exactly why the bank has been explicit that training, internship, or contractual experience won’t be accepted as valid.

Candidates who clear both stages move to Group Discussion and/or Personal Interview, where only a limited number are called based on how strong their qualifications and experience look on paper. This is genuinely where the selection gets decided — panels are typically senior bank officials assessing domain depth, not general aptitude.

Finally, there’s the Pre-Recruitment Medical Test (PRMT). Clearing the interview isn’t the finish line; your final offer still depends on being certified medically fit under the bank’s standards.

Read More 👉 Banking Job vs SSC Job: Details On The Top Government Jobs 

How to Apply for IDBI Bank Specialist Officer SO Recruitment 2026

The entire process runs online, and IDBI Bank has been clear that no other mode of application will be entertained. 

Here’s how the steps break down in practice:

  1. Start by visiting the IDBI Bank careers page and navigating to Current Openings, where you’ll find the notification titled “Recruitment of Specialist Officer – 2026-27 (Advt. No. 03/2026-27).” 
  2. Register using a valid personal email ID and mobile number — the bank will use these for all future communication, so it needs to stay active through the entire process. 
  3. Fill in your personal, educational, and experience details carefully, since this is the same data that gets checked line by line during document verification later. 
  4. You’ll then need to upload a photograph, signature, thumb impression, a handwritten declaration, and a scribe declaration if applicable, all in the exact size and format specified in the notification.

Once your form is complete, review it thoroughly before hitting final submit — IDBI Bank does not allow edits after that point. Pay the application fee online which is around Rs. 1050 for general and Rs. 250 for reserved category, wait for server confirmation, and save your e-receipt along with the Provisional Registration Number and password sent to your email and phone. Print your final application and confirmation for future reference, because you’ll likely need it at the document verification stage.

Candidates must know that they are allowed to apply for only one post and if they try to apply for multiple posts then it leads to outright rejection. The fee won’t be refunded. So if you see yourself eligible for more than one position then take a break to think which one suits your strongest experience before you apply.

Salary, Perks & Career Prospects

Beyond the pay scale attached to each grade, selected candidates get access to allowances, perquisites, and Performance Linked Variable Pay under the bank’s policy, which is periodically revised. 

Every appointee joins on a one-year probation and gets covered under the IDBI Bank Ltd. New Pension Scheme (IBLNPS) Rules, 2011. It’s also worth knowing that IDBI Bank reserves the right to post you anywhere across its branches, offices, or associate institutions based on organizational need, and it can offer a grade one level lower than what you applied for depending on suitability and vacancy availability. Neither of these should be dealbreakers, but they’re worth factoring into your decision before you apply.

How to Actually Prepare for This Recruitment

Since there’s no written paper to study for, preparation here looks completely different from a typical bank exam. Your real work is making sure your professional story holds up under scrutiny because that’s exactly what the interview panel is going to test.

Go through your own experience letters and appointment records before you fill the form, and make sure the dates, designations, and responsibilities you’re about to declare match what’s on paper. Any mismatch surfaces during document verification, and there’s no recovering from it at that stage. 

If you’re applying for the Audit-IS post, be ready to speak in depth about specific systems you’ve audited, frameworks you’ve worked with, and findings you’ve closed — vague answers don’t hold up against a panel of senior audit professionals. The same logic applies across Legal, Infrastructure, and Security roles: panels in specialist recruitment drives ask pointed, experience-based questions, not textbook definitions.

It also helps to read up on IDBI Bank itself — its recent financials, its position as a LIC-backed private sector bank, and any developments in the department you’re applying to. Interviewers often gauge genuine interest by asking why a candidate specifically wants to join IDBI Bank over sticking with their current organization, and a generic answer here tends to stand out for the wrong reasons.

Read More 👉 Institute of Banking Personnel Selection (IBPS) 2026: Complete Exam & Recruitment Guide

Conclusion

The IDBI Bank Specialist Officer recruitment 2026 rewards people who’ve already put in the years, not people looking for an exam. If your background genuinely fits one of these four functional areas, then this opportunity is for you: a stable banking sector role, a defined pay scale, and a faster route than the traditional written-exam route most candidates are used to. The only real risk right now is running out of time before 26 July 2026, so if you’re eligible, get the application moving today rather than next week. 

How to Join Indian Army — Your Complete Guide to Serving the Nation

How to join Indian Army

How to join Indian Army: It’s not just a job, a profession or a service, it’s a way of life to be in the Indian Army and a lifetime commitment to the nation. For millions of young Indians, the olive-green uniform stands for honor, meaning and pride that far surpasses any regular jobs. But the path to joining the Indian Army isn’t a smooth one it requires vision, preparation, stamina and the knowledge of different entry points available. 

Whether you are a 10 or 12 student, a graduate or one aspiring to get commissioned, the Indian Army has multiple avenues to make that dream a reality. Unique in this sense, this guide shows you everything from entry schemes, through selection stages, fitness, documents, medical standards, ensuring that you can prepare as best you can to help you realise your own dream to serve the nation with pride.  

Understanding Your Entry Options

There are hardly any rigid models for recruitment of the Indian Army. The company understands that people with potential can come from anywhere educationally and that is why it has different entry schemes. If you are a class 12 passer, the Agniveer scheme is for you. If you’re a graduate or an engineer, you can apply for the Short Service Commission (SSC) or the Technical Graduate Course (TGC). For people still in class 12 with strong academics, the NDA is a well-known route that leads to officer-level commissions.

What I like about Indian Army recruitment is its open door policy. For soldiers and officers, technical and manpower roles for that matter, there is something for everyone. Your starting point might be different from your colleague’s, but the destination – serving the nation – is the same. 

The Most Popular Route: Agniveer Scheme

For most hopefuls it has become like the Agniveer scheme and this is the only option going forward. Introduced to recruit a younger, more dynamic force into the Armed Forces, the scheme is available for men and women aged 17.5 to 21 years. You must have passed class 10th/12th from a recognized board with minimum 50% marks in aggregate.

The submission of the application is easy. Go to the official site joinindianarmy.nic.in and register providing your basic details, e-mail and mobile number. You will fill up application details with your 10th certificate with as per rules. After you have submitted, you will be given a registration number—hold on to this, it is the key to the next step. 

Read More 👉 UPSSSC Lekhpal Online Form 2025: Apply Online for 7,994 Revenue Posts

The Three-Phase Selection Gauntlet

After the registration you must prepare yourself for three intense stages. The first state is the Common Entrance Exam (CEE), a written test conducted offline. This test examines your understanding of General Knowledge, Mathematics, Science and Reasoning. It’s not like you need to memorize stuff, the exam is on your logical thinking and problem solving skill.

If you clear the CEE, then you will be invited for the second stage: the Recruitment Rally. This is your physical fitness moment! The rally comprises a Physical Fitness Test (PFT) which is truly exhausting. You must run 1.6 km in 5 minutes and 45 seconds, do at least 6 pull-ups, jump a 9-foot ditch, and complete a zig-zag balance test. They’re not just random drills, they’re meant to test whether or not your body can keep up with the rigors of military life.

The third stage is the medical test and document confirmation. Medical examinations are extensive – they examine your vision, hearing, bone density, heart health, and your general well-being. The Army needs soldiers who aren’t just strong but also medically able to go where it’s hard to go. 

Physical Fitness

Being physically fit matters, and you really can’t ignore your way through it. If you really want to join, start your fitness regimen now. Running is your foundation—start with distances you can handle and slowly increase your speed and distance. Do interval training by alternating between high-intensity bursts and recovery intervals.

For pull-ups, who you are is more important than how many you can do right now. If you have no pull-ups yet, use resistance bands/assisted pull-ups or work on negatives to start building strength. Add push-ups, sit-ups and squats for full body strength. Flexibility and balance are also important for many candidates don’t realise, but it is this which is tested in the zig-zag test. Add yoga and agility drills to your training.

Nutrition-related matters are just as vital/nutrition matters are just as vital/nutrition is just as vital Nutrition & hydration are equally important Nutrition Jones in Sydney opined: “it is not only the training [that is important], nutrition is [also]. Fuel your body with protein, complex carbohydrates, fruits and vegetables. Keep hydrated as you train, and stay away from junk food that zaps your energy. 

The Officer Route: A Different Path

If you are a class 12 student with good academic record and want to join Indian Army, consider the Technical Entry Scheme (TES for NDA) or the National Defence Academy (NDA). The NDA is conducted by the Union Public Service Commission (UPSC) and the applicants must be aged between 16.5 and 19.5 years have qualified 10+2 to be eligible. The competition is stiff with only 5 to 10 percent getting selected but the reward is a three year training at the National Defence Academy and then a permanent commission in the Indian Army.

​For graduates, the Combined Defence Services (CDS) exam, which leads to Indian Military Academy (IMA). Male and female candidates who are graduates are also eligible and the selection procedure consists of a written exam and then the infamous Services Selection Board (SSB) interview.

The SSB Interview: The Ultimate Test

If there is a stage that divides the dreamers and the doers it is the SSB interview. This isn’t your run-of-the-mill job interview; you’ll be subjected to a five-day psychological and personality test to determine how officer-like you are. You will be having the Officer Intelligence Rating (OIR) test, Picture perception and discussion (PPDT), psychological tests, group discussions, outdoor tasks and a personal interview.

Leadership, teamwork, bravery, and the capacity to think on your feet are the qualities that the SSB wants. It evaluates the consistency between what you think, what you say and what you do — an idea based on the ancient “Manasa, Vacha Karmana” principle. The interviewing officer will question your background, your motivation for enlisting, your knowledge of current events, and your capacity to stress. 

Documents Required For This Position

  • 10th and 12th mark sheets and certificates
  • Domicile certificate with photograph
  • Caste certificate
  • Religion certificate
  • School character certificate
  • Unmarried certificate (if below 21 years)
  • Aadhar card or ID proof
  • 20 passport-size color photographs
  • Any NCC certificates or sports achievements

The Medical Examination

After passing the physical and mental evaluations, you will have a full medical check-up. The Army requires its soldiers to withstand harsh environments, so the standards are tough. After you cross this last barrier, you will get your joining letter and will be sent to the respective training academy. 

Conclusion

Enrolling in the Indian Army is not just about getting a job and a stable source of income. You’d be serving your country, joining a brotherhood that has stayed vigilant over the nation for generations, and doing something that’s bigger than you are. The path is tough, the competition is fierce and the training will test you to your limits.

But here is what makes it so worthwhile: the privilege of wearing the uniform, the gratification of serving one’s country, and the realization that you are a member of an organization that has influenced the future of the nation. If you have the passion, if you have the resolve, and if you can run – the Indian Army awaits you. Start today, hold fast, and who knows maybe, just maybe, a year from now you’ll be standing tall in that uniform, serving the nation with pride. 

Scroll to Top