Your Credit Score Ignores 90% of Your Financial Life — What Your First Credit Card Changes 

Credit Score

Once your first credit card is approved, you probably think that you are eligible for loan or finance. But you’re wrong because your credit score matters and it is built from repayment history not from your financial status or expenses. There are four active bureaus (CIBIL, Experian, Equifax, CRIF High Mark) in India and they all sit between 300 and 900 score. 

And it doesn’t know your salary, your savings account, your mutual fund SIPs, or the fact that you’ve never once missed a rent payment. It tracks exactly one thing closely: how you’ve handled borrowed money. 

That gap between what the score sees and what your financial life actually looks like is where most first-time cardholders get caught off guard.

What Your Credit Score Measures in Your Financials

A score is built almost entirely from repayment behavior. FICO, the US model most bureaus borrow their logic from, publishes its weighting: payment history (about 35%), credit utilization (about 30%), length of credit history (about 15%), credit mix (about 10%), and new credit inquiries (about 10%). 

It breaks it down, the ingredients look roughly like this:

  • Payment history — whether you’ve paid EMIs and card bills on time. This carries the heaviest weight, often estimated at around 30-35%.
  • Credit utilization — how much of your available credit limit you’re actually using. Maxing out a card, even if you pay it off in full, can quietly hurt you. 
  • Length of credit history — how long your oldest active account has been open. This is exactly why closing your first credit card years later can lower your score instead of helping it. 
  • Credit mix — a blend of secured loans (car, home) and unsecured ones (credit cards, personal loans) reads better than having only one type. 
  • New credit inquiries — every time you apply for a loan or card, a “hard inquiry” gets logged, and too many in a short window signals risk to lenders. 

CIBIL doesn’t publish its exact formula, but the underlying behavior it rewards and punishes is the same. None of this touches your bank balance. It only starts once you’ve borrowed something — a loan, an EMI, a credit card and shows how consistently you paid it back.

Read More 👉 Best App To Get Instant Loan Without Salary Slip

The 90% of Credit Score Never Sees Your Financial Life

Your salary doesn’t appear on your first credit card report. Neither does your savings balance, your fixed deposits, your stock or mutual fund portfolio, property you own, freelance or side income, or rent you’ve paid on time for years (unless you’ve specifically enrolled in one of the newer rent-reporting services, which are still rare in India). Utility bills and UPI spending don’t count either, since none of that is borrowed money. 

This cuts both ways. Someone with a strong income and zero loans can be “credit invisible” — no score at all, simply because they’ve never borrowed. Someone drowning in personal debt but paying the minimum on time every month can carry a technically decent score while their actual finances are falling apart. The number reflects repayment discipline, not net worth.

Why This Number Still Runs Your Financial Life

Even though it’s a narrow measurement, it’s the one lenders trust most. A home loan applicant with a score above 750 might get an interest rate a full percentage point lower than someone below 650 — on a 20-year loan, that gap alone can add up to lakhs of rupees in extra interest. 

Your score also decides which credit cards you qualify for and what limit you’re offered, and in some sectors — finance, banking, occasionally government roles — employers run a credit check as part of background verification. 

Landlords in a few metro markets have started asking for credit reports too. None of that is about how much you earn. It’s entirely about whether you’ve paid back what you owed, on time, before.

The Mistakes That Wreck a First-Time Cardholder’s Score

Paying Only the Minimum Due

The minimum due usually around 5% of the outstanding bill — keeps your account technically current, but the remaining balance starts accruing interest immediately, typically in the range of 3 – 3.5% a month, which works out to somewhere near 36–42% annualized. It’s one of the most expensive ways to borrow money that exists, and the balance compounds faster than most first-time users expect.

Maxing Out the Limit

Spending close to your full limit every month signals risk to lenders, even if you clear the bill in full. Keeping usage under roughly 30% of your available limit protects the score far more than people assume — this is often a bigger factor than the actual bill amount.

Applying for Multiple Cards in the First Year

Every new application triggers a hard inquiry, and each one dents the score slightly while sitting on your report for a couple of years. Several applications close together read to lenders as credit hunger, not creditworthiness.

Missing the Due Date, Even Once

A single day late usually just costs a late fee. But once a payment crosses roughly 30 days overdue, it typically gets reported to the bureau and that single entry can move the score sharply and stay visible for years.

Closing the Card Too Early

Shutting down  your first credit card within the first year shortens your average credit age, which is one of the more underrated factors in the score. A longer, active history — even on a card you barely use — tends to help more than starting fresh with a new one.

Read More 👉 How to Apply for an Education Loan Online

The Right Way to Spend From Your First Card

Treat it like a debit card with a receipt trail, not free money. Pick one or two recurring expenses — a mobile recharge, one subscription, fuel and route them through the card on autopay. This builds a steady, low-risk repayment pattern without tempting you into overspending. 

Pay the full statement balance every cycle, not the minimum. Check your statement monthly for errors or unfamiliar charges. Avoid withdrawing cash on the card entirely — interest usually starts from the day of withdrawal with no grace period, on top of a flat fee near 2.5–3%. 

And think twice before converting purchases to EMI, even “no-cost” ones; the discount you’d have gotten on the outright price is often quietly folded back into the total.

How Fast Can a Credit Score Really Move?

Scores don’t jump in percentages — there’s no such thing as a score rising “by 90%.” They move in points, and how fast depends on which factor you’re fixing. 

Utilization moves quickest: pay down a high balance before your statement date, and the next reporting cycle, usually 30 to 45 days later, can reflect a meaningful jump, sometimes 50 or more points on the 900-point scale, because utilization updates almost as fast as your balance does. 

Payment history moves slower and compounds instead: one on-time payment barely registers, but six to twelve months of consistent on-time payments builds a track record lenders actually trust. Bureau errors — a closed loan still showing as open, a paid card marked as defaulted, can also produce a fast correction once flagged, sometimes within a single reporting cycle. 

For someone starting with a thin or nonexistent credit file, a workable, lender-friendly score in six to twelve months of disciplined use is a realistic target. Overnight is not.

Before Cardholder Swipe That First Time

Pull your free annual report from the bureau and note your starting number before you spend a single rupee. Set autopay for the full statement amount, not the minimum, and add a separate calendar reminder a few days before the due date as backup. 

Pick one recurring bill to run through  your first credit card and leave the rest alone for now. Then check the number again in three months, not three weeks — that’s roughly how long it takes the system to actually reflect what you did.

Read More 👉 Business Ideas for Students With Zero Investment — Easy Startup Guide

Conclusion

Your financial health doesn’t increase your Credit Score and it is important to maintain that score. It’s a way for lenders to understand how responsibly you’ve handled borrowed money, not how much you earn, save, invest, or own. 

For a first-time cardholder, utilization should be lower, pay the statement balance on time, do not fill unnecessary applications, be patient and give time for your credit history to grow. Treat your first credit card as a tool for building trust with lenders, so when you actually need a bigger loan or good credit, you can get it easily. 
Leave a Comment

Your email address will not be published. Required fields are marked *

Google Launches Fitbit Air in India: Features, Price and Availability

Fitbit Air

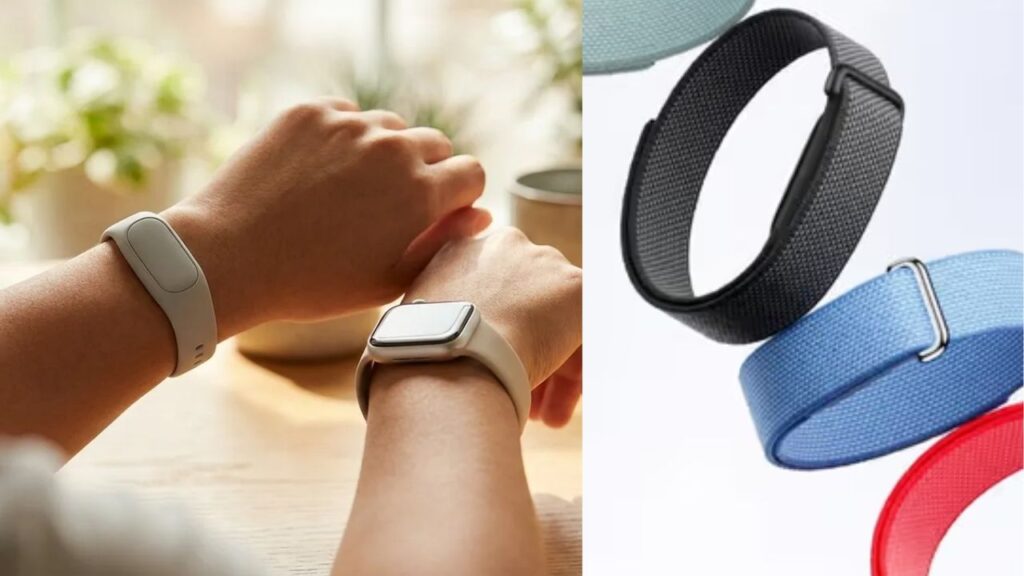
Picture a fitness tracker you forget you’re wearing. It has no screen to check mid-meeting and no buzz on your wrist at 2 a.m. That’s the idea behind the Fitbit Air. Google has now launched it in India at ₹13,999, with sales starting October 2. It’s the company’s smallest and lightest FitBit yet, and it arrives in a market where most people expect a wearable to have a display. 

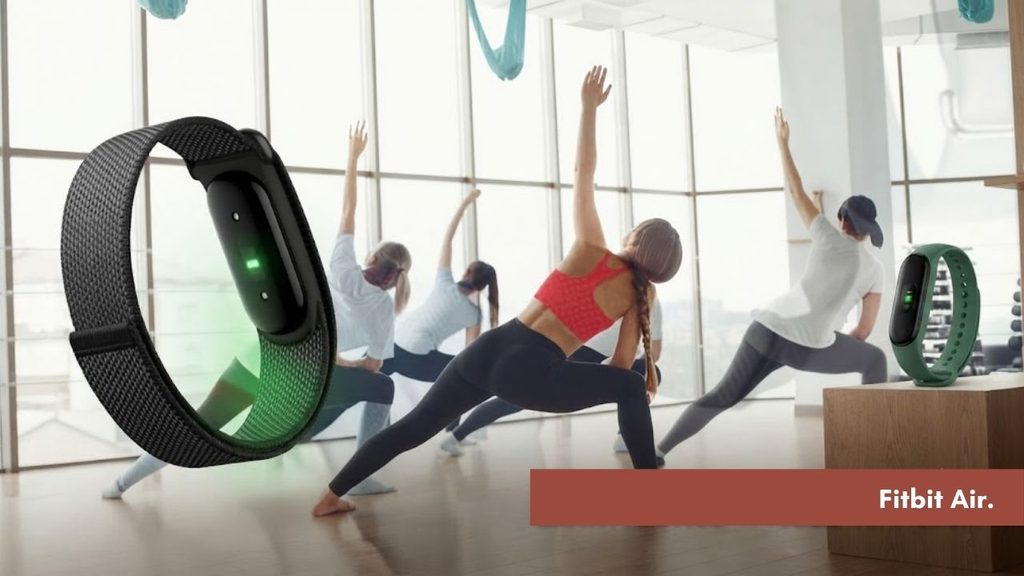
The Fitbit Air isn’t a smartwatch. It’s a small sensor “pebble” that sits in a band and tracks your body in the background. Everything you want to read, like sleep scores, workout recaps and heart trends, lives in the Google Health app on your phone.

This isn’t a brand-new product. Google announced the Fitbit Air globally on May 7, 2026, with US shipping from May 26. India is getting it about four months later.

Fitbit Air Price in India And Launch Offers

The India price is ₹13,999 for all four colours. The box includes a three-month trial of Google Health Premium. That trial matters because it unlocks the Google Health Coach, the AI assistant Google built this tracker around.

For comparison, the US price is $99.99. Indian buyers will pay noticeably more than the US sticker price. On bank offers, buyers using eligible HDFC Bank and ICICI Bank cards get ₹1,000 cashback at launch, and it can be combined with six-month no-cost EMI. The exact terms may vary depending on the bank’s conditions.

Google Health Premium will cost is different in India after the trial ends. In the US, it runs $9.99 a month. Google hasn’t shared an Indian figure in the launch details, so check the Google Store listing before you buy.

More Helpful : Voice-to-Notes Tools for Students

What Fitbit Air Features Tracks And How Long It Lasts

Sensors

Google says the sensors cover 24/7 heart rate, heart rhythm monitoring with Afib alerts, SpO2, resting heart rate, heart rate variability, and sleep stages and duration. However, Google’s own footnote says the Afib feature is not available in all countries. So it is still unconfirmed whether it will be switched on in India at launch. If irregular-rhythm alerts are a deciding factor for you, verify this first.

Battery life is the other reliable feature 

Google claims up to a week per charge, and five minutes of fast charging gives you roughly a full day. Those numbers come from Google’s own pre-production testing, so real-world results may be lower.

Workout tracking is where the Google Health Coach comes in 

The Air detects common activities automatically, and you can also start a session from the app. With Premium, you can snap a photo of a cardio machine or a gym whiteboard routine and have it logged.

Hardware details from the global launch:

SpecFitbit Air
DisplayNone
WeightAbout 5 g for the pod alone, 12 g with a band
Water resistance50 metres 
BatteryUp to 7 days (Google’s claim)
Phone supportAndroid 11 or higher, iOS 16.4 or higher
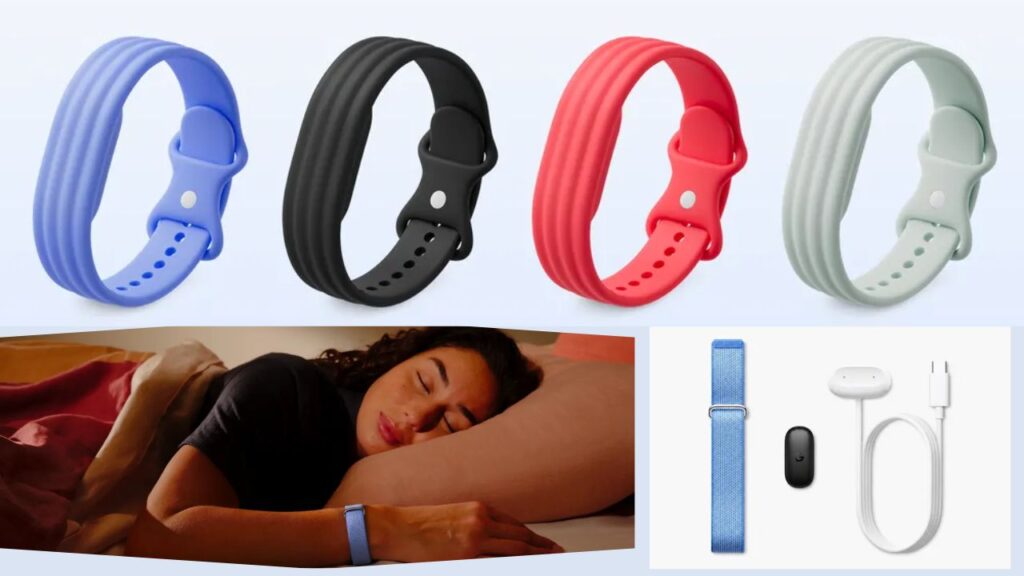
Colours (India)Obsidian, Berry, Lavender, Fog

A reviewer at The5KRunner reported that the Air has no built-in GPS, so run distances will depend on your phone. 

Bands

The pebble pops out, so you can swap bands. The Performance Loop, made from recycled materials, comes in the box. The sweatproof Active Band and the dressier Elevated Modern Band are sold separately. India pricing for those extra bands wasn’t available at the current time.

Fitbit Air Availability In India

The Fitbit Air goes on sale October 2 through the Google Store, Flipkart, Croma, Reliance Digital and Vijay Sales. That offline spread is a smart move for a product people may want to try on first. A screenless tracker is odd enough that holding one makes it easier to understand.

👉 Explore More: Apple iPhone Duo Cost-Effective Methods

Fitbit Air vs Whoop: How Does it Compare?

The obvious rival is Whoop, which pioneered the screenless band. The 5.0 is bulkier, at about 27 g with its band, and rated for 10 metres of water resistance. The bigger difference is the business model. 

Whoop requires a membership starting at $199 a year, while the Fitbit Air’s core tracking works without a required subscription. WHOOP’s current India pricing and availability weren’t clear, so the comparison below uses US pricing only. 

Beyond that, the Fitbit Air competes with cheaper straps like the Amazfit Helio Strap and with Fitbit’s own older display trackers. Those give you a screen for similar money. If you want to glance at the time or your heart rate mid-run, a screenless band is a step backward.

Conclusion

You can buy a Fitbit Air if sleep and recovery data matter more to you than notifications, you already like the Google ecosystem. If you’ve been curious about Whoop but dislike paying a yearly fee. Then it makes you confused, what you need matters most. The Fitbit Air is more comfortable to use around 24/7. A 12 g band is easier to wear to bed than a smartwatch.

Skip it if you want on-wrist GPS, quick glances at stats, or music and payments. Also hold off if the Premium price after the three-month trial is unclear to you, since the Coach is the main reason to choose this over cheaper trackers.

Wait for the October 2 listings, check the final Premium pricing and bank-offer terms, and compare against any display tracker you’re considering at ₹13,999. Then decide which one you can need.

Leave a Comment

Your email address will not be published. Required fields are marked *

IIT BHU Non-Teaching Recruitment 2026 — Vacancy and How to Apply

IIT BHU Non-Teaching Recruitment

IIT BHU Non-Teaching Recruitment 2026 is currently live, visit official website to fill the form. The online application time will end on 01/October/2026. It is conducted by the Indian Institute of Technology (Banaras Hindu University), Varanasi to fill 55 regular vacancies across various administrative, technical, engineering, library, and Rajbhasha cadres.

Candidates who are eligible for this recruitment can apply but make sure that you must have official educational documents in hand before applying. Other necessary documents are also required during filling the application.

ItemDetail
OrganizationIndian Institute of Technology (Banaras Hindu University), Varanasi
Total vacancies55 posts (Group B & C)
Application modeOnline via SAMARTH portal only
Online application window25 Aug 2026 – 01 Oct 2026, 5:00 PM (last date extended)
Physical copyMandatory: printout + documents by Speed Post within 7 days of last date
SelectionShortlisting + possible Screening/Written Test, GD, Presentation, Interview (as per post)
Nature of appointmentRegular with probation; institute may offer on contract basis in some cases

Application Fee

Post GroupGeneral / EWS / OBC (Male)SC / ST / PwBD / All Female
Group B (e.g., Junior Superintendent, Assistant/Junior Engineer, JTO)₹500Nil
Group C (e.g., Junior Technician, Junior Library Assistant)₹250Nil

Essential Qualifications Required For IIT BHU Non-Teaching Recruitment 

The eligibility criteria depends on the posts you are applying for because it requires knowledge in that particular area. 

  • Bachelor’s degree in any discipline with at least 55% marks for a Junior Superintendent and supervisory experience also required (3 years at Level 5 or equivalent). 
  • Bachelor’s degree in B.Sc. or B.E./B.Tech or a Diploma in engineering with at least 55% marks for Junior Technician is required. But Diploma holders must also have 1 year of experience in the same field. 
  • Civil Engineering post sets a rule that candidate must qualify B.E./B.Tech or 3-year Diploma in engineering and an experience certificate.
  • To apply for Assistant Engineer, you must have a B.E./B.Tech or Diploma in Civil/Electrical Engineering with extensive experience (5–8 years). 
  • You are required for Bachelor’s/Diploma in Library & Information Science with 55% marks to Junior Library Assistant post. 

Read Also 👉 RRB NTPC 2026 Online Form: Graduate and UG Level Dates, Vacancies, and How to Apply

IIT BHU Non-Teaching Recruitment 2026 Vacancy Breakdown (post-wise)

Post NameCadreGroupPay Level (7th CPC)VacanciesUpper Age Limit
Junior SuperintendentAdministrativeBLevel 621 35 yrs
Junior Technician (Group-I: Chemistry/Physics)TechnicalCLevel-34 27 yrs
Junior Technician (Group-II: Mech/Met/Ceramic/Mat Sci)TechnicalCLevel-311 27 yrs
Junior Technician (Group-III: Electrical/Electronics)TechnicalCLevel-33 27 yrs
Junior Technician (Group-IV: Civil/Arch/Mining)TechnicalCLevel-34 27 yrs
Junior Technician (Group-V: CSE/IT/CCIS)TechnicalCLevel-34 27 yrs
Junior Library AssistantLibraryCLevel-3230 yrs
Assistant EngineerEngineeringBLevel 82 40 yrs
Junior EngineerEngineeringBLevel 63 35 yrs
Junior Translation OfficerRajbhashaBLevel 61 35 yrs

Selection Process IIT BHU Non-Teaching Recruitment

The selection process typically includes an initial screening of applications, based on online data. Shortlisted candidates may be called for Written Test / Skill Test / Presentation or Interview (depending on the post requirements) and document verification. 

Schedules will be sent only by email to registered IDs; no hard copies. Visit the official website of the IIT BHU to check the lists of shortlisted/non-shortlisted candidates. The reason is also mentioned there for your status. 

How to Apply (step-by-step)

  1. Go to SAMARTH portal: https://iitbhunt.samarth.edu.in if you wanna apply for IIT BHU Non-Teaching Recruitment 2026.
  2. Register → fill personal, educational, and experience details carefully (no edits after submission).
  3. Upload photo/signature and required documents.
  4. Pay application fee (if applicable).
  5. Submit online by 01 Oct 2026, 5:00 PM.
  6. Take a printout of the submitted form.
  7. Now you have to send that printout along with copies of your required qualification documents and experience certificate by courier to the Registrar, IIT (BHU), Varanasi – 221005. Application No., Advertisement No., and Post Name & Code must be written on the envelope.
  8. If you’re a serving Govt/Autonomous/Educational employee, ensure your application is forwarded through Proper Channel within 7 days of the last date; upload NOC & Vigilance Clearance (or produce at interview).

Read Also 👉 Festive Season Sale In October Is About to Reshape Smartphone Prices in India 

Conclusion 

IIT BHU Non-Teaching Recruitment 2026 drive is on-going on an official portal. Apply now or you’ll miss the deadline, but check your eligibility before applying and download the official notification for more deeper details. The vacancy breakdown is given so you can guess the competition level for your exam.

Leave a Comment

Your email address will not be published. Required fields are marked *

Apple iPhone Duo Changes the Cost Effectively With These Methods

Apple iPhone

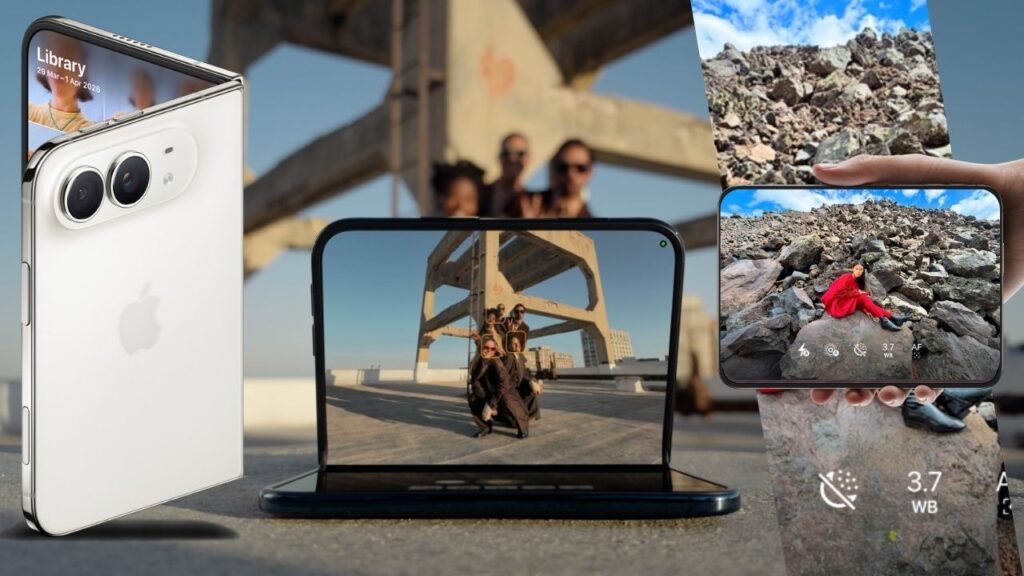
The Apple’s iPhone Duo is unlike any iPhone before with foldable versatility and 50% larger screen than iPhone 18 Pro Max. Apple iPhone Duo price started at ₹2,99,900 for a base 256GB model. The EMI run down to ₹48,817 a month sounds almost manageable until you realise that’s just for the base model if you want more space, the cost is going higher.

The top 2TB configuration crosses ₹4,49,900, either way, Apple’s first foldable is the most expensive iPhone the company has ever sold in India, and pre-orders open at 5:30 PM IST on October 16, with units shipping from October 23. 

Between No Cost EMI, card cashback, and trade-in credit, there are real ways to bring the effective cost down, and just as many ways to misread the fine print and end up paying more than you expected. 

What the Apple iPhone Duo Costs in India

Apple has published pricing for all four storage tiers of the Duo:

  • 256GB — ₹2,99,900
  • 512GB — ₹3,24,900
  • 1TB — ₹3,74,900
  • 2TB — ₹4,49,900 

The iPhone 18 Pro starts at ₹1,64,900 and the iPhone 18 Pro Max at ₹1,79,900. The Duo’s entry price is roughly ₹1,35,000 above the Pro — not a small step up, and one reason Apple’s foldable debut in India has drawn as much attention for its billing as for its 7.6-inch inner display and A20 Pro chip. 


Unlike the standard iPhone 18 line, the iPhone Duo isn’t manufactured locally, so import duty and GST land on top of a device that already costs more to make. In the US, the same phone starts at $1,999 (roughly ₹1.7 lakh at the going exchange rate) — a reminder that Indian pricing on the Duo carries a heavier markup than usual, even by iPhone standards.

Apple iPhone Duo EMI: What Costs You Per Month

Apple’s No Cost EMI on the Duo runs over 3 or 6 months through most major card issuers — noticeably shorter than what Apple offers elsewhere. The US gets 24-month Apple Card Monthly Installments at roughly $83/month; the UK gets 30 months at 0% APR, working out to about £67/month. India’s 6-month cap is the shortest interest-free tenure Apple offers on the Duo anywhere, which is exactly why the monthly number here looks so heavy.

Published monthly EMI figure against each storage tier, and what six payments actually add up to versus the list price:

StorageMonthly EMI6-Month TotalSavings vs List Price
256GB₹48,817₹2,92,902₹6,998 under
512GB₹52,983₹3,17,898₹7,002 under
1TB₹61,317₹3,67,902₹6,998 under
2TB₹73,817₹4,42,902₹6,998 under

The Cashback Catch: ₹15,000 Sounds Bigger Than It Is

Apple India advertises “up to ₹15,000 instant cashback” across its entire store for customers using eligible American Express, Axis Bank, or ICICI Bank cards. That ₹15,000 is a store-wide ceiling — it’s not a number attached to the Duo, or to any single product. 

Run the EMI math above and the actual deduction baked into Apple’s Duo pricing lines up with ₹7,000, the same figure that’s been reported for the iPhone 18 Pro launch offer. Budget for that, not for ₹15,000.


A few conditions apply regardless of which figure you’re chasing:

  • Minimum transaction value of ₹10,001
  • Maximum two qualifying orders per rolling 90-day period
  • Not available to Business Store customers, and can’t be stacked with Education or Corporate Employee Purchase Plan pricing
  • Apple India explicitly reserves the right to revise or withdraw these terms without notice 

Apple hasn’t published a cashback figure specific to the Duo, a list of exactly which card variants qualify, an AppleCare+ price for the folding display, or what a screen repair would cost outside warranty. If any of those numbers matter to your decision, wait for the October pre-order.

Read More 👉 Your Dollar Income Isn’t Fixed: How INR Volatility Changes Freelancers Earning 

Turning Your Old iPhone Into a Down Payment

Apple’s exchange program advertises “save up to ₹62,000” when you trade in an eligible smartphone — available both online and in-store. Treat that ₹62,000 as a ceiling for a high-end device in excellent condition, not a number your specific phone will hit. 

A three-year-old iPhone with a cracked back glass is not pulling anywhere near that figure. If trade-in is central to your plan, get an online valuation for your exact device and condition before pre-order day, so you’re not recalculating your budget at checkout.


Third-party platforms like Cashify have historically run parallel exchange bonuses on top of card-linked EMI offers — ICICI’s Instant EMI programme has combined a 24-month deferred payment structure with additional exchange bonuses up to ₹6,000 on older iPhone models. 

The ICICI offer terms currently list iPhone 16 and 17-series devices, not the Duo. It’s reasonably expected that Duo-specific versions of these programmes will show up once pre-orders open.

Where You Can Buy Apple iPhone Duo

Apple India’s own store — with UPI, net banking, and EMI on eligible cards — is the confirmed channel from October 23. Authorized Apple resellers and large retail chains are expected to carry it too, based on how Apple has rolled out every recent flagship. 

Amazon and Flipkart listings are widely expected to go live around the launch window, though neither platform has published Duo-specific financing or exchange terms as of now. 

If a Bajaj Finserv No Cost EMI card or a Flipkart-specific bank offer matters to your plan, that’s one more thing to check on launch day rather than assume.

Apple iPhone Duo vs iPhone 18 Pro Max: Is the Jump Worth Financing?

The comparison that actually matters for your wallet isn’t Duo-to-Duo storage tiers — it’s Duo versus the iPhone 18 Pro Max, since that’s the next phone up in Apple’s current India lineup.

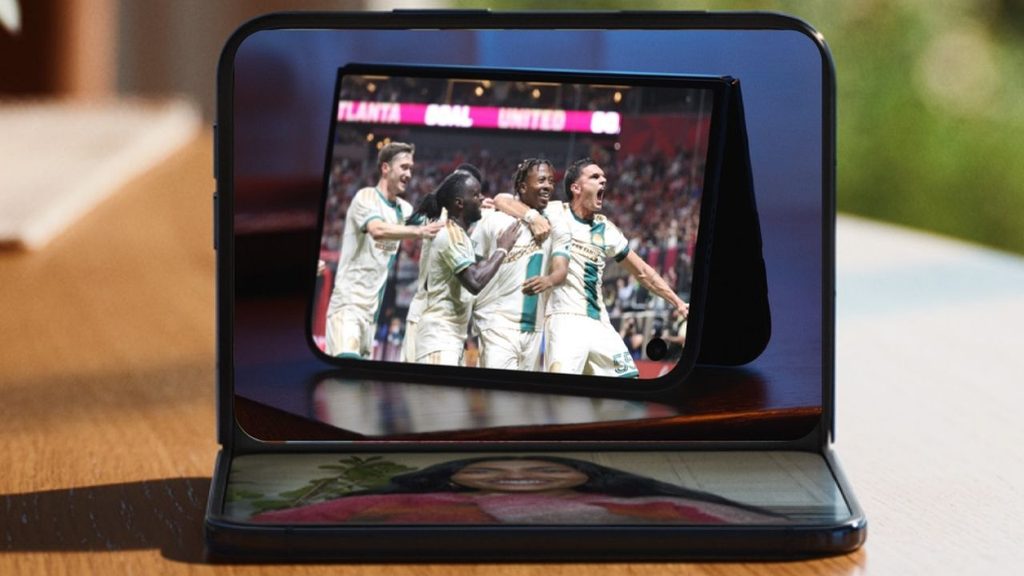
The iPhone 18 Pro Max starts at ₹1,79,900, less than two-thirds of the Duo’s ₹2,99,900 entry price, and runs on the same A20 Pro silicon. What you’re paying the extra ₹1,20,000 for is the fold itself: a 7.6-inch inner display Apple says is 50% larger than the Pro Max screen, a 5.4-inch cover display carrying over 90% of the Pro Max’s screen area when closed, and software in iOS 27 built specifically to adapt across open, half-folded, and closed states — split-screen Safari and Siri-driven multitasking that the Pro Max’s single flat screen can’t replicate.


That’s the real difference between these two smartphones. It’s a much harder case to make if your actual use is calls, camera, and social media, where the Pro Max’s flat 6.9-inch OLED does the job for a lot less money and without a hinge to eventually worry about. If the fold itself isn’t pulling you toward the Duo, the EMI math above becomes a much easier decision: skip it.

There’s also a first-generation-hardware question worth asking before you commit six months of EMI to it. The Duo’s hinge uses more than 100 parts and a magnet array to snap shut, sits under a titanium frame, and pairs Ceramic Shield 2 on the outer front with regular Ceramic Shield on the back — Apple’s most reinforced build on any iPhone. That’s a serious engineering effort, but it’s also Apple’s first attempt at a folding mechanism, with no multi-year track record the way the flat-screen Pro Max has. 

If you’ve never owned a folding phone and are financing this on EMI you can’t easily walk away from, it’s worth being honest about whether you’re the kind of owner who’ll baby a hinge for two years, or the kind who’ll drop it once every four months.

Read More 👉 Foreign Education Loan Currency Explained: How INR Depreciation Can Increase Your Loan Cost 

Apple’s eSIM-Only & 31 Hours Battery Power Doesn’t Affect On Duo Costs

The Apple iPhone Duo has no physical SIM tray, anywhere in the world. Every line runs on eSIM, with two eSIMs active at once and room to store eight or more profiles. Apple says this is part of why the phone manages up to 31 hours of video playback on the inner display and up to 44 hours on the outer one — the tray took up space that now goes to the dual-battery system instead.

That’s not a deal-breaker in India, where Jio, Airtel, and Vi have supported eSIM on postpaid and select prepaid plans for years. But it does mean two things worth planning around before you finance a ₹3-lakh phone. 


First, if you’re switching from an Android phone with a physical SIM, you can’t just pop the card across — you’ll need to get an eSIM profile issued by your carrier, which usually means a store visit or an app-based request, not an instant swap. 

Second, if your trade-in plan involves handing over your current iPhone the same day you activate the Duo, do the eSIM transfer before you box up the old phone, not after — Apple’s eSIM Quick Transfer works phone-to-phone, but only while both devices are in hand. Neither issue affects what the Duo costs, but both affect how smoothly your launch-day purchase goes, and a botched activation is a bad way to start a 6-month EMI commitment.

Read More 👉 SSC CPO SI CAPF Online Form 2026

Conclusion — Which Financing Route Fits You?

If you’ve got a recent flagship iPhone to trade in for Apple iPhone Duo, exchange + EMI is your cheapest real path — get the online trade-in estimate first, then layer 6-month No Cost EMI with an eligible Axis, ICICI, or Amex card on whatever balance is left.

If you don’t have a trade-in and want the lowest monthly hit, 6-month EMI beats 3-month by roughly half the monthly outflow for the same total cost — there’s no financial reason to choose the shorter tenure unless your card’s credit limit forces it.

If you’re on the fence about needing the fold at all, the iPhone 18 Pro Max buys you the same chip and most of the camera capability for ₹1,20,000 less, with a financing plan that’s easier on the wallet either way.

And if none of the current numbers work for your budget, waiting past October 16 costs you nothing — Apple, Amazon, and Flipkart have all historically added deeper festive-season offers on new iPhone within weeks of launch, and the Duo’s card-specific cashback terms are explicitly subject to change before then.

Leave a Comment

Your email address will not be published. Required fields are marked *

Festive Season Sale In October Is About to Reshape Smartphone Prices in India 

Festive Season Sale

This year’s Festive Season Sale In October will bring many new offers and discounts on electronic products — massive offers hit on smartphones. If you’ve been sitting on an upgrade — whether that’s finally moving off a three-year-old Galaxy or jumping into the iPhone ecosystem for the first time — this is the window the entire Indian smartphone retail calendar builds toward. 

When the sale is live, which smartphone will actually get a discount and what’s coming to this season, know everything before planning around.

When Does the Festive Season Sale Start?

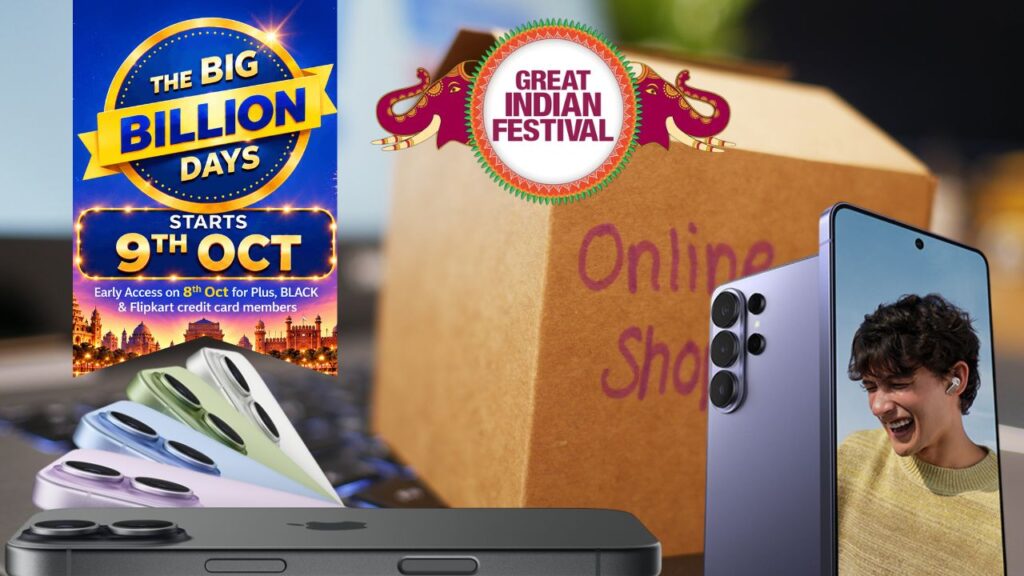
The Amazon Great Indian Festival 2026 is going live on October 8 with no closing date, so treat this as a multi-week sale. Prime members get early access from October 7. This Festive Season Sale has flagged on many categories, including mobile phones, electronics, home appliances, and fashion. With 160,000 seasonal jobs secured by Amazon to handle the load, this shows how big this year’s event is expected to be.

Flipkart’s Big Billion Days 2026 goes live for everyone on October 9, a day after Amazon, with early access on October 8 for Flipkart Plus, Flipkart Black and select co-branded credit card holders. Flipkart has also been running a slower build-up than usual: Early Bird Deals started September 24, and official price reveals on flagship phones have been trickling out since September 26.

October 7–9 for early access across both platforms, then the main event running through most of October. If you’re the type who wants to plan a purchase around the calendar rather than react to a flash notification, mark October 7 as your first checkpoint.

What Discounts and Bank Offers to Expect

Neither platform has published final smartphone pricing yet — genuinely, this is one area where numbers are still moving daily, and anyone claiming exact final prices two weeks out is guessing. What’s confirmed on the banking side is more solid:

On Amazon, SBI credit and debit card users get a flat 10% instant discount on eligible transactions, including EMI purchases, and Amazon has said overall discounts across electronics could run up to 80%, with an additional 10% on top for SBI cardholders. There’s already a Prime Coupon Bonanza running ahead of the main event, offering up to ₹6,000 off select Samsung and Sony televisions — a hint at how aggressive the electronics category is shaping up to be.

On Flipkart, Axis Bank and ICICI Bank cardholders get a 10% instant discount on eligible debit and credit card transactions, Flipkart Plus and Black members get up to 12% additional card discount, and Bajaj Finance EMI options are being pushed hard for higher-ticket purchases like flagship phones. Flipkart is projecting discounts climbing as high as 90% across electronics, appliances, fashion and home decor — though that ceiling figure almost always applies to accessories and older inventory rather than current-generation flagships.

Best Smartphone Deals Expected This Festive Season

1. iPhone 17 (256GB) — Best for iOS Upgraders on a Budget

The launch price of iPhone 17 is ₹82,900 for 256GB storage but if you purchase 512GB, the price rises up to ₹1,02,900. Flipkart’s dropping iPhone 17 price under ₹80,000 during Big Billion Days. From above Rs 1 lakh to Rs 80 thousand, the difference is quite big.


At a sub-₹80,000 price point, this is the cheapest true current-generation iPhone has ever launched into a festive sale with outstanding features including 6.3-inch Super Retina XDR display, A19 chip, dual rear camera system. It is available in 5 colours — Black, White, Mist Blue, Sage and Lavender.

Limitation: You still don’t get the telephoto lens or ProMotion display that the Pro models carry, so heavy zoom-shooters and gamers chasing 120Hz will feel the gap. But a perfect model for anyone upgrading from an older iPhone who needs a clear camera and high-end features.

👉 Why ChatGPT Ads Deserve a Place In Your 2027 Media Plan 

2. Samsung Galaxy S25 Ultra — Best Flagship Value Pick

Samsung put the launching price ₹1,29,999 on Galaxy S25 Ultra which was around ₹84,999 after a discount during Amazon’s July Prime Day and as low as ₹94,999 during the May Great Summer Sale and both offers flagged by the same retailer. Now it’s preparing for the festive push. Expect festive pricing to land in a similar ₹85,000–₹95,000 band.


You’re getting a phone that was a ₹1.3 lakh flagship a year ago for roughly two-thirds the
price. Buyers who are searching for best cameras and display smartphones can afford the Snapdragon 8 Elite for Galaxy chipset, which still holds up against 2026 competition. The flagship specifications 6.9-inch Dynamic AMOLED 2X display at up to 2,600 nits brightness, 12GB RAM, titanium frame with Corning Gorilla Armor 2 glass. 

Limitation: It’s now the previous generation — no Galaxy S26’s Snapdragon 8 Elite Gen 5 or the newer Privacy Display feature, and Samsung’s software support clock started a year earlier than on the S26.

3. Samsung Galaxy S26 Ultra — Best for the Latest Hardware

Another Samsung’s flagship model launched in 2026 at ₹1,39,999 for 12GB+256GB and for higher storage, price rises up to ₹1,59,999 for 512GB and ₹1,89,999 for 16GB+1TB. This smartphone is delivering a high-end technology — Snapdragon 8 Elite Gen 5 for Galaxy, 6.9-inch display and first built-in Privacy Display for limiting side-angle screen visibility. The festive offer lands near ₹1,24,999 because July sale cuts to the same.


A 200MP main camera with an absolute hardware system which can’t be broken easily. Buyers who are looking for 2026 latest smartphones at a range over 1 lakh, this is the best time to think about it.

Limitation: Because it’s this fresh, don’t expect S25 Ultra–style 35% festive cuts. If your budget caps around ₹1 lakh, the S25 Ultra is the more realistic festive buy.

4. Samsung Galaxy S25 FE — Best Mid-Flagship Pick

Flipkart teased S25 FE deals alongside the S25/S25 Ultra as part of its Big Billion Days smartphone lineup, Galaxy S25 FE discounted prices will land near ₹60,000. Buyers who can’t afford S26 Ultra for the series design language and camera hardware, this one provides them the same two features at an affordable range in this festive season.

Limitation: Detailed specs and confirmed pricing are still pending official reveal — if you need certainty before buying, wait for Flipkart’s price-reveal window closer to the sale date rather than an early-bird listing.

👉 Apple iPhone Duo Changes the Cost Effectively With These Methods

Compare iPhone 17 vs. Galaxy S25 Ultra On an Overview

iPhone 17 (256GB)Galaxy S25 Ultra (256GB)
Expected festive priceUnder ₹80,000₹85,000–95,000 (based on recent 2026 sale pricing)
Display6.3″, Super Retina XDR6.9″, Dynamic AMOLED 2X, 2,600 nits
Standout strengthCleaner ecosystem, resale valueBigger screen, S Pen support, titanium build

If display size and a stylus matter more to you than the Apple ecosystem, the S25 Ultra is the better festive buy at a comparable post-discount price. If you want the newest chip generation with the smallest footprint, the iPhone 17 wins.

Don’t Lock Into One Platform Too Early

Amazon and Flipkart are running near-identical bank-offer structures this year, but the specific phone deals won’t be identical — Samsung’s S25 Ultra pricing has historically differed by a few thousand rupees between the two platforms in past sales, and the same is likely this October. 

Check both listings once early access opens on October 7–8 before finalising a purchase; a single-retailer comparison isn’t a real comparison.

👉 Upgrade Laptop Like New Model In Low Budget

Conclusion

If your budget is under ₹80,000 and you want the newest possible chip, wait for the iPhone 17’s Festive Season Sale price to drop and buy it in the first 48 hours of early access — historically, the steepest festive cuts on genuinely new-generation phones show up early, before stock tightens.

If you’re chasing flagship specs on a ₹85,000–95,000 budget, the Galaxy S25 Ultra is the stronger buy this cycle, since last year’s flagship pricing has already proven it can fall that far. And if you specifically want Samsung’s newest chip and can stretch past ₹1.2 lakh, hold out for the S26 Ultra rather than compromising — buying older hardware you’ll regret in a year isn’t really a discount.

One practical step regardless of which phone you pick: add it to your Amazon or Flipkart wishlist now, and note the current listed price before October 7. That’s the only way to verify a “festive discount” is real rather than a price that was quietly bumped up the week before the sale.

Leave a Comment

Your email address will not be published. Required fields are marked *

SIP For Beginners: Best Time To Start is Your First Salary  

SIP

If you are a fresher then you should understand the value investment to secure your future. SIP for beginners is a basic core to let you know how truly you can enjoy your first paycheck. There’s this urge to celebrate — a new phone, a trip, dinner out every other night. Nothing wrong with any of that. But somewhere between the celebration and the next paycheck, most of us miss a quiet window that never really opens this wide again.

That window is the gap between “I have no financial responsibilities yet” and “I have financial responsibilities I can’t avoid.” And the best tool for that window is SIP which most people postpone for years.

They are 100% safe but not guaranteed. The risks involve which kind of mutual fund investors seek to invest in (equity, debt, or hybrid) not the process itself. 

What Is a SIP?

SIP stands for Systematic Investment Plan. Strip away the jargon and it’s simple — you invest a fixed amount, usually into a mutual fund, at regular intervals (usually monthly), instead of putting in one large sum at once.

Think of it like a gym membership for your money. You don’t need a big lump sum to start. You just need to show up consistently, month after month, and let the process do its work.

Why Your First Salary Is the Ideal Starting Point

There’s a reason financial advisors keep repeating this, even though it sounds like a cliché: time is the one resource that actually multiplies your money for you.

When you invest early, you’re not just investing your money — you’re investing years. And years, thanks to compounding, behave less like addition and more like multiplication.

Say you invest ₹5,000 a month starting at age 23, versus someone who starts the same amount at age 33. Assuming a similar average return over time, the person who started ten years earlier could end up with a corpus that’s not just proportionally bigger — it could be several times larger by retirement. The extra decade at the start does more work than an extra decade added at the end.

This isn’t about being lucky or picking the “right” fund. It’s about giving your money the maximum amount of time to grow.

Read More 👉 Your Credit Score Ignores 90% of Your Financial Life — What Your First Credit Card Changes 

How To Manage SIP Along With Your Daily Expenses

This is a fair point. Rent, EMIs, family contributions, that gym membership you forgot to cancel — early salary life is expensive. But this is exactly why starting small matters more than starting big.

A SIP doesn’t demand a large amount. Many funds let you start with as little as ₹500 a month. The goal in your first year isn’t to build wealth overnight — it’s to build the habit of paying your future self before you pay for anything else.

Pay yourself first, Instead of saving whatever’s left after spending, you flip the order — invest first, spend what remains.

Maintain Your Psychology To Empower Yourself Financially

Your spending habits calcify fast. The lifestyle you build in your first two years of earning tends to become your baseline. Once you get used to spending your entire salary, increasing that SIP amount later feels like a sacrifice, even if you’re earning more.

Starting a SIP with your first paycheck means your lifestyle grows around a slightly smaller number from day one. You never miss what you never got used to spending.

Read More 👉 Collateral vs No Collateral Loan Amount Where Collateral Starts Making Financial Sense

How To Avoid Common Mistakes — SIP For Beginners

Waiting for the “right” market conditions. SIPs are designed to work through ups and downs — that’s the entire point of investing at regular intervals instead of timing the market.

Choosing funds based on friends’ recommendations. What worked for your colleague may not match your goals or risk appetite.

Stopping the SIP the moment markets dip. Volatility is normal, not a signal to panic. Long-term SIPs are built to absorb short-term noise.

Not linking the SIP to an actual goal. A vague “let me just invest” often loses motivation. Tying it to something — a house down payment, early retirement, a five-year trip fund — makes it easier to stay consistent.

A Simple SIP For Beginners Way to Start

You don’t need a finance degree or a stockbroker uncle to get going. Most banking apps and investment platforms let you set up a SIP in under ten minutes:

1. Pick a fund category based on your goal and time horizon (equity for long-term growth, debt for shorter, safer goals).

2. Decide an amount you can commit to without stress — even a small one.

3. Automate it. Set the SIP date right after your salary credit date so it happens before you have a chance to spend it.

4. Increase it gradually as your income grows — many platforms let you “step up” your SIP automatically each year.

Read More 👉 Switching Jobs? Don’t Ignore Your EPF, NPS, and Mutual Fund Investments 

Conclusion

Nobody regrets starting a SIP early. Plenty of people regret waiting for the “perfect moment” that never quite arrives. Your first salary isn’t just your first taste of financial independence — it’s the cheapest, most flexible starting line you’ll ever get for long-term wealth building.

Start small. Start messy if you have to. Just start with the first one. A SIP for beginners guide will help you understand everything from why it is important to how to start, you just have to decide how much you can give for your future.

This post is for general awareness and educational purposes only. Mutual fund and SIP returns are subject to market risk. Please evaluate your own financial goals, risk appetite, and consult a financial advisor before making investment decisions.

Leave a Comment

Your email address will not be published. Required fields are marked *

Scroll to Top