Best Student Loans for College Students

Student Loans

Your admission letter came through and you are stressed about its fees? That’s the moment you’ll start looking for the best student loans for college students. Between tuition, hostel, a laptop, and living costs, a B.Tech at a decent private college or a master’s abroad can run anywhere from ₹8 lakh to over ₹1 crore, and very few Indian families are sitting on that kind of cash without dipping into a fixed deposit meant for something else. 

This is exactly where the best Student Loans in the market — from SBI’s Scholar Loan to NBFCs like HDFC Credila and Avanse, start doing real work, provided it actually fits your situation instead of just going with whichever bank branch is nearest to your house.

This blog walks through the loan for education options Indian students actually use in 2026 — public banks, private banks, NBFCs, and the government’s PM Vidyalaxmi scheme with real numbers, what each one is genuinely good at, and where it falls short.

Who Can Get These Loans for Education

If you’re an Indian student (or a parent reading this on their behalf) heading into an undergraduate program, a postgraduate course, or a study-abroad admission, and you need a study loan rather than paying out of pocket, this comparison is built for you. It splits lenders into three buckets — public sector banks, private banks, and specialised NBFCs because each serves a different kind of borrower, and picking the wrong bucket is the single most common reason students overpay by lakhs over a 15-year tenure.

Interest rates on education loans are floating and revised frequently by each lender’s internal benchmark. The figures below reflect indicative ranges reported by lenders and comparison platforms as of mid-2026. Treat every rate here as a starting reference, not a quote so confirm the live number on the lender’s own site before you apply.

Best Student Loans For College Students in India

1. SBI Scholar Loan / Global Ed-Vantage — Best for Domestic Students and Government-Bank Trust

  • Rate: roughly 8.15%–10.75%, MCLR-linked (floating)
  • Loan amount: up to ₹7.5 lakh without collateral for listed premier institutes; higher amounts with collateral, up to ₹1.5 crore under Global Ed-Vantage for study abroad
  • Processing fee: flat ₹10,000 — no percentage-based fee
  • Tenure: up to 15 years

SBI remains the default first stop for most Indian students, and there’s a simple reason: as the largest public bank, it consistently prices education loans lower than private banks and NBFCs, and its flat processing fee actually saves real money on larger loans compared to a percentage-based charge. 
The trade-off is speed — SBI’s sanction process for study-abroad loans can take four to eight weeks, and IBA guidelines require 15% margin money on foreign education loans above ₹4 lakh, meaning you’ll need to arrange that slice yourself. 

Best for: students with time before their visa deadline who want the lowest lifetime interest cost.

2. HDFC Credila — Best for Speed and High-Value Unsecured Loans

  • Rate: roughly 9.5%–13%, secured loans starting near 9.95%, unsecured (no collateral) starting near 11.25%
  • Loan amount: up to ₹50–60 lakh for premier institutes, sometimes higher
  • Processing fee: 1%–1.5% plus GST
  • Tenure: up to 15 years

Credila built its business on what it calls a “future employability” assessment rather than collateral value, which is why students without property to pledge still get approved here. Sanctions typically land in 7–14 days, which matters enormously when a visa interview is on the calendar and SBI’s timeline doesn’t fit. 

The catch is that unsecured Credila loans run meaningfully higher than SBI’s rate, and the processing fee, a percentage plus GST are added up fast on a ₹50 lakh loan. 

Best for: students on a tight admission or visa timeline who need fast, collateral-free approval and can absorb a higher rate.

3. Bank of Baroda — Best for Large Loans to Global Universities

  • Rate: competitive with SBI, generally in the 8.5%–11% band depending on the institute tier
  • Loan amount: up to ₹1.5 crore for premium global universities
  • Processing fee: typically lower than private banks; concessions available for girl students
  • Tenure: up to 15 years

BoB doesn’t get the same attention as SBI or the big NBFCs, but for students heading to genuinely expensive programs like top-50 global MBAs or engineering master’s — its higher loan ceiling and public-bank pricing make it worth a direct comparison. 

Best for: high-ticket study-abroad admissions where you need both a large sanction and a public-bank rate.

4. Avanse Financial Services — Best for Broad Course Coverage

  • Rate: roughly 11%–14.5%
  • Loan amount: up to ₹50–75 lakh
  • Processing fee: 1.25%–1.75% plus GST
  • Tenure: up to 15 years

Avanse is one of the few lenders that regularly finances courses public banks are cautious about — niche postgraduate programs, some online degrees, and vocational tracks. It’s genuinely useful when your course doesn’t fit a PSU bank’s approved list. The limitation is its rates sit at the higher end of the NBFC range, so it’s rarely the cheapest option on the table. 

Best for Student Loans for college students whose course or university isn’t covered by public-bank lending lists.

Read More👉 RRB JE Notification OUT With RRB JE Vacancy Of 3,993 Posts 

5. Axis Bank / ICICI Bank Education Loan — Best for Existing Bank Customers Wanting Fast Digital Processing

  • Rate: roughly 9.5%–13.5%
  • Loan amount: up to ₹40 lakh
  • Processing fee: moderate, varies by profile
  • Tenure: typically 10–15 years

If you or your parents already bank with Axis or ICICI, pre-approved education loans can be sanctioned in as little as 72 hours for existing customers, bundled with a forex card and a student account for study abroad. The point here is convenience, not price — you’re paying slightly more for an integrated, faster experience with a bank you already have a relationship with. 

Best for: existing customers who value speed and a bundled international banking package over shaving off the last percentage point of interest.

SBI vs HDFC Credila: The Two-Lender Face-Off

These two get compared constantly because they represent opposite philosophies — lowest cost versus fastest approval.

SBI Global Ed-VantageHDFC Credila
Starting rate~8.15%–9.65%~9.5%–11.25% (unsecured)
Processing feeFlat ₹10,0001%–1.5% + GST
Sanction time4–8 weeks7–14 days
CollateralRequired above ₹7.5 lakhOptional, employability-based
Best forLowest total interest costTight visa or admission deadlines

On a ₹50 lakh, 15-year loan, roughly every 100 basis points of extra interest costs about ₹7.5 lakh over the loan’s life, so the gap between these two isn’t cosmetic. Take Credila or Avanse first to secure fast disbursal for the visa file, then refinance into SBI once the loan is live and the pressure is off.
 

This works better than it used to, because the RBI’s Prepayment Charges Directions, effective January 1, 2026, banned foreclosure and prepayment charges on floating-rate loans to individual borrowers — a rule that covers nearly every education loan in this list. Before this, NBFCs could charge 2%–5% of the outstanding principal to close a loan early; that lock-in is now gone.

Don’t Skip the Government Route: PM Vidyalaxmi Scheme

Before comparing private lenders at all, check whether you qualify for PM Vidyalaxmi, the Centre’s collateral-free education loan scheme launched in November 2024. It isn’t a separate lender — it works through participating banks but it changes the math significantly for eligible students:

  • Collateral-free, guarantor-free loans up to ₹7.5 lakh, backed by a 75% government credit guarantee
  • Covers students admitted purely on merit (not management or NRI quota) to around 1,425 listed Quality Higher Education Institutions
  • A 3% interest subvention during the moratorium period for families with annual income up to ₹8 lakh, on loans up to ₹10 lakh
  • Rates capped at the bank’s benchmark lending rate plus 0.5%, with banks free to offer an extra 1% concession if you service interest during your study period
  • Subsidy is disbursed directly through the PM Vidyalaxmi Digital Rupee (CBDC) app

More than 1.12 lakh loans had been sanctioned under the scheme as of July 2026, so it’s no longer a pilot — it’s a live, functioning route worth checking on the PM Vidyalaxmi portal before you approach a bank directly.

Read More 👉 Best Student Laptops for School and University in 2026 

Two Rules That Apply Regardless of Which Lender You Choose

Section 80E tax benefit: the entire interest you pay on student loans for college students — not principal, and with no upper cap is deductible from your taxable income for up to 8 years from the year you start repaying. This applies to loans from any bank or approved NBFC and is one of the few genuinely uncapped deductions left in Indian tax law.
The girl-student concession: most public banks, including SBI and PNB, shave 0.5% off the standard rate for female applicants. It’s easy to miss because it’s rarely advertised loudly — ask for it explicitly when you apply for any of these student loans for college students.

Conclusion

If your priority is the lowest total interest over 15 years and you have a few weeks before your deadline, start with SBI — check PM Vidyalaxmi eligibility first if your loan need is under ₹7.5 lakh. 

If your visa interview or admission deposit deadline is within two weeks and you need money to move fast, HDFC Credila or Avanse will get you there, with the option to refinance into a cheaper public-bank loan later at no penalty under the new RBI rule. And if your course or university sits outside what PSU banks typically approve, Avanse’s broader course coverage is worth a direct call before you assume you’re out of options. 

Whichever lender you pick, don’t sign with the first offer you get on Student Loans for college students — pull two or three live quotes through the Vidya Lakshmi portal, apply the 80E deduction into your repayment planning from day one, and claim every concession you’re eligible for.

Note: Interest rates, fees, and scheme terms mentioned above are indicative and change frequently. Verify current figures directly with the lender or on official government portals before applying. 
Leave a Comment

Your email address will not be published. Required fields are marked *

SIP For Beginners: Best Time To Start is Your First Salary  

SIP

If you are a fresher then you should understand the value investment to secure your future. SIP for beginners is a basic core to let you know how truly you can enjoy your first paycheck. There’s this urge to celebrate — a new phone, a trip, dinner out every other night. Nothing wrong with any of that. But somewhere between the celebration and the next paycheck, most of us miss a quiet window that never really opens this wide again.

That window is the gap between “I have no financial responsibilities yet” and “I have financial responsibilities I can’t avoid.” And the best tool for that window is SIP which most people postpone for years.

They are 100% safe but not guaranteed. The risks involve which kind of mutual fund investors seek to invest in (equity, debt, or hybrid) not the process itself. 

What Is a SIP?

SIP stands for Systematic Investment Plan. Strip away the jargon and it’s simple — you invest a fixed amount, usually into a mutual fund, at regular intervals (usually monthly), instead of putting in one large sum at once.

Think of it like a gym membership for your money. You don’t need a big lump sum to start. You just need to show up consistently, month after month, and let the process do its work.

Why Your First Salary Is the Ideal Starting Point

There’s a reason financial advisors keep repeating this, even though it sounds like a cliché: time is the one resource that actually multiplies your money for you.

When you invest early, you’re not just investing your money — you’re investing years. And years, thanks to compounding, behave less like addition and more like multiplication.

Say you invest ₹5,000 a month starting at age 23, versus someone who starts the same amount at age 33. Assuming a similar average return over time, the person who started ten years earlier could end up with a corpus that’s not just proportionally bigger — it could be several times larger by retirement. The extra decade at the start does more work than an extra decade added at the end.

This isn’t about being lucky or picking the “right” fund. It’s about giving your money the maximum amount of time to grow.

Read More 👉 Your Credit Score Ignores 90% of Your Financial Life — What Your First Credit Card Changes 

How To Manage SIP Along With Your Daily Expenses

This is a fair point. Rent, EMIs, family contributions, that gym membership you forgot to cancel — early salary life is expensive. But this is exactly why starting small matters more than starting big.

A SIP doesn’t demand a large amount. Many funds let you start with as little as ₹500 a month. The goal in your first year isn’t to build wealth overnight — it’s to build the habit of paying your future self before you pay for anything else.

Pay yourself first, Instead of saving whatever’s left after spending, you flip the order — invest first, spend what remains.

Maintain Your Psychology To Empower Yourself Financially

Your spending habits calcify fast. The lifestyle you build in your first two years of earning tends to become your baseline. Once you get used to spending your entire salary, increasing that SIP amount later feels like a sacrifice, even if you’re earning more.

Starting a SIP with your first paycheck means your lifestyle grows around a slightly smaller number from day one. You never miss what you never got used to spending.

Read More 👉 Collateral vs No Collateral Loan Amount Where Collateral Starts Making Financial Sense

How To Avoid Common Mistakes — SIP For Beginners

Waiting for the “right” market conditions. SIPs are designed to work through ups and downs — that’s the entire point of investing at regular intervals instead of timing the market.

Choosing funds based on friends’ recommendations. What worked for your colleague may not match your goals or risk appetite.

Stopping the SIP the moment markets dip. Volatility is normal, not a signal to panic. Long-term SIPs are built to absorb short-term noise.

Not linking the SIP to an actual goal. A vague “let me just invest” often loses motivation. Tying it to something — a house down payment, early retirement, a five-year trip fund — makes it easier to stay consistent.

A Simple SIP For Beginners Way to Start

You don’t need a finance degree or a stockbroker uncle to get going. Most banking apps and investment platforms let you set up a SIP in under ten minutes:

1. Pick a fund category based on your goal and time horizon (equity for long-term growth, debt for shorter, safer goals).

2. Decide an amount you can commit to without stress — even a small one.

3. Automate it. Set the SIP date right after your salary credit date so it happens before you have a chance to spend it.

4. Increase it gradually as your income grows — many platforms let you “step up” your SIP automatically each year.

Read More 👉 Switching Jobs? Don’t Ignore Your EPF, NPS, and Mutual Fund Investments 

Conclusion

Nobody regrets starting a SIP early. Plenty of people regret waiting for the “perfect moment” that never quite arrives. Your first salary isn’t just your first taste of financial independence — it’s the cheapest, most flexible starting line you’ll ever get for long-term wealth building.

Start small. Start messy if you have to. Just start with the first one. A SIP for beginners guide will help you understand everything from why it is important to how to start, you just have to decide how much you can give for your future.

This post is for general awareness and educational purposes only. Mutual fund and SIP returns are subject to market risk. Please evaluate your own financial goals, risk appetite, and consult a financial advisor before making investment decisions.

Leave a Comment

Your email address will not be published. Required fields are marked *

How AI Could Change India’s Digital Public Infrastructure

Digital Public Infrastructure 

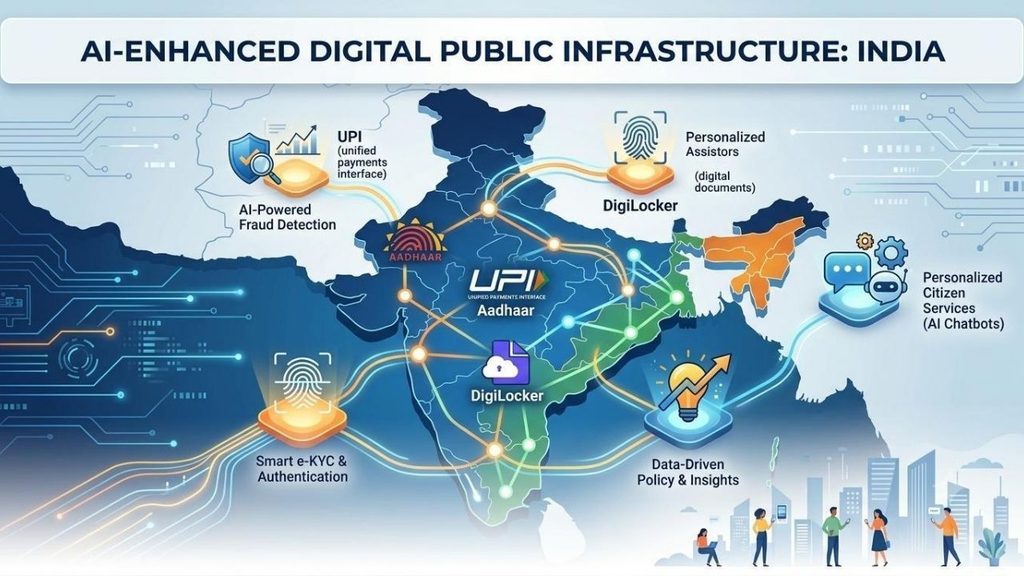
The shift from traditional systems to Digital India raises concerns about public privacy and security, as greater reliance on digital systems can create new opportunities for fraud and scams. Aadhaar is one pillar of what the government now calls India’s Digital Public Infrastructure and how AI could change that DPI for making it faster and more reliable is the biggest evolution.

Every month, close to 20 million people across India get turned away by a fingerprint scanner or a face-authentication camera that’s supposed to hand them a subsidised ration bag, a pension, or a bank withdrawal. That failure rate — a little over 6% of roughly 312 million Aadhaar-based authentications attempted monthly has stayed almost unchanged for a decade, according to UIDAI’s own parliamentary disclosures. 

It’s a strange fact to sit with, because DPI includes the stack of identity, payments, and data-sharing rails — Aadhaar, UPI, DigiLocker, Account Aggregator, ONDC — that more than a billion Indians touch, often without realising it. AI is now being wired into nearly every one of those rails. Some of it is already live and working. 

What Is India’s Digital Public Infrastructure 

Aadhaar is the identity layer — a biometric ID held by nearly every adult in the country. UPI is the payments layer, the real-time system that lets any bank app talk to any other. DigiLocker and Account Aggregator are the document and data-sharing layers, letting people share verified paperwork or consented financial records instead of photocopies. 


ONDC is the newest piece, an attempt to do for e-commerce what UPI did for payments: an open network any app can plug into, rather than one company owning the marketplace. 

Each of these was built as plumbing — deliberately boring, interoperable infrastructure. AI is the first layer being added on top that isn’t boring at all, and it’s arriving fastest in fraud detection, credit, language, and now shopping.

Fraud Detection at a Scale No Human Team Can Watch

UPI now clears more than 750 million transactions a day, a number NPCI expects to keep climbing toward a billion. At that volume, catching fraud after the money has moved is close to useless — NPCI’s fraud-detection platform processes roughly 2 terabytes of transaction data daily and needs to score risk within about 20 milliseconds, fast enough to block a payment before it settles. 

Its MuleHunter AI tool has already flagged more than 4.7 lakh mule accounts — the disposable, borrowed accounts fraud rings use to bounce stolen money through four to six hops before cashing out. 

NPCI is now piloting what it calls a “federated model” with three or four banks: instead of pooling everyone’s raw transaction data in one place, banks and NPCI compare AI-generated risk scores on a customer, getting the benefit of shared pattern-matching without centralising anyone’s actual financial history. 

NPCI’s leadership has said openly that the next leg of UPI’s growth depends on AI doing three jobs at once — catching fraud, extending credit based on payment history, and onboarding the next half-billion users through voice and regional-language interfaces instead of English-only screens.

Half of India Still Can’t Access Bank Credit

For decades, an MSME owner without three years of clean, bankable paperwork was mostly invisible to formal lenders — not un-creditworthy, just un-scoreable. 

The Account Aggregator framework, built on the RBI’s 2016 Master Direction and NITI Aayog’s Data Empowerment and Protection Architecture, changed the plumbing: with a customer’s explicit consent, a lender can now pull real bank statements, GST filings, and insurance records through a single encrypted pipe instead of chasing PDFs. 

As of the framework’s fourth anniversary in 2025, 112 financial institutions had gone live on both sides of that pipe, with hundreds more connected as data providers or users. AI models sit on top of that data flow, and lenders report the payoff is real: industry estimates put improvements in default-prediction accuracy at 15 to 25%, and processing times that used to run one to three weeks are increasingly settled same-day. 

This isn’t unregulated black-box lending, though — RBI’s digital lending rules require a lender to explain, in terms a risk officer or auditor can actually interrogate, why a model approved or rejected an application, which puts a real ceiling on how opaque these systems are allowed to get.

Read More 👉 Apple iPhone Duo Changes the Cost Effectively With These Methods

No More Language Barrier: Treating Language Like Infrastructure

India has more than one language and an AI layer that drops the barrier between languages is Bhashini. In India, MeitY’s National Language Translation Mission became fully AI-powered translation engines and it now sits underneath every government services app from January 2026. Portals like DigiLocker, UMANG, e-Shram running into 22 Indian languages. 


A Bhashini-powered voice assistant called Kumbh Sahaiyak used a Llama-based model to field pilgrim questions in 11 languages in real time — arguably the clearest proof yet that a DPI project can meet people in their own language at genuine crowd scale, not just in a pilot deck. If India’s Digital Public Infrastructure’s whole promise was ever about reaching people who can’t fill out an English form, Bhashini is the piece actually doing that, one API call at a time.

The Part AI Might Not Fix: Aadhaar’s Exclusion Problem

The government’s current bet is that AI-driven face authentication — rather than fingerprint or iris scanning, which struggle with a manual labourer’s worn fingerprints or an elderly person’s cataracts — will close that 6.5% failure gap. 

It’s already been tested at real scale with UIDAI ran a face-authentication proof of concept at NEET-UG 2025 exam centres with the NTA and NIC, and by 2026 similar AI-camera verification, backed by liveness checks and a fingerprint or manual fallback, was standard at UPSC exam halls. Officials describe the results as promising. 

Researchers who’ve actually gone door to door are less convinced: a survey across 32 villages in Jharkhand by economist Jean Drèze and co-authors found exclusion errors running as high as 20% in areas where biometric authentication was required for every ration purchase — and critics note that swapping fingerprints for face scans doesn’t remove the underlying design flaw, which is that a single biometric check, controlled by a ration dealer or bank teller rather than the beneficiary, decides whether someone eats that month. 

There’s a second, quieter concern sitting alongside is the more AI systems sit on top of Aadhaar-linked data — UPI payments, SIM registrations, app logins — the easier it becomes to assemble a detailed behavioural profile of someone, usually described publicly as fraud prevention rather than surveillance. Both things can be true at once. 

AI-based face authentication may genuinely cut into the 20-million-a-month failure count, and the same infrastructure may quietly expand what the state and private platforms can see about a person’s life. That tension, not a clean technical fix, is the actual story here.

Agents That Could Soon Shop and Transact for You

The newest layer is barely a layer yet. ONDC, India’s government-backed alternative to Amazon and Flipkart, runs on the open-source Beckn protocol, which had onboarded more than 900 network participants across grocery, food delivery, mobility, and financial services by 2026. 

FIDE, the nonprofit behind Beckn, has already demonstrated BecknGPT — an experimental agent that lets a ChatGPT-style assistant browse and complete an ONDC purchase on a shopper’s behalf and mainstream apps including Swiggy, BigBasket, and Flipkart have started exposing their catalogues directly to AI shopping assistants. 

It’s genuinely early, more demo than daily habit right now. But the direction matters: if UPI proved India could build a public payments rail that private apps compete on top of, ONDC plus AI agents is the government’s bet that the same model can work for commerce itself, without any single platform owning discovery.

Read More 👉 Bihar STET 2026 Online Form Out: Check Exam Syllabus and Pattern To Get Teacher Job

Why Other Countries Are Copying India’s Homework

Whatever India’s Digital Public Infrastructure domestic wrinkles, India has turned it into one of its more effective diplomatic exports. 

During its 2023 G20 presidency, India pushed Digital Public Infrastructure as a global development model, the framework receiving endorsement from 20 member nations. By 2026, the cooperation agreements between India and other 23—24 countries have been signed for helping them build their own version of Aadhaar, UPI, or DigiLocker by sharing open-source blueprints rather than selling a finished product. 


UPI itself is already live in eight-plus countries, from the UAE and Singapore to France and Mauritius, and Kenya is reportedly building a national digital-identity stack directly modelled on India’s approach. 

Analysts who track this call it the “Aadhaar Paradox”: India is exporting a model with real, unresolved problems at home — the exclusion numbers above, heavy market concentration in UPI apps, ongoing data-protection debates — alongside genuine, population-scale successes that few other countries have managed. 

Both halves of that sentence are true, and any AI layer India bolts onto its own DPI will likely travel abroad along with everything else.

What Determines Changing India’s Digital Public Infrastructure With AI Goes Well

A few concrete things to watch over the next year, rather than general optimism about AI transforming governance. 

First, whether NPCI’s 30% market-share cap for individual UPI apps — currently set to take effect December 31, 2026 — actually holds this time, since two apps still control more than 80% of transaction volume and AI-driven credit and voice features could widen that gap further or finally give smaller players something to compete on. 

Second, whether UIDAI’s AI-based face authentication measurably moves the 6.5% Aadhaar failure rate in its next couple of annual disclosures, or whether as analyzer expect — it just changes which biometric ends up failing people. 

None of these are settled yet. Both will tell you, faster than any government press release, whether AI made India’s Digital Public Infrastructure more inclusive, or just faster at doing the same thing to the same people.

Read More 👉 NBEMS NEET PG Answer Key 2026: How To Download & Calculate Your Score

Conclusion 

AI could make India’s Digital Public Infrastructure faster, more accessible, and better at handling problems that humans simply cannot manage at this scale. From spotting fraud across UPI transactions to helping lenders understand small businesses and breaking language barriers, the benefits are already becoming visible. 

But the bigger question isn’t whether AI can make India’s Digital Public Infrastructure more efficient. It’s whether it can make it more inclusive without creating new problems along the way. Aadhaar’s authentication failures, concerns around data profiling, and the risk of AI-powered systems becoming harder to challenge show why speed alone isn’t enough.

India has already built the digital rails. The next phase is about deciding how intelligently, transparently, and fairly AI runs on top of them. The success of that shift will depend not just on better models, but on whether the people using these systems actually have fewer barriers when they need them most.

Leave a Comment

Your email address will not be published. Required fields are marked *

Voice-to-Notes Tools for Students: Study Faster Without Typing

Voice-to-Notes Tools

Voice-to-Notes Tools are really helpful from turning large study lectures into simple notes in just few minutes. Writing everything down is an old fashion technique that takes a lot of time for a few pages notes but everything is going easy with fast pacing technologies. Whether it’s hours of session or long research sheets, enabling speech to text is the smarter way to take notes. 

You’re forty minutes into a lecture, the professor has moved through three concepts, and your notes still say “photosynthesis — light reaction —” because your hand gave up before your brain did. Speaking runs at roughly 150-160 words a minute while typing tops out around 40 for most people. 

That gap is the entire case for Voice-to-Notes Tools , and for Indian students juggling coursework in English, Hindi, or a regional language, the tool you pick matters more than the concept itself — because most of the tools were built for American office meetings, not for Indian classrooms. 

Best Voice-to-Notes Tools For Indian Students 

There are plenty of tools that can turn your voice into text but then you find an error — spelling, whole different word (except, accept), not able to turn your regional language — that’s because it doesn’t understand. Some AI integrated voice tools that turn your every word into text without major errors is here:

Gboard Voice Typing — free, and it’s already on your phone

Before downloading anything, check what you have. Google’s Gboard keyboard has an in-built voice typing feature which you can use by clicking on the mic icon. If the icon is invisible then enable it from the setting so Voice-to-Notes can be easy and quick without downloading any new app.


It works in Hindi plus eight regional languages — Bangla, Gujarati, Kannada, Malayalam, Marathi, Tamil, Telugu, and Urdu — Indian students can use this keyboard in any app that takes input in the same language, not just Google’s own apps. 

For a student jotting quick revision notes in Hindi between classes, this is the lowest-friction option because there is no signup, no subscription, no separate app to remember to open.

Google Recorder — real-time transcription, best if you have a Pixel

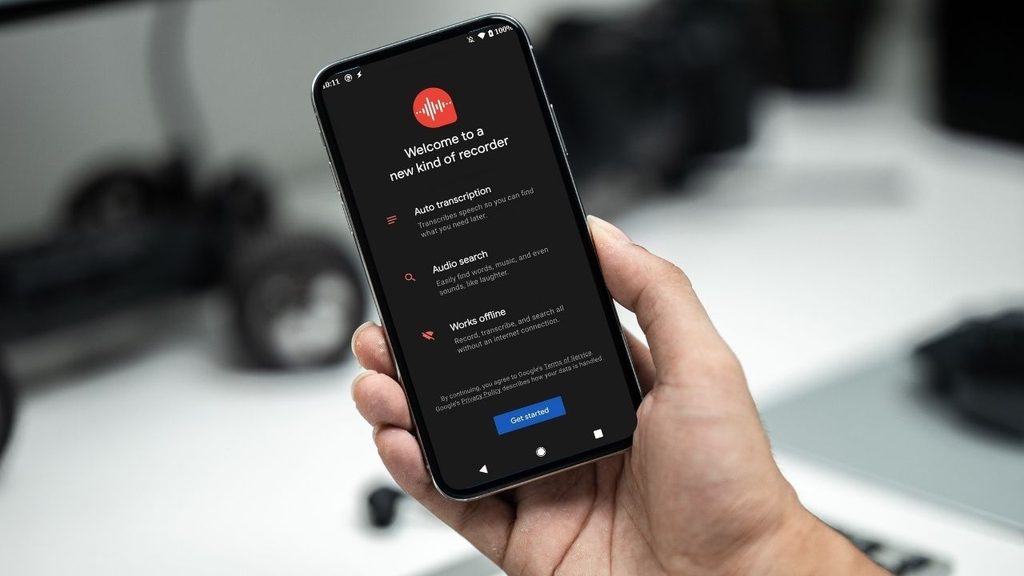
Google Recorder transcribes live as you speak and runs the processing on-device, which matters if your hostel Wi-Fi is unreliable. The catch: it’s tied to Pixel phones for its full real-time transcription experience, so if you’re on a different Android device or iPhone, this one’s off the table.

Otter.ai — good for English lectures, but it skips Hindi entirely

Otter is the name that comes up first in most “best Voice-to-Notes Tools” lists, and for English-medium lecture capture it’s genuinely capable — live transcription, speaker labels, searchable transcripts. 

The free tier gives you 300 minutes of transcription a month, capped at 30 minutes per recording, which covers maybe eight or nine standard lecture sessions before you hit the wall. The Pro plan runs $16.99/month billed monthly, or roughly $8.33/month if you pay annually (about $99.99/year). 

But for Indian students: Otter’s transcription supports English and a small set of other languages — Spanish, French, German, Japanese, Chinese depending on the source you check — but not Hindi or Indian regional languages. If your coursework happens in Hindi medium, Otter simply won’t understand you, no matter which plan you’re on.

Wispr Flow

Wispr Flow is the strongest option because it works inside almost any application. Students who want long-form writing and fast drafting can use this tool but unlimited dictation requires a subscription, which costs around $15 per month or $12 per month when billed annually. Since it supports more than 100 languages and gives accuracy for names and jargon along with AI editing, the cost is worth it.

VoiceToNotes.ai 

Its features include real-time transcription, grammar correction, AI summaries so it can become a useful tool for students which turn spoken thoughts into structured notes. Some professionals consider this tool as more affordable than many full-featured AI assistants but free usage is limited. The catch: accuracy still depends on microphone quality and background noise.

Mindgrasp

Mindgrasp is primarily an AI learning and content-understanding platform. Students can use it for lectures and study material — it helps in creating flashcards and quizzes automatically. Best for exam preparation and research but some features are tied to specific subscription tiers. 

Lisup 

Lisup focuses on accessibility and hands-free writing. It can be used across desktop applications so access will be easy and it is specifically designed for in-place speech-to-text features. It’s not built for broader use but enough for students to take notes easily. 

Soniox — the app actually built for Hindi dictation

Soniox is less well-known in student circles but solves exactly the gap Otter leaves open. It handles Hindi across regional varieties like Khariboli and Braj Bhasha, works system-wide across any app or text field on your phone rather than locking you into one note-taking interface, and covers 60-plus languages total with the ability to switch languages mid-sentence. 


It’s useful if you naturally code-switch between Hindi and English while explaining a concept to yourself. It’s free to start, with weekly free credits rather than a hard monthly cap, and the company states it doesn’t store your recordings or use them for model training, which is worth knowing if you’re dictating exam-prep notes you’d rather keep private.

Sarvam AI — worth watching, not quite a student app yet

Sarvam is India’s most-funded sovereign AI company, and its speech models (Saaras v3) handle 22 Indian languages with genuinely strong accuracy claims. But as of now, Sarvam’s product lineup is built mainly for enterprises — voice agents for banks and government call centers, APIs for developers — rather than a polished consumer app you’d install and use for lecture notes. 

A consumer-facing voice app was announced in February 2026, aimed at exactly this kind of mass-market, multilingual use case, but a public launch isn’t happening right now.

Read Also 👉 Why ChatGPT Ads Deserve a Place In Your 2027 Media Plan 

Why Do Students Need These Tools?

Most of the time students missed points while trying to understand the same topic simultaneously. Writing it down on paper or in a mobile is the same thing — it consumes a lot of time and misses points. So, these Voice-to-Notes Tools help students take notes without tiring their hands. 

There are some free and some paid tools, if you just need to take notes of what your processor is explaining then a free tool is enough for you. But if you are a Ph.D student or you need to do heavy research, organize every note, and make summaries from online content, you need a tool which can handle all of that, even if it costs you a little.

Which Speech-to-Text Tools are Best For Studies?

Google’s Gboard keyboard is the best free Voice-to-Notes Tools which I have used personally and crafting many documents in English, Hindi and Urdu. I recommended to students who wanted to take notes before exams and stop writing everything manually and waste their time. 


Gboard offers unlimited access to use on any other applications like docs, word, and on any device (mobile or laptop). Most of the students take their mobile to the college, so it runs smoothly. But sometimes it makes minor errors in spelling which you can edit later. 

Second is Wispr Flow but you have to pay after a limited use and many students can’t afford it but those who can afford can consider Wispr Flow as the best tool for making notes.

Read Also👉 Upgrade Laptop Like New Model In Low Budget

Conclusion for Voice-to-Notes Tools

The world is changing and for solving traditional problems by adapting new technology. One of the old problems is taking notes in a mid-session in your classrooms. Students have to understand the topic and write down their important concepts — two jobs at once.

If they forgot, they have to ask other students and it appears a problem if you don’t have a lot of friends. So the problem is solved now, you can spend your time to understand the topic without worrying about the notes as these Voice-to-Notes Tools do that job for you.

Leave a Comment

Your email address will not be published. Required fields are marked *

Switching Jobs? Don’t Ignore Your EPF, NPS, and Mutual Fund Investments 

Jobs

Your resignation letter is signed, the new offer is accepted, and you’re ready for switching Jobs but what happens to the EPF account and should the new company’s NPS enrollment change anything about how you’re already investing through mutual funds? Don’t Ignore your EPF, NPS and Mutual Fund which most people already are doing.

The EPF vs NPS vs mutual funds decision isn’t really one choice — it’s three separate accounts with three different rules, and a job switch is exactly the moment most people either transfer things correctly or lose track of money they’ve already earned.

What Is EPF, NPS, and Mutual Funds

EPF — 8.25% for FY 2025-26, third year running at that rate, govt-backed, EEE (contribution, interest, withdrawal all tax-free if you cross 5 years’ continuous service). Mandatory for salaried staff at covered establishments; you don’t really “choose” this one, you’re already in it.

NPS — Market-linked, mix of equity/debt/govt bonds you can allocate; extra ₹50,000 deduction under 80CCD(1B) on top of the 80C limit. At exit, minimum 40% of the corpus must go into an annuity — you don’t get the whole pot in cash, and annuity payout rates in India have historically been mediocre (5–6% range).

Mutual funds — No lock-in except ELSS (3 years); LTCG/STCG taxed, no EEE treatment. Best long-run equity return potential of the three, but zero forced discipline — nothing stops you from redeeming during a panic.

Don’t Ignore Your EPF, NPS, and Mutual Funds After Switching Job

Your EPF doesn’t “carry over” automatically. A lot of people assume EPF just follows them to the new job. It doesn’t — not unless you actually transfer it.

When you leave a company, your EPF account under that employer becomes inactive. Your new employer opens a fresh account. If you don’t link the two using your UAN (Universal Account Number), you end up with multiple EPF accounts scattered across your career. Each one earns interest for a while, but an account that stays inactive for 36 months stops earning interest altogether.

How To Set Up Your EPF Account After Job Switch

  • Use the “One Employee One EPF Account” (OEEOA) transfer request on the EPFO portal, or let your new employer initiate it.
  • Don’t withdraw your EPF just because it feels like “extra cash” during the job switch. Withdrawing before 5 years of continuous service makes it taxable, and you lose out on decades of compounding.
  • Check your UAN is correctly linked to Aadhaar and your new employer’s establishment ID — half of all transfer delays come from mismatched KYC details.

The instinct to cash out is understandable when you’re between Jobs and expenses are piling up. But EPF is one of the few instruments giving you a stable, tax-free return over the long run. Treat withdrawal as a last resort, not a bonus.

Read More 👉 Your Credit Score Ignores 90% of Your Financial Life — What Your First Credit Card Changes 

Check Your NPS Before Leaving the Company

Your NPS account isn’t tied to your employer at all. It’s tied to you, through your PRAN (Permanent Retirement Account Number). So technically, nothing needs to be “transferred.”

But there’s a catch. If your NPS contribution was happening through your employer under the corporate NPS model, that contribution stops the day you resign. Your new employer may or may not offer an NPS benefit. If they don’t, your account doesn’t close but it goes silent unless you start contributing on your own through the eNPS platform or a POP (Point of Presence).

What to check:

  • Confirm your new employer’s NPS deduction is active and linked to your existing PRAN — don’t let them create a second one by mistake.
  • If your new company doesn’t offer NPS, decide if you want to keep contributing voluntarily. Many people simply let it sit, which defeats the purpose of consistent, long-term retirement investing.
  • Update your bank and nominee details after the switch — this is the most commonly skipped step.

NPS rewards discipline more than any other retirement product because of how compounding and low fund management costs stack up over 20-30 years. A gap of even a couple of years in contributions has a real, measurable impact on your final corpus.

Mutual funds: the SIPs nobody remembers to check

Job switches usually come with a change in salary account, and that’s where mutual fund SIPs quietly break. If your SIP auto-debit was linked to your old salary account and you close that account (or stop maintaining the minimum balance), your SIP simply fails. Most people don’t notice for months — until they check their portfolio and realize three or four SIP cycles never went through.

What to do immediately after switching:

Re-link your SIP mandates to your new primary bank account, or keep enough balance in the old one until the transition is smooth.

Review your asset allocation. A new job often means a new salary, new expenses, maybe new financial goals (relocation, higher rent, a shorter or longer commute cost). Your SIP amounts should reflect your current life, not your old one.

If you got a signing bonus or relocation allowance, resist the urge to let it sit in a savings account. Even a lump sum top-up into an existing fund puts that money to work instead of losing value to inflation.

What Happens If You Neglect These Procedures

None of this is complicated. It’s just easy to postpone because nothing about it feels urgent in the middle of a job change. But delayed EPF transfers lose interest. Paused NPS contributions lose compounding years you can’t get back. Broken SIPs mean missed market cycles.

A Jobs switch is one of the few moments where you’re forced to look at your entire financial setup at once — new salary, new perks, new expenses. Use that moment. Spend one weekend afternoon logging into EPFO, checking your PRAN, and confirming your SIPs are active. It’s boring, unglamorous work. It’s also the difference between a retirement corpus that actually reflects your career and one that has quiet, unexplained gaps in it.

Your new job deserves your excitement. Your old investments deserve five minutes of your attention before you move on.

Read More 👉 Collateral vs No Collateral Loan Amount Where Collateral Starts Making Financial Sense

Conclusion

Switching Jobs is exciting but don’t ignore your EPF, NPS, and mutual funds investment as it is a chance to reset your financial checklist. Your EPF needs to be transferred, your NPS needs to stay linked to your PRAN, and your mutual fund SIPs need to keep running without interruption.

You don’t have to choose between EPF vs NPS vs mutual funds, understanding the role each plays in your long-term financial plan is important. EPF provides retirement stability, NPS adds a dedicated retirement investment option, while mutual funds offer greater flexibility and growth potential.

Leave a Comment

Your email address will not be published. Required fields are marked *

Festive Season Sale In October Is About to Reshape Smartphone Prices in India 

Festive Season Sale

This year’s Festive Season Sale In October will bring many new offers and discounts on electronic products — massive offers hit on smartphones. If you’ve been sitting on an upgrade — whether that’s finally moving off a three-year-old Galaxy or jumping into the iPhone ecosystem for the first time — this is the window the entire Indian smartphone retail calendar builds toward. 

When the sale is live, which smartphone will actually get a discount and what’s coming to this season, know everything before planning around.

When Does the Festive Season Sale Start?

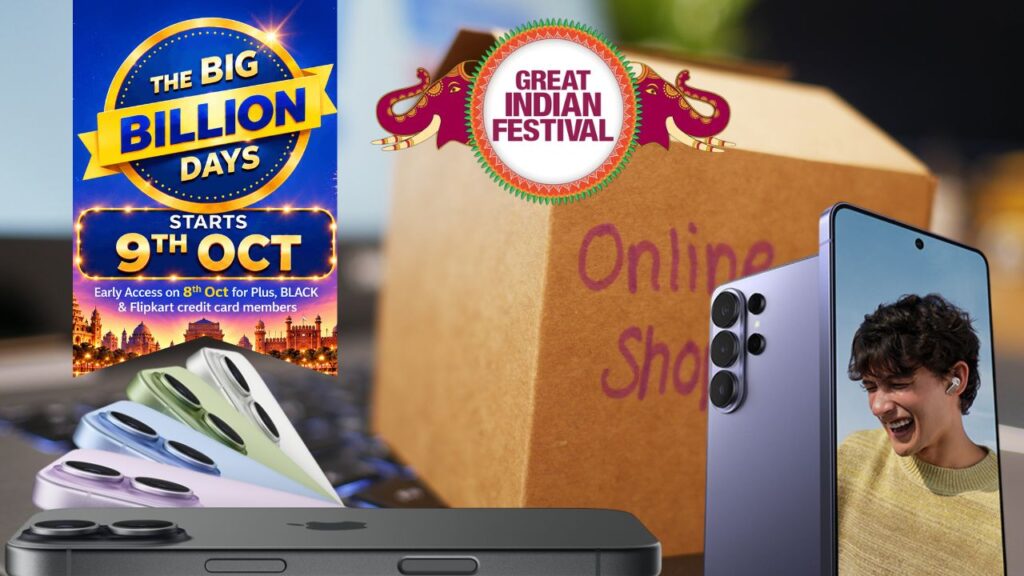
The Amazon Great Indian Festival 2026 is going live on October 8 with no closing date, so treat this as a multi-week sale. Prime members get early access from October 7. This Festive Season Sale has flagged on many categories, including mobile phones, electronics, home appliances, and fashion. With 160,000 seasonal jobs secured by Amazon to handle the load, this shows how big this year’s event is expected to be.

Flipkart’s Big Billion Days 2026 goes live for everyone on October 9, a day after Amazon, with early access on October 8 for Flipkart Plus, Flipkart Black and select co-branded credit card holders. Flipkart has also been running a slower build-up than usual: Early Bird Deals started September 24, and official price reveals on flagship phones have been trickling out since September 26.

October 7–9 for early access across both platforms, then the main event running through most of October. If you’re the type who wants to plan a purchase around the calendar rather than react to a flash notification, mark October 7 as your first checkpoint.

What Discounts and Bank Offers to Expect

Neither platform has published final smartphone pricing yet — genuinely, this is one area where numbers are still moving daily, and anyone claiming exact final prices two weeks out is guessing. What’s confirmed on the banking side is more solid:

On Amazon, SBI credit and debit card users get a flat 10% instant discount on eligible transactions, including EMI purchases, and Amazon has said overall discounts across electronics could run up to 80%, with an additional 10% on top for SBI cardholders. There’s already a Prime Coupon Bonanza running ahead of the main event, offering up to ₹6,000 off select Samsung and Sony televisions — a hint at how aggressive the electronics category is shaping up to be.

On Flipkart, Axis Bank and ICICI Bank cardholders get a 10% instant discount on eligible debit and credit card transactions, Flipkart Plus and Black members get up to 12% additional card discount, and Bajaj Finance EMI options are being pushed hard for higher-ticket purchases like flagship phones. Flipkart is projecting discounts climbing as high as 90% across electronics, appliances, fashion and home decor — though that ceiling figure almost always applies to accessories and older inventory rather than current-generation flagships.

Best Smartphone Deals Expected This Festive Season

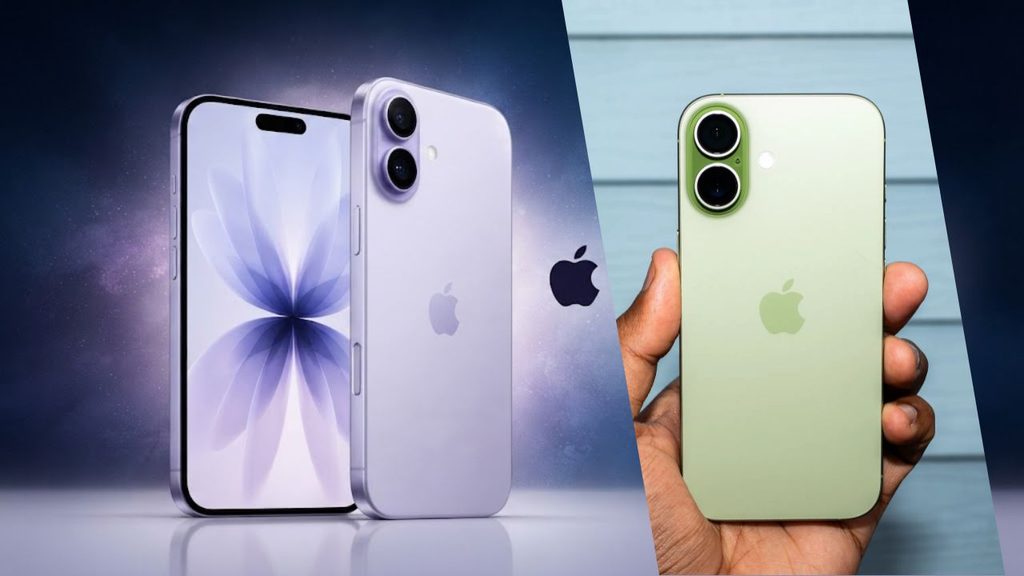
1. iPhone 17 (256GB) — Best for iOS Upgraders on a Budget

The launch price of iPhone 17 is ₹82,900 for 256GB storage but if you purchase 512GB, the price rises up to ₹1,02,900. Flipkart’s dropping iPhone 17 price under ₹80,000 during Big Billion Days. From above Rs 1 lakh to Rs 80 thousand, the difference is quite big.


At a sub-₹80,000 price point, this is the cheapest true current-generation iPhone has ever launched into a festive sale with outstanding features including 6.3-inch Super Retina XDR display, A19 chip, dual rear camera system. It is available in 5 colours — Black, White, Mist Blue, Sage and Lavender.

Limitation: You still don’t get the telephoto lens or ProMotion display that the Pro models carry, so heavy zoom-shooters and gamers chasing 120Hz will feel the gap. But a perfect model for anyone upgrading from an older iPhone who needs a clear camera and high-end features.

👉 Why ChatGPT Ads Deserve a Place In Your 2027 Media Plan 

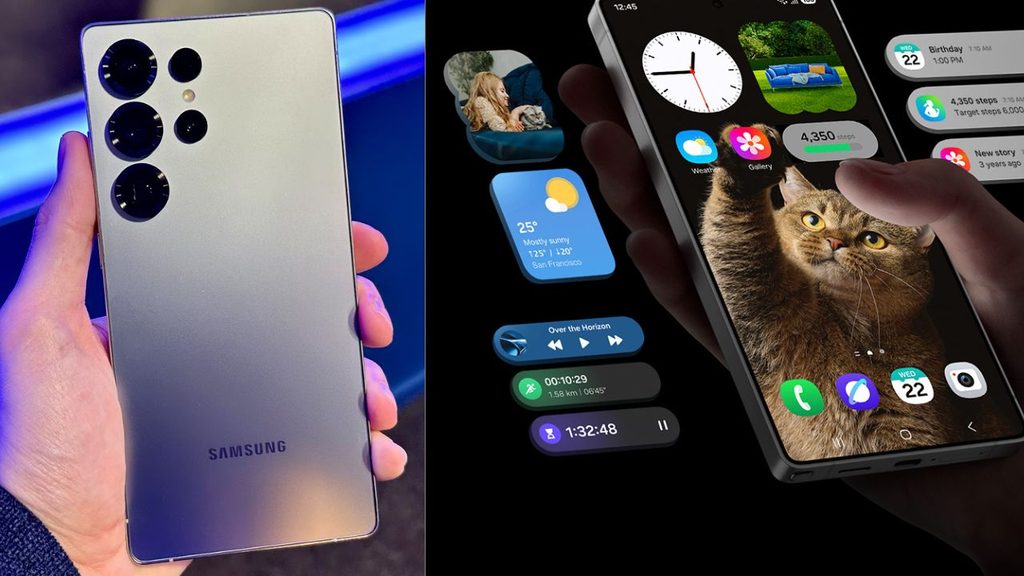
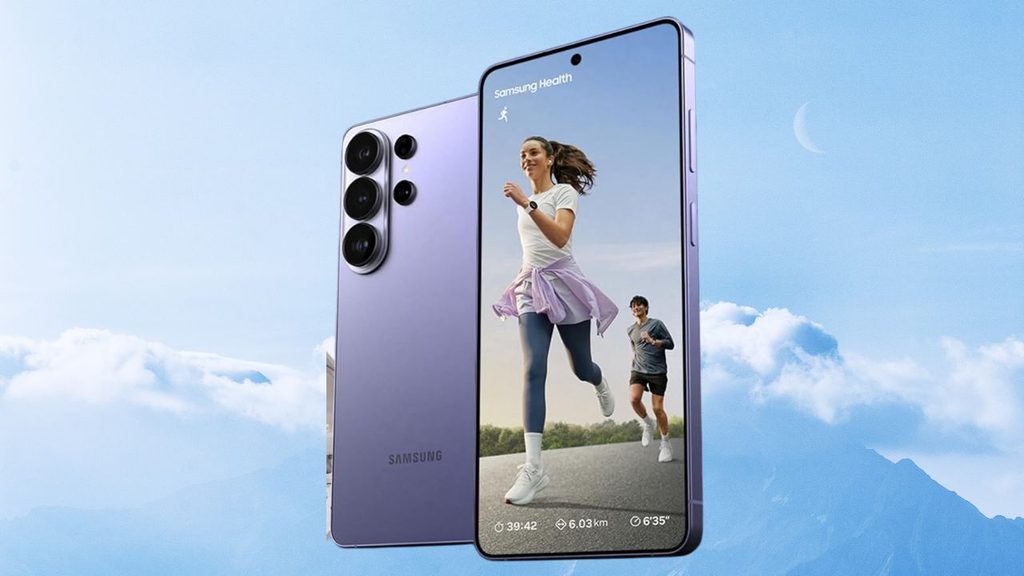
2. Samsung Galaxy S25 Ultra — Best Flagship Value Pick

Samsung put the launching price ₹1,29,999 on Galaxy S25 Ultra which was around ₹84,999 after a discount during Amazon’s July Prime Day and as low as ₹94,999 during the May Great Summer Sale and both offers flagged by the same retailer. Now it’s preparing for the festive push. Expect festive pricing to land in a similar ₹85,000–₹95,000 band.


You’re getting a phone that was a ₹1.3 lakh flagship a year ago for roughly two-thirds the
price. Buyers who are searching for best cameras and display smartphones can afford the Snapdragon 8 Elite for Galaxy chipset, which still holds up against 2026 competition. The flagship specifications 6.9-inch Dynamic AMOLED 2X display at up to 2,600 nits brightness, 12GB RAM, titanium frame with Corning Gorilla Armor 2 glass. 

Limitation: It’s now the previous generation — no Galaxy S26’s Snapdragon 8 Elite Gen 5 or the newer Privacy Display feature, and Samsung’s software support clock started a year earlier than on the S26.

3. Samsung Galaxy S26 Ultra — Best for the Latest Hardware

Another Samsung’s flagship model launched in 2026 at ₹1,39,999 for 12GB+256GB and for higher storage, price rises up to ₹1,59,999 for 512GB and ₹1,89,999 for 16GB+1TB. This smartphone is delivering a high-end technology — Snapdragon 8 Elite Gen 5 for Galaxy, 6.9-inch display and first built-in Privacy Display for limiting side-angle screen visibility. The festive offer lands near ₹1,24,999 because July sale cuts to the same.


A 200MP main camera with an absolute hardware system which can’t be broken easily. Buyers who are looking for 2026 latest smartphones at a range over 1 lakh, this is the best time to think about it.

Limitation: Because it’s this fresh, don’t expect S25 Ultra–style 35% festive cuts. If your budget caps around ₹1 lakh, the S25 Ultra is the more realistic festive buy.

4. Samsung Galaxy S25 FE — Best Mid-Flagship Pick

Flipkart teased S25 FE deals alongside the S25/S25 Ultra as part of its Big Billion Days smartphone lineup, Galaxy S25 FE discounted prices will land near ₹60,000. Buyers who can’t afford S26 Ultra for the series design language and camera hardware, this one provides them the same two features at an affordable range in this festive season.

Limitation: Detailed specs and confirmed pricing are still pending official reveal — if you need certainty before buying, wait for Flipkart’s price-reveal window closer to the sale date rather than an early-bird listing.

👉 Apple iPhone Duo Changes the Cost Effectively With These Methods

Compare iPhone 17 vs. Galaxy S25 Ultra On an Overview

iPhone 17 (256GB)Galaxy S25 Ultra (256GB)
Expected festive priceUnder ₹80,000₹85,000–95,000 (based on recent 2026 sale pricing)
Display6.3″, Super Retina XDR6.9″, Dynamic AMOLED 2X, 2,600 nits
Standout strengthCleaner ecosystem, resale valueBigger screen, S Pen support, titanium build

If display size and a stylus matter more to you than the Apple ecosystem, the S25 Ultra is the better festive buy at a comparable post-discount price. If you want the newest chip generation with the smallest footprint, the iPhone 17 wins.

Don’t Lock Into One Platform Too Early

Amazon and Flipkart are running near-identical bank-offer structures this year, but the specific phone deals won’t be identical — Samsung’s S25 Ultra pricing has historically differed by a few thousand rupees between the two platforms in past sales, and the same is likely this October. 

Check both listings once early access opens on October 7–8 before finalising a purchase; a single-retailer comparison isn’t a real comparison.

👉 Upgrade Laptop Like New Model In Low Budget

Conclusion

If your budget is under ₹80,000 and you want the newest possible chip, wait for the iPhone 17’s Festive Season Sale price to drop and buy it in the first 48 hours of early access — historically, the steepest festive cuts on genuinely new-generation phones show up early, before stock tightens.

If you’re chasing flagship specs on a ₹85,000–95,000 budget, the Galaxy S25 Ultra is the stronger buy this cycle, since last year’s flagship pricing has already proven it can fall that far. And if you specifically want Samsung’s newest chip and can stretch past ₹1.2 lakh, hold out for the S26 Ultra rather than compromising — buying older hardware you’ll regret in a year isn’t really a discount.

One practical step regardless of which phone you pick: add it to your Amazon or Flipkart wishlist now, and note the current listed price before October 7. That’s the only way to verify a “festive discount” is real rather than a price that was quietly bumped up the week before the sale.

Leave a Comment

Your email address will not be published. Required fields are marked *

Scroll to Top