SIP For Beginners: Best Time To Start is Your First Salary  

SIP

If you are a fresher then you should understand the value investment to secure your future. SIP for beginners is a basic core to let you know how truly you can enjoy your first paycheck. There’s this urge to celebrate — a new phone, a trip, dinner out every other night. Nothing wrong with any of that. But somewhere between the celebration and the next paycheck, most of us miss a quiet window that never really opens this wide again.

That window is the gap between “I have no financial responsibilities yet” and “I have financial responsibilities I can’t avoid.” And the best tool for that window is SIP which most people postpone for years.

They are 100% safe but not guaranteed. The risks involve which kind of mutual fund investors seek to invest in (equity, debt, or hybrid) not the process itself. 

What Is a SIP?

SIP stands for Systematic Investment Plan. Strip away the jargon and it’s simple — you invest a fixed amount, usually into a mutual fund, at regular intervals (usually monthly), instead of putting in one large sum at once.

Think of it like a gym membership for your money. You don’t need a big lump sum to start. You just need to show up consistently, month after month, and let the process do its work.

Why Your First Salary Is the Ideal Starting Point

There’s a reason financial advisors keep repeating this, even though it sounds like a cliché: time is the one resource that actually multiplies your money for you.

When you invest early, you’re not just investing your money — you’re investing years. And years, thanks to compounding, behave less like addition and more like multiplication.

Say you invest ₹5,000 a month starting at age 23, versus someone who starts the same amount at age 33. Assuming a similar average return over time, the person who started ten years earlier could end up with a corpus that’s not just proportionally bigger — it could be several times larger by retirement. The extra decade at the start does more work than an extra decade added at the end.

This isn’t about being lucky or picking the “right” fund. It’s about giving your money the maximum amount of time to grow.

Read More 👉 Your Credit Score Ignores 90% of Your Financial Life — What Your First Credit Card Changes 

How To Manage SIP Along With Your Daily Expenses

This is a fair point. Rent, EMIs, family contributions, that gym membership you forgot to cancel — early salary life is expensive. But this is exactly why starting small matters more than starting big.

A SIP doesn’t demand a large amount. Many funds let you start with as little as ₹500 a month. The goal in your first year isn’t to build wealth overnight — it’s to build the habit of paying your future self before you pay for anything else.

Pay yourself first, Instead of saving whatever’s left after spending, you flip the order — invest first, spend what remains.

Maintain Your Psychology To Empower Yourself Financially

Your spending habits calcify fast. The lifestyle you build in your first two years of earning tends to become your baseline. Once you get used to spending your entire salary, increasing that SIP amount later feels like a sacrifice, even if you’re earning more.

Starting a SIP with your first paycheck means your lifestyle grows around a slightly smaller number from day one. You never miss what you never got used to spending.

Read More 👉 Collateral vs No Collateral Loan Amount Where Collateral Starts Making Financial Sense

How To Avoid Common Mistakes — SIP For Beginners

Waiting for the “right” market conditions. SIPs are designed to work through ups and downs — that’s the entire point of investing at regular intervals instead of timing the market.

Choosing funds based on friends’ recommendations. What worked for your colleague may not match your goals or risk appetite.

Stopping the SIP the moment markets dip. Volatility is normal, not a signal to panic. Long-term SIPs are built to absorb short-term noise.

Not linking the SIP to an actual goal. A vague “let me just invest” often loses motivation. Tying it to something — a house down payment, early retirement, a five-year trip fund — makes it easier to stay consistent.

A Simple SIP For Beginners Way to Start

You don’t need a finance degree or a stockbroker uncle to get going. Most banking apps and investment platforms let you set up a SIP in under ten minutes:

1. Pick a fund category based on your goal and time horizon (equity for long-term growth, debt for shorter, safer goals).

2. Decide an amount you can commit to without stress — even a small one.

3. Automate it. Set the SIP date right after your salary credit date so it happens before you have a chance to spend it.

4. Increase it gradually as your income grows — many platforms let you “step up” your SIP automatically each year.

Read More 👉 Switching Jobs? Don’t Ignore Your EPF, NPS, and Mutual Fund Investments 

Conclusion

Nobody regrets starting a SIP early. Plenty of people regret waiting for the “perfect moment” that never quite arrives. Your first salary isn’t just your first taste of financial independence — it’s the cheapest, most flexible starting line you’ll ever get for long-term wealth building.

Start small. Start messy if you have to. Just start with the first one. A SIP for beginners guide will help you understand everything from why it is important to how to start, you just have to decide how much you can give for your future.

This post is for general awareness and educational purposes only. Mutual fund and SIP returns are subject to market risk. Please evaluate your own financial goals, risk appetite, and consult a financial advisor before making investment decisions.

Leave a Comment

Your email address will not be published. Required fields are marked *

Your Dollar Income Isn’t Fixed: How INR Volatility Changes Freelancers Earning 

INR Volatility

If you are a student or IT engineer and have a side freelancing business then exchange rate updates is the second in your search list. Once you understand Impact of Exchange Rates On Freelancers In India and how it moves forward then you can earn a little more. Let’s take a look at some important points to understand INR Volatility isn’t about what you’re actually thinking.

You raised the invoice in August. $1,000, net 30, client in Austin. By the time the payment actually lands in your account in September, the number in rupees isn’t what you calculated when you sent it. Maybe it’s more. Maybe it’s less. Either way, you didn’t do anything different — the client paid exactly what they owed — and your income still moved. 

That gap is what most freelancers mean when they say the rupee is “volatile,” and most of them are only half right about what that word actually costs or earns them. 

Current Changes In INR Volatility 

As of September 9, the dollar was trading around ₹95.13, after touching two-month highs near ₹94.4 the week before on the back of sustained Reserve Bank of India intervention. Zoom out to the 12-month view, the rupee has weakened roughly 8% against the dollar over the past year. For a freelancer billing in USD, that’s not a warning sign — it’s a raise you didn’t ask for.

Run the math on a flat $1,000 invoice. At a rate near ₹88 (roughly where the pair sat a year ago, working backward from the reported annual move — treat this as an approximation, not a verified historical quote), that invoice cleared around ₹88,000. 

At today’s rate, the same $1,000 clears closer to ₹95,000. Same client, same scope, same invoice — ₹7,000 more in your account, before any platform fees. If your Gigs, your budgeting, or your client pricing only accounts for the dollar amount, you’re missing the part of your income that moved on its own.

Why “Volatile” Doesn’t Mean “Falling” 

If you thought “the rupee is volatile” means “the rupee is always losing value, brace yourself.” But that’s not what volatility means, and it’s not what the data shows. The rupee gained about 0.9% in the week leading into September 9, with the RBI actively defending the band using its foreign exchange reserves. A currency that can move up or down 1% in a week, depending on which government or central bank decides to act, is unpredictable — not one-directional.

The near-term pressure right now is coming from oil. Brent crude jumped roughly 8% to around $97 a barrel after US-Iran tensions escalated, and India imports the overwhelming majority of the crude it uses, so a sustained spike pushes the rupee the other way — weaker, which again works in a dollar earner’s favor, but also raises input costs across the economy, indirectly squeezing the Indian clients some freelancers also serve. 

Layer on the US Federal Reserve’s meeting scheduled for September 15–16, where a rate move could swing global dollar demand overnight, and you’ve got a currency pair reacting to three or four separate levers in the same month. Betting on “the rupee only goes one way” is how freelancers get caught flat when it doesn’t.

Read More 👉 UP Anganwadi Bharti 2026 — District-Wise Vacancies & Recruitment Details

Impact of Exchange Rates On Freelancers In India

Here’s the part that costs freelancers real money and rarely makes it into the currency conversation: the spread between the rate you see on Google and the rate you actually receive. This gap is usually bigger than the market’s actual weekly movement. And it fills only when you understand Impact of Exchange Rates On Freelancers In India.

PayPal is the most expensive route by a wide margin — a cross-border transaction surcharge that can run up to 4.4%, stacked with a currency markup of roughly 3.5–4.5%, pushes total cost toward 6% on some routes. 

Payoneer, common for Upwork and Fiverr payouts, charges around 1% to move funds to your bank plus an FX markup that can reach 2% on withdrawal into a different currency — so a $2,000 month can quietly lose $50–60 to fees that never show up as a single visible number. 

Wise is the outlier: it settles at the mid-market rate — the actual number you’d see on Google — with a transparent fee that’s usually under 1% for most USD-to-INR transfers, which is why it’s become the default for freelancers paid directly by clients rather than through a marketplace.

None of that shows up when you’re only watching the headline USD/INR number. A freelancer who tracks the exchange rate obsessively but invoices through PayPal is optimizing the wrong variable.

Read More 👉 Foreign Education Loan Currency Explained: How INR Depreciation Can Increase Your Loan Cost 

How To Check Your USD Income is Moving Forward

Stop checking “what’s the rupee doing today” in isolation. Three things move it, and all three are trackable without a finance degree: RBI intervention behavior (visible in how tightly the rate is held to a band, like the ₹94.5–95.3 range this week), Fed rate decisions (scheduled, public, and usually priced in days ahead), and oil price swings (Brent crude, since India’s import bill is the direct transmission line into rupee weakness or strength).

Practically, that means two things for how you run your freelance income. First, match your payout method to your income source — Payoneer if most of your work comes through marketplaces, Wise if you invoice direct clients — because the fee gap between them is often larger than a month’s currency movement. 

Second, if you’re pricing recurring retainers in USD, revisit them quarterly rather than annually; an 8% currency shift plus a fee structure you haven’t audited in a year is easily a 10–12% swing in what a “fixed” retainer actually pays you in rupees.

Your dollar invoice was never the number that mattered. The rupee number that hits your account is — and that number has three separate forces acting on it before you even get to the part your payment platform quietly takes.

Read More 👉 Planning MBBS or Master’s Abroad? Country-Wise Costs, Loan Limits and Lenders

Conclusion 

For Indian freelancers, earning in dollars doesn’t mean earning a fixed amount. The USD/INR rate, RBI and Fed decisions, oil prices, and payment-platform fees can all change what finally reaches your bank account. A $1,000 invoice can be worth noticeably more or less in rupees without the client changing a thing.

The smart move isn’t to predict the impact of Exchange Rates On Freelancers In India. It’s to understand how currency movements affect your real income, compare payout fees, and review your USD pricing regularly. For IT students planning to freelance or work with overseas clients, learning this early can help turn Dollar Income into something you can actually budget around.

Leave a Comment

Your email address will not be published. Required fields are marked *

Best Noise-Cancelling Headphones for Online Classes and Mock Tests 

Headphones

You’re 40 minutes into a 3-hour mock test, deep into the reasoning section, and someone two floors down starts drilling a wall. Or it’s your neighbor’s TV bleeding through during a live online class, right when the teacher explains the one concept you actually needed. With best Noise-Cancelling Headphones, it is possible to block the noise out the room, stays comfortable for hours, and doesn’t die halfway through a session. 

As that kind of interruption doesn’t just annoy you — it costs you marks and attention you can’t get back. The right pair of Noise-Cancelling Headphones for online classes and mock tests is meant for this. Not just any Headphones — most people don’t need studio-grade audio for a lecture or a test window. Here are best picks that actually do that, across different budgets.

Why ANC Matters More for Exams Than for Music

Active noise cancellation in short ANC, helps prevent outside noise with an inverse sound wave by using a microphone and it is so effective on low-frequency and steady sound like traffic, fans, washing machine, TV, and construction site but less effective random sharp noises like barking or door slamming.

For a 2-3 hour mock test, that steady cancellation is what keeps your focus from draining. For live classes, you also need a decent mic, since ANC alone won’t help your teacher hear you over a ceiling fan.

Best Noise-Cancelling Headphones for Online Classes and Mock Tests

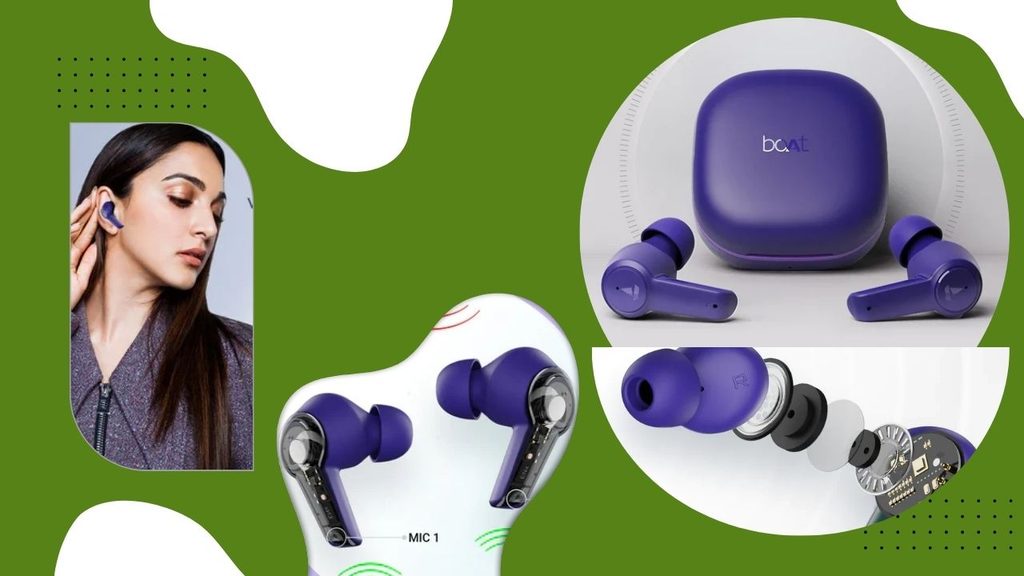
1. boAt Airdopes 413 ANC — ₹1,999

  • 25dB Active Noise Cancellation
  • ENx dual-mic technology for calls
  • ~20 hours total battery (earbuds + case)
  • In-ear TWS design


This is about as cheap as real ANC gets in India, and it holds up for what it is — steady background noise gets noticeably duller, which is the whole point during a test. The case battery isn’t huge, so charge it the night before a long mock test rather than assuming it’ll carry you through a full day.

Best for: the tightest possible budget where any real ANC beats none.

2. Boult Audio Omega — ₹2,499

  • Active Noise Cancellation + separate ENC chip for calls
  • 4 mics per stem, touch controls
  • ~32 hours total battery (8hr earbuds + 24hr case)
  • Dedicated Game Mode for low latency

The separate ENC chip is the standout here — it’s built for call clarity, which matters if your online classes involve a lot of back-and-forth with the teacher rather than passive listening. If you are also looking for gaming purposes, not just for mock test sessions then low-latency mode is an additional benefit in Boult Audio Omega.

Best for: students who have live classes and online courses to attend rather than recorded lectures.

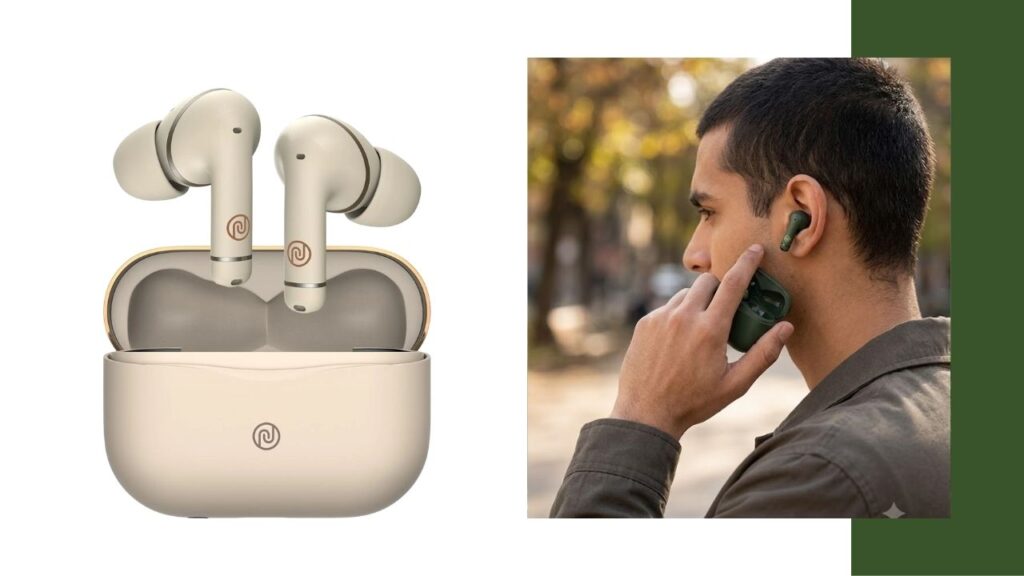
3. Noise Buds Solo — ₹2,999

  • Active Noise Cancellation with switchable Transparency mode
  • 10mm driver, touch controls for calls/music/voice assistant
  • ~36 hours total battery (7hr earbuds + case)
  • Interchangeable eartips for fit
Noise Buds Solo


The 36-hour total battery is the best in this budget tier, and the switchable Transparency mode is genuinely handy — flip it on for five minutes if someone’s calling you from another room, without pulling an earbud out mid-test. Interchangeable eartips also make a bigger difference than you might realize; a bad seal will ruin passive noise isolation even before ANC activates. 

Best for: the best all-round earbud pick under ₹3,000 if battery life is your priority.

Read More👉 Best Laptops for Coding and Programming: Top Picks for Every Budget

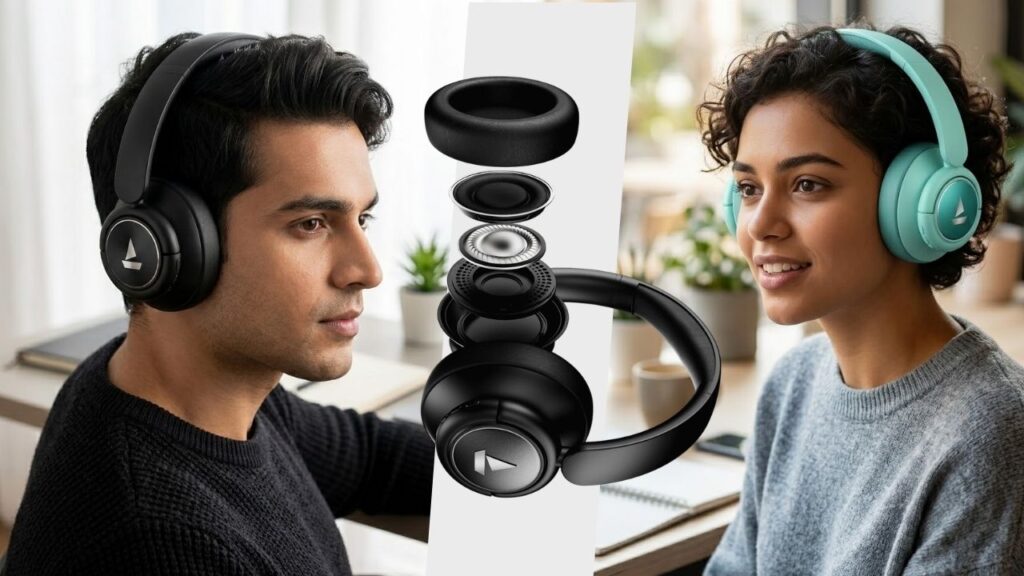
4. boAt Rockerz 450 ANC — ₹2,499–2,999

  • Hybrid ANC (up to 25dB reduction)
  • 20-hour battery life with ANC on
  • 40mm dynamic drivers, BEAST mode for low-latency audio
  • On-ear, foldable design
boAt Rockerz 450 ANC


This is the one to get if you just need to shut out a noisy house without spending a month’s pocket money. The ANC won’t touch a jackhammer, but it flattens fan noise, traffic hum, and a TV in the next room reasonably well. The ear cushions get a little warm after 2+ hours, and call clarity is average — fine for a mock test, less ideal if you’re live-unmuting often in class.

Best for: students on a tight budget who mainly need ANC for silent, focused test-taking.

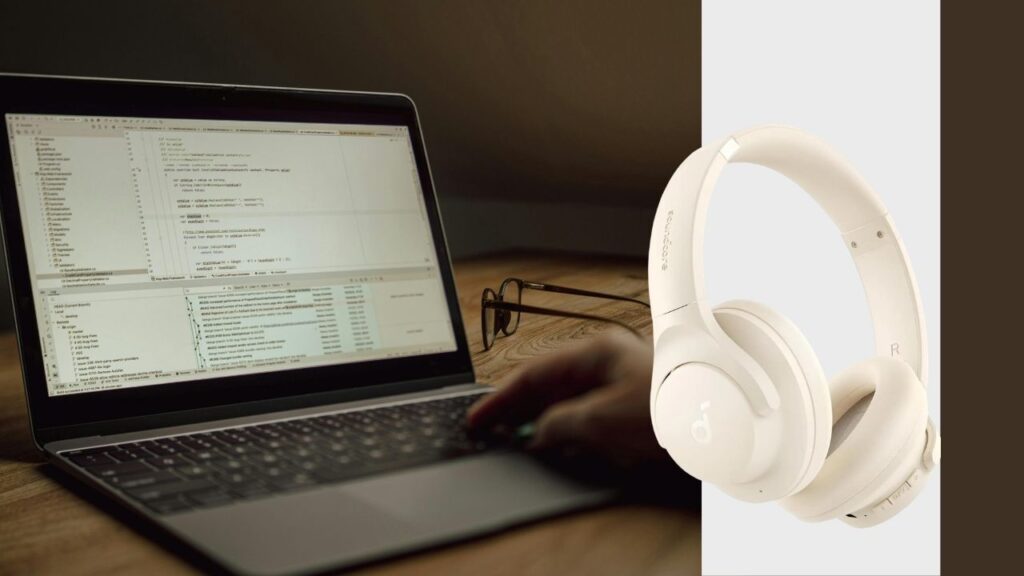
5. Soundcore Q20i — ₹4,298

  • Hybrid ANC with Indoor/Outdoor/Transport modes
  • 40-hour battery life with ANC on
  • Soft protein-leather earcups
  • Wired mode available (3.5mm) when the battery does die
Soundcore Q20i


The battery life here is the real selling point — 40 hours means you could go through an entire mock-test series for a week without touching the charger. The Indoor mode specifically tunes the ANC for steady household noise rather than street sound, which is exactly the scenario most Indian students are dealing with. The bass is a bit boosted for critical listening, but for lectures and tests that’s irrelevant.

Best for: anyone who forgets to charge things — this Noise-Cancelling Headphones forgives you.

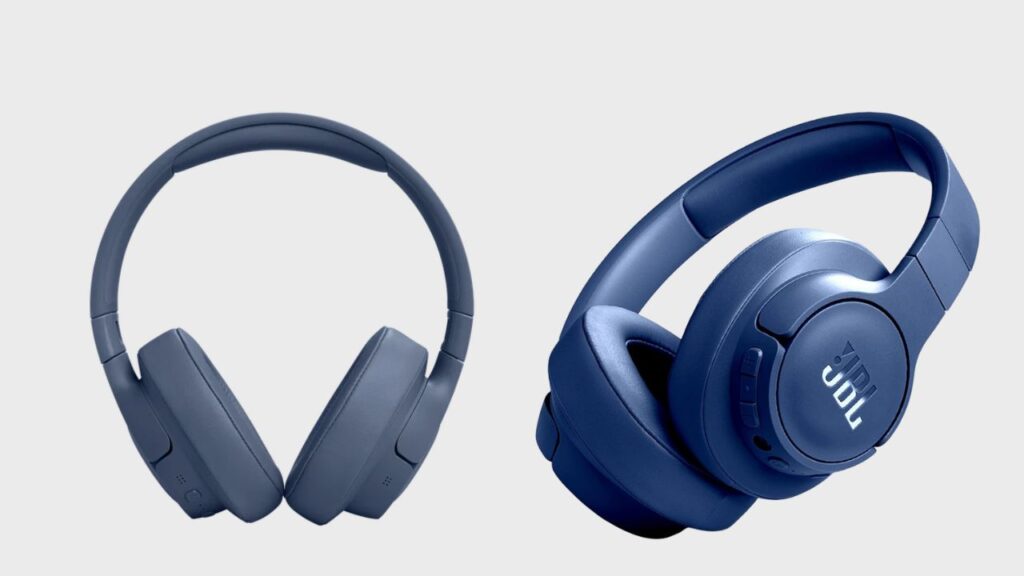
6. JBL Tune 770NC — ₹8,999–10,999

  • Adaptive ANC that responds very quickly to the surrounding noise automatically
  • 50-hour battery life (ANC off), around 44 hours with ANC on
  • Multipoint Bluetooth (connect to phone and laptop simultaneously)
  • 40mm drivers with JBL Signature Sound
JBL Tune 770NC

The multipoint pairing is genuinely useful if you attend classes on a laptop but take calls or check notifications on your phone — no fumbling with Bluetooth settings mid-lecture. Adaptive ANC means it automatically dials up cancellation when your maid starts sweeping and dials back down when it’s quiet, instead of a fixed on/off toggle. Bass is JBL’s usual signature — punchy, a little forward — which some people love and others find a bit much for spoken-word content.

Best for: students juggling both a laptop for classes and a phone for everything else.

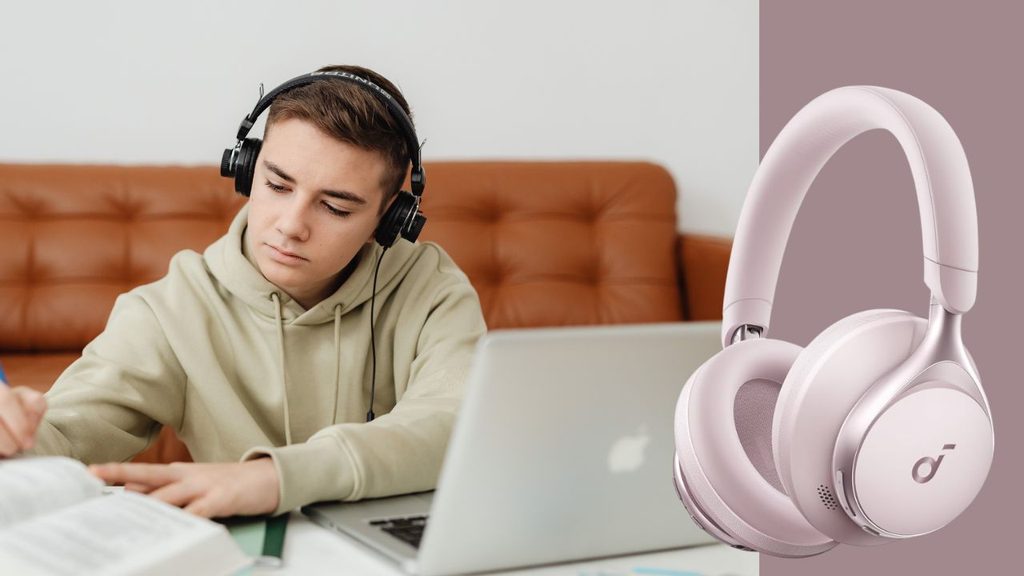
7. Soundcore Space Q45 — ₹9,999 (often available around ₹8,500–9,000 on sale)

  • Adaptive ANC rated up to 98% noise reduction
  • 50-hour battery life with ANC on
  • LDAC support for Hi-Res audio over Bluetooth
  • Memory foam earcups, app-based custom EQ

This is the closest thing to flagship-level ANC without paying flagship prices. The 98% noise reduction figure holds up well against consistent background noise — the kind you get from a busy street or a joint family household during the day. Good memory foam cushions really do make a difference during a 3-hour test because your ears are not sore at the end. The app is actually useful, allowing you to choose a “study” EQ preset that cuts mid-bass boom, making spoken word clearer while you’re studying or attending lectures.

Best for: the best all-round pick if you want near-premium ANC without the premium price tag.

Read More👉 Best Student Loans for College Students

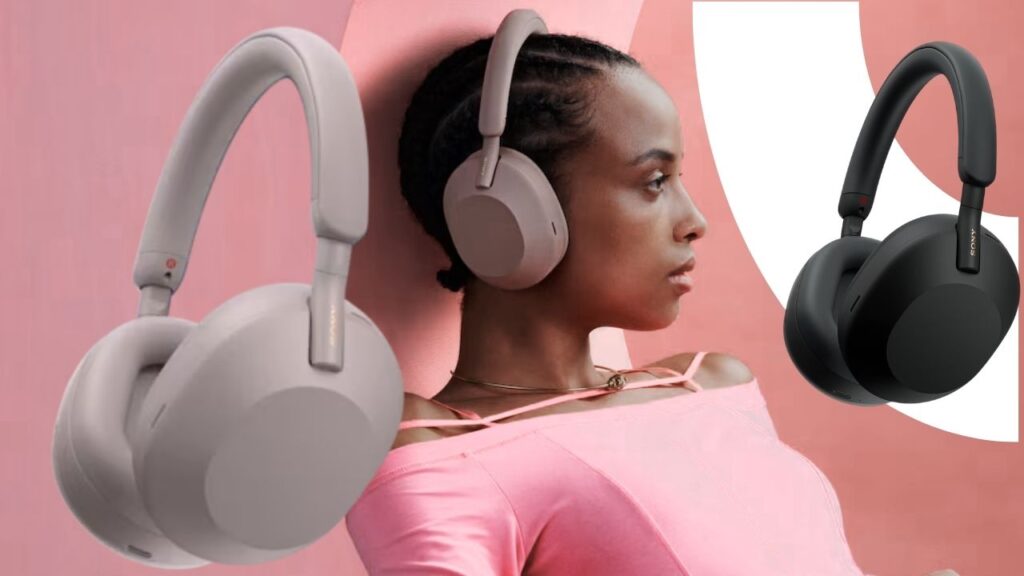
8. Sony WH-1000XM5 — ₹29,990

  • Industry-leading ANC with 8-microphone array and dual processors
  • 30-hour battery life with ANC on
  • Speak-to-Chat: automatically pauses audio when you start talking
  • Precise Voice Pickup Technology for clearer calls
Sony WH-1000XM5

If your budget stretches this far, the XM5 is close to overkill for a student use case — but that’s not a bad thing. A duo which makes you feel like you are sitting in an exam hall rather than your house. When you’re nervous your voice gets lower that people sitting behind the system couldn’t understand but Sony WH-1000XM5 gives an automatic Speak-to-Chat feature that pauses automatically if you say something out loud and passes your lower voice very smoothly. But this is too expensive for students but college students who strictly need can buy it on EMI

Best for: students who treat this as a long-term investment across school, coaching, and eventually work-from-home use.

Sony WH-1000XM5 vs Soundcore Space Q45

Sony WH-1000XM5Soundcore Space Q45
Price₹29,990₹9,999
ANC strengthBest-in-class, handles sudden noise tooExcellent against steady noise, weaker on sudden sharp sounds
Battery (ANC on)30 hours50 hours
Mic quality for classesBest on this listGood, not exceptional
Value for a student budgetLow — premium pricingHigh — near-flagship ANC at a third of the price

If money weren’t a factor, the XM5 wins outright. For a student budget, though, the Space Q45 gets you 80-90% of the noise-cancelling experience for roughly a third of the price, plus a longer battery — which matters more than most people expect once exam season gets long.

Which Noise-Cancelling Headphones Should You Buy?

If you’re prepping for a single exam cycle and want the smallest possible spend, go with the boAt Rockerz 450 ANC or the Soundcore Q20i — either will hold up fine for mock tests where mic quality doesn’t matter. If you’re attending daily online classes on top of tests and need reliable multipoint connectivity, the JBL Tune 770NC earns its price. 

And if you’re looking for one pair that will cover you throughout years of coaching, college, and then working remotely, the Soundcore Space Q45 is the best value for money on this list, with the Sony WH-1000XM5 as the upgrade option if budget genuinely isn’t an issue. 

All of Noise-Cancelling Headphones are available on Amazon.in and Flipkart, boAt and Sony also sell directly from their own India stores if you want manufacturer warranty support without a third party seller in the mix. Prices above reflect typical listings as of August 2026 and do fluctuate with sale events — worth a quick price-check before you check out.

boAt Rockerz 450 ANC vs Noise Buds Solo

boAt Rockerz 450 ANC (Over-ear)Noise Buds Solo (Earbuds)
Price₹2,499–2,999₹2,999
Noise blockingANC + passive seal from ear cupsANC only, weaker passive isolation
Comfort for 2-3 hr sessionsBetter for most — no in-ear fatigueSome users get ear fatigue past 90 min
Battery20 hours~36 hours total (earbuds + case)
PortabilityFoldable but bulkierFits in a pocket

If you’re choosing between a headphone and earbuds at roughly the same price, format matters more than spec sheets here. Over-ear wins on raw silence for a long test window; earbuds win on battery life and portability if you’re carrying them between home, coaching class, and a library.

Read More 👉 How to Apply for a Student Loan to Get a Higher Education & Make Career

Conclusion

Best Noise-Cancelling Headphones for online class and mock tests are not always the expensive ones. For most students, the Soundcore Space Q45 provides the best combination of ANC, comfort, battery life, and price, while the boAt Rockerz 450 ANC and Soundcore Q20i are better choices for those on a tighter budget. 

If money is not an issue, the Sony WH-1000XM5 offers the best overall experience. In the end, decide based on the length of your studies, the noise level of your environment and whether you need better microphones or portability in addition to noise cancellation. 

Leave a Comment

Your email address will not be published. Required fields are marked *

Business Ideas for Students With Zero Investment — Easy Startup Guide

Business Ideas

Your semester fees just went out, your parents already transferred money twice this month, and asking again feels wrong. Meanwhile, half your hostel WhatsApp group is talking about someone in third year who’s making pocket money reselling kurtis on Instagram, and another guy is tutoring juniors for ₹500 an hour between classes. You’ve got a laptop, a phone, and more free time than you think — what you don’t have is capital. That’s fine, because none of the Business Ideas for students with zero investment below need any.

It’s a practical rundown of what students in India are actually doing right now to earn without touching their savings or taking a loan — plus how to do it without your attendance or your grades taking the hit.

Why Students Need These Business Ideas

Your parents are already paying the education cost in lakhs. Tuition, hostel fees, textbooks, and the occasional weekend trip are climbing faster than your father’s income. You thought of eating maggi at dinner to save the money but it won’t help. Customer service jobs or fixed shifts at retail shops pay the working hours so it affects your studies and classes. These Business Ideas for students are flexible, even if you start small, you can keep earning through referrals, repeat orders and content that stays active while you’re busy in exams. 

There’s a second reason that matters just as much: what you build now becomes proof of work later. A recruiter reading “ran a 200-follower food page that landed three restaurant collaborations” or “sold ₹40,000 worth of handmade jewellery on Instagram over one semester” is reading initiative, sales sense, and follow-through — things a transcript can’t show. 

Freelance platforms like Fiverr and Upwork, and reselling apps like Meesho, have made the entry point for all of this genuinely free; you’re not renting a shop or buying inventory, you’re renting your own time.

How to Manage a Startup With Your Studies?

The honest risk with any student business is letting it eat into exam prep. A few ground rules keep that from happening:

  1. Block fixed hours, not “free time.” “I’ll work on it when I’m free” usually means never. Pick two or three specific slots a week — say, 7–9 PM on Tuesdays and Thursdays — and treat them like a lab session you can’t skip.
  2. Start with one product or one client, not five. Trying to tutor, resell, and run a YouTube channel in the same month usually means all three stay half-finished. Pick one, get it earning something small and consistent, then add the next.
  3. Use what your campus already gives you for free. Wi-Fi, a decent camera on a hostel-mate’s phone, a common room for shoots, a WhatsApp broadcast list of 60 classmates — that’s most of the “startup cost” covered before you spend a rupee.
  4. Protect exam weeks on purpose. Pause client work or batch your content a week in advance before internals and end-sems. A business that costs you a backlog isn’t worth running.
  5. Treat semester breaks as your test lab. Two months without lectures is the best window to try an idea at full speed and see if it’s worth continuing during term time, or if it was only ever a break-time project.

Read More👉 Best Laptops for Coding and Programming: Top Picks for Every Budget

Business Ideas for Students With Zero Investment

Each of these can be started with a phone, an internet connection, and whatever skill or spare time you already have. No inventory to buy, no shop to rent.

1. Tutoring & Trainer

If you’re good at a subject, a language, or even a sport, someone younger is struggling with exactly that right now. Offline, this means tutoring school kids in your neighbourhood or juniors in your own course during exam season. 

Online, platforms like Vedantu, Superprof, and Unacademy let you list yourself as a subject tutor without paying a listing fee, and you can also just post in your college’s WhatsApp/Telegram groups. Beyond academics, “trainer” covers fitness coaching, yoga sessions, or teaching a musical instrument over video call — anything you already know how to do.

2. Reselling Products

Reselling apps let you sell fashion, home, and lifestyle products through your own WhatsApp and Instagram without holding stock — the supplier ships directly to the buyer. Meesho is the platform most Indian resellers currently use for this. You share a product link, add your margin, and the platform handles logistics. It’s genuinely zero-investment because you never buy stock upfront. You can purchase for yourself and make review videos for Youtube — a content idea that helps your channel monetize and receive more brand promotions.

3. Handmade & Crafted Items

If you make jewellery, resin art, candles, crochet pieces, or hand-painted items, you already have a product — you just need a shopfront. Instagram works as a free storefront on its own; a basic Shopify store is an option once orders pick up, though Shopify does charge a subscription once your free trial ends, so weigh that against your order volume first. 

College fests and flea markets are also underrated distribution: a single fest stall can outsell a month of Instagram posts because people can touch the product before buying.

4. Local Influencer

You don’t need lakhs of followers to start earning as a food, travel, or campus-news page — brands doing local marketing often care more about engagement rate than follower count. 

A food page covering canteens and local eateries near campus, a travel page documenting budget weekend trips, or a campus-news account covering fests and placements can all start picking up small paid collaborations once the page has a real, active audience — even a few thousand followers.

5. Share Your Skills on YouTube

Teaching what you know on camera works because the content keeps earning views long after you upload it. Coding walkthroughs, recipe videos, DIY room-decor tutorials, study-with-me sessions, or a “learn Spanish in 10 minutes” series are all formats students are already running successfully. 

YouTube’s Partner Programme requires a watch-hour and subscriber threshold before ad revenue kicks in, so early on this is more about building an audience and a portfolio than instant income — brand deals usually arrive before AdSense money does.

6. Graphic Design

If you can put together a clean logo, an Instagram carousel, or a poster, small businesses and even fellow students will pay for it — most don’t have an in-house designer. Canva’s free tier is enough to start; Canva Pro is worth the (still low) cost only once you have paying clients. 

Fiverr is the easiest place to list design gigs with zero setup cost. Print-on-demand — designing T-shirts, mugs, or phone cases that a platform like Redbubble prints and ships only when someone orders, is the same skill applied to a physical product, again with no inventory risk.

7. Social Media Management and Content Writing

Small businesses — a local salon, a café, a tuition centre — often know they need Instagram content but don’t have time to make it. Managing 2–3 such accounts for a monthly fee is realistic freelance work you can do from a hostel room. 

Content writing runs in parallel: blogs, product descriptions, and SEO articles are in constant demand, and platforms like Upwork and Contentmart are common entry points for beginners. If you’d rather build something of your own instead of freelancing for others, a niche newsletter or blog you grow yourself can eventually monetise through ads or sponsorships too.

Read More👉 How to Apply for a Student Loan to Get a Higher Education & Make Career

8. Repairing Mobiles and Laptops

Every hostel has someone with a cracked screen, a dead battery, or a laptop that won’t boot, and most students don’t want to make a trip to a service centre for something small. If you’re comfortable with basic hardware fixes and software troubleshooting — clearing malware, reinstalling an OS, replacing a battery — you can build a reputation purely through word of mouth in your own hostel block. This one scales slowly but has almost no competition on campus.

9. Making/Selling Notes, and Reselling Old Books

Well-organised, exam-focused notes are worth real money to juniors who’d rather buy clarity than make it themselves. Selling PDF notes or a compiled formula sheet through your class WhatsApp group costs you nothing but the time you’d have spent making them for yourself anyway. 

The same logic applies to old textbooks and reference books gathering dust after your exams — sell them directly to incoming juniors or through campus resale groups instead of letting them sit unused.

10. Tiffin or Food Delivery on Campus

Hostel food gets old fast, and a home-style tiffin service run out of your own kitchen (or a family member’s) fills a real gap — this works especially well if you live near campus and can cook, or partner with someone who does. 

Start with a small WhatsApp order list for your block before expanding, and be upfront about your kitchen’s hygiene standards since that’s the first thing customers will ask about.

11. Dropshipping Business

Dropshipping lets you run an online store — usually on Shopify where a supplier ships products directly to your customer, so you never hold stock. It’s worth being honest about one thing here: while there’s no inventory cost, most dropshipping stores don’t get real traffic without some ad spend, so “zero investment” mostly holds if you’re driving traffic organically through social media rather than paid ads, at least until the store proves itself.

12. Photography

If you already have a decent phone camera or access to a friend’s DSLR, campus fests, birthdays, and small local events are a steady source of paid photography work that needs no equipment purchase to start. Portfolio-building is the real first step — shoot a few events for free or cheap, post the best shots, and let those bookings lead to paid ones.

13. Audiobooks and Dubbing

If you have a clear speaking voice, platforms built for Indian-language audio content — Kuku FM and Pocket FM among them — regularly look for narrators and voice talent, and Audible’s ACX opens up English narration and dubbing work globally. This is genuinely zero-cost to start — a quiet room and a phone mic are enough for a demo reel.

You can use this skill to upload on Youtube without using copyright content and earn when thousands of people listen to it.

Read More👉 Best Student Loans for College Students

14. Creating AI Agents

This is the newest idea on the list and the one moving fastest. No-code automation tools — Zapier, Make, and n8n among them — let you build simple AI agents and chatbots (a WhatsApp order-taking bot for a local shop, an FAQ agent for a small business website) without writing production code. 

Local businesses that can’t afford a developer are a realistic first client base, and Fiverr/Upwork already have a growing “build me an AI agent” category. Because this space is changing month to month, treat any specific tool or pricing claim here as a starting point to verify, not a fixed fact.

15. Tour Coach

If you know your city well — the food streets, the history, the spots tourists never find on Google — you can run informal walking tours for other students, exchange-programme visitors, or tourists passing through. 

This starts as pure word-of-mouth and a shared Google Form for bookings; no licence or investment is needed for small informal group walks, though it’s worth checking your city’s local rules if you plan to scale it into a formal, paid business.

How to Choose One Business Option for Yourself

With fifteen options on the table, picking one comes down to three honest questions:

What do you already do without being asked? If you’re the one editing everyone’s assignment for grammar, that’s writing or content work. If you’re the one people ask to fix their laptop, that’s repair. The idea that fits fastest is usually the one closest to a habit you already have.

How many hours can you actually spare each week? Tutoring and freelance writing can run for 3–4 hours weekly. A tiffin service or reselling business needs closer to daily attention. Be honest about your semester’s course load before committing to something time-heavy.

Does your campus or city actually have demand for it? A tiffin service needs hungry hostel students nearby. A tour-coach idea needs a city with something to show. Match the idea to where you actually are, not to what worked for someone in a different city’s Instagram reel.

If two ideas still feel equally right, run both for two weeks each during a low-pressure period and let actual results — not your gut — make the call.

Read More 👉 Best Noise-Cancelling Headphones for Online Classes and Mock Tests 

Conclusion

You don’t need capital to start earning as a student — you need one skill, a few free hours a week, and the willingness to start small enough that a bad exam week doesn’t sink the whole thing. Pick the one idea from this list of “Business Ideas for students” that matches something you’re already good at, give it thirty days of consistent effort before judging it, and treat the first version as a test rather than a final plan. 

Most student businesses that actually last didn’t start as a five-year vision — they started as someone testing whether people would pay for something they were already doing for free.
Leave a Comment

Your email address will not be published. Required fields are marked *

How to Apply for an Education Loan Online

Education Loan

Your admission letter has a deadline attached to it, and so does the deposit your college wants. That’s usually the exact moment families realise they need an education loan and have no idea where to start — which bank, which portal, how long it takes, or whether the college fee will actually reach the institute on time. Applying for an Education Loan online in India isn’t hard once you know the sequence, but doing it in the wrong order costs weeks you don’t have.

Here’s the sequence that actually works, plus the numbers most guides skip.

Start On The Vidya Lakshmi Portal, Not a Random Bank Branch

The government’s PM-Vidyalakshmi portal (pmvidyalaxmi.co.in) exists precisely to stop students from filling out ten different forms at ten different bank branches. It currently lists 86 education loan schemes from 38 banks, and lets you fill one Common Education Loan Application Form (CELAF) and send it to up to three lenders at once. Each bank evaluates it independently and responds through your dashboard — you compare offers side by side instead of chasing branch managers.

You can still apply directly through a bank’s own app (SBI YONO, HDFC’s portal, or an NBFC like Credila or Avanse), and for study-abroad loans that’s often faster. But if you’re not sure which lender fits your profile, the portal is the better starting point because it also flags which subsidy schemes you qualify for — more on that below.

The Standard Step-By-Step Process on the Portal

Register on The Portal

with your mobile number, email, and Aadhaar. You’ll set up a student login and can save your progress partway.

Fill The CELAF  

Complete the Common Education Loan Application Form — personal and academic bio-data, course and institution details, total cost of education, and collateral info if applicable. One form covers every bank you apply to. 

Search and Shortlist Schemes. 

The portal shows which banks match your course, institute ranking, and loan amount, along with their listed interest rates.

Apply to up to 3 banks

Submit the same CELAF to up to three participating banks simultaneously. Each bank evaluates independently and responds through the portal.

Upload documents 

KYC, admission letter, fee structure/cost estimate, income proof, academic records, and collateral documents (if the loan amount requires security) go up here. Track status in real time — sanctioned, under review, or query raised.

Respond to Bank Queries 

Follow-up document requests, or interview calls show up directly on the dashboard if they ask for additional paperwork. Approval typically runs 15–30 working days depending on profile and paperwork. 

Sanction and Disbursement 

Loans are usually released in tranches per academic year — the first installment around admission time, the rest against fee receipts and progress certificates. Most banks send the amount as a demand draft or transfer straight to the institute, not to you.

Public sector banks typically take 15–25 days to sanction; NBFCs like Credila can do it in 7–14 days, which matters if your visa or admission deadline is tight.

Important Documents You Must Have For Education Loan

  • Admission letter with fee structure, 
  • 10th/12th mark sheets and entrance scorecard (JEE, NEET, CAT, GRE, whatever applies), 
  • Aadhaar and PAN, 
  • Co-applicant’s income proof (last two years’ ITR and Form 16, or salary slips), 
  • Last six months’ bank statements, 
  • Passport-size photos, 
  • Collateral documents if your loan amount needs security. 

Missing or blurry documents are the single biggest reason applications sit in “query raised” status for weeks.

Read More 👉 Business Ideas for Students With Zero Investment — Easy Startup Guide

How Much You Have To Repay in Education Loan Online

Headline rates change with every RBI repo revision, so treat these as indicative starting points as of mid-2026, not fixed numbers — confirm the current rate directly with the lender before you sign anything.

LenderIndicative rate (p.a.)Notes
SBI Scholar Loan (IIT/IIM/ISB/select institutes)6.90% – 7.65%Lowest rates available, but restricted to a specific institute list
SBI Global Ed-Vantage (study abroad)From ~9.15%Flat ₹10,000 processing fee, needs 15% margin money above ₹4 lakh
PNB8.55% – 11.95%Up to ₹20 lakh without collateral for eligible courses
Canara Bank9.25% – 11.95%Strong presence in South India
HDFC Bank9.50% – 13.50%Faster processing than most PSU banks
Axis Bank9.50% – 13.50%Similar positioning to HDFC
ICICI Bank10.50% – 13.50%Higher end of private-bank rates
HDFC Credila (NBFC)~9.75% secured / ~10.25%+ unsecured100% financing possible, sanction in days, but processing fee is 1–1.25% + GST
Avanse / Propelld (NBFC)~10% – 13.5%Collateral-free options up to ₹60–75 lakh, merit-based pricing

The gap between a PSU bank’s lowest rate and an NBFC’s unsecured rate can run 3–4 percentage points. On a ₹15 lakh loan over 10 years, that difference alone adds up to several lakh rupees in extra interest — it’s worth the extra week of paperwork to get a PSU sanction if your timeline allows it.

The Subsidy Most Students Never Check For

Two separate government schemes can cut your effective rate, and they’re easy to confuse:

PM-Vidyalakshmi interest subvention (launched November 2024) gives a 3% interest subvention on loans up to ₹10 lakh, during the study period and moratorium, if your family income is up to ₹8 lakh a year. It only applies if you’re admitted to a Quality Higher Education Institution — over 860 of them qualify, including all IITs, NITs, and IIMs, plus state institutions ranked 101–200 in the NIRF list. There’s also a 75% government credit guarantee on loans up to ₹7.5 lakh, which is why some banks will sanction you without asking for collateral or a guarantor.

Central Sector Interest Subsidy (CSIS) is the older scheme — it covers the full interest during moratorium, but only for families earning up to ₹4.5 lakh a year and only at a separate, narrower list of premier institutions. You can’t claim both on the same loan, so check which one your institute and income bracket actually qualify for before assuming you get nothing.

Apply for whichever subvention you’re eligible for through the same portal — it isn’t automatic.

What Happens Once You Start Your Repayment

Once repayment starts, the interest you pay (not the principal) is fully deductible under Section 80E of the Income Tax Act — no upper limit on the amount. The deduction runs for 8 years from when you start repaying, or until the interest is fully paid off, whichever comes first. 

It applies to loans taken for your own, your spouse’s, or your children’s higher education, but only from a bank or a notified financial institution — a loan from a relative doesn’t qualify.

Read More 👉 How to Start a Mineral Water Business: Complete Guide

How You Can Save Real Money in Education Loan

  • Girl students get an automatic 0.5% rate concession at most public sector banks — ask for it explicitly if it isn’t applied.
  • Pay simple interest during the moratorium if you can manage it, even partially. Left unpaid, it often compounds once repayment begins, and on a ₹10 lakh loan that gap can run into a couple of lakh rupees by the time you graduate.
  • Compare processing fees, not just the headline rate. SBI charges a flat ₹10,000; NBFCs typically charge 1–1.75% of the loan plus GST, which is a meaningful amount on a ₹50 lakh loan.
  • Check margin money requirements. PSU banks generally need you to fund 15% of the cost yourself for loans above ₹4 lakh (domestic) or above a certain threshold for study abroad; several NBFCs offer 100% financing instead.
  • Ask about prepayment penalties before signing with an NBFC — some charge 1–3% if you close the loan early, which matters if your income grows faster than expected.

What If Your Study Loan Application Gets Stuck?

Most delays trace back to one of four things: 

Documents uploaded in the wrong format or half-legible, applying to a bank whose collateral rules don’t match the loan amount requested, assuming you qualify for a subsidy without checking the institute list first, and accepting the first offer instead of comparing at least two or three sanctioned terms side by side.

Register on the Vidya Lakshmi portal, shortlist one PSU bank and one NBFC so you have both a low-rate option and a fast-sanction backup, check which subsidy scheme your institute and income actually qualify for, and get your documents scanned before you start the form — not after a bank asks for them.

Conclusion

Understanding How to Apply for an Education Loan Online lets you avoid mistakes, get your documents ready at time, and not get your application stuck. If you want to pursue your education but can’t afford it, the study loan will help you achieve your dreams. Remember to check the bank’s interest and calculate the cost you have to pay later.

Leave a Comment

Your email address will not be published. Required fields are marked *

UP SuperTET Vacancy Notification 2026: Check Out Details, Dates, & Eligibility

SuperTET

If you’ve been searching continuously on Google for “UP SuperTET 2026 Notification Out, you are not alone because many future teachers are googling it but don’t panic. You are not late, because the official notification has not been released yet. The vacancy numbers are a guess if you see anywhere.  

When Will The UP SuperTET Notification Get Released?

UPBEB is going to publish the SuperTET 2026 notification soon and it carries the exam date, required documents, eligibility, and exam pattern information for the candidates. The best way of starting the process is to read that notification carefully once it is released before going to fill the form for UP SuperTET 2026. 

It’ll land after the UPTET result is out, so most of the candidates get eligible for the SuperTET so there should be a larger number of vacancies. But that’s an educated guess about timing, not a commitment from the The Uttar Pradesh Basic Education Board. 

Where You Can Find The SuperTET Updates? 

Skip the YouTube shorts and forward-heavy WhatsApp groups. The two sources worth bookmarking are:

Vacancy For UP SuperTET Exam 2026

From the past cycle and current teacher-shortage data, it is precisely reasonable that UP SuperTET 2026 Vacancy lies around 69,000, 85,000. But these numbers aren’t shared by the officials so treat them as a closer guess. 

The 2019 SuperTET drive filled around 69,000 posts so it became the usual provisional around number. Until UPBEB publishes district-wise and category-wise vacancy breakdowns in the actual notification.

SuperTET Salary and Eligibility 

Vacancy and dates can change year by year but 80% of the stuff is the same each year. SuperTET eligibility, salary, exam pattern are not going to change, even if it does, only slight change can happen. 

ParameterDetails
PostAssistant Teacher – Primary (Classes 1–5) and Upper Primary (Classes 6–8)
Pay Scale₹35,400 – ₹1,12,400 (Level 6, 7th Pay Commission)
EligibilityValid CTET or UPTET:- Paper I for Primary (Classes 1–5)- Paper II for Upper Primary (Classes 6–8)Plus relevant qualifying degree and/or B.Ed as per recruitment rules
Exam PatternObjective-type test, 150 marks, covering:- Language proficiency- Pedagogy (teaching methodology)- General Knowledge- Subject-specific content knowledge

Qualifying Numbers are easily let you pass by acquiring 40% (60/150) if you are General category candidate and 33% (49.5/150) for the candidates who belong to SC/ST/OBC-NCL/PwD but they are not a scoring score to win this battle among thousands candidates. 

Actual merit cutoff: if you actually want to get selected then score from 90 to 130+ out of 150 to hold out your position. These are the actual merit numbers, it also depends up on your category and how many seats are open. 

That gap between “qualifying score” and “actual selection score” trips people up every cycle. SuperTET isn’t a pass/fail eligibility test — it’s a straight competitive recruitment exam. Scoring the minimum gets you nowhere near a job.

UPSSSC PET Exam Date 2026 Out

How To Prepare Yourself For The Exam

  1. Don’t wait to start preparing. The syllabus and pattern are already finalized by UP authorities, which is usually a sign the recruitment machinery is moving even if the notification isn’t out yet.
  2. Keep your CTET/UPTET certificate and documents ready. Once the form opens, the window is typically short — 20 to 30 days and document scrambling under deadline pressure is a self-inflicted wound.
  3. Ignore vacancy-number debates on social media. They change nothing about your prep and mostly exist to farm engagement.
  4. Set a check-in habit, not a refresh habit. Checking the official website once a day is enough. Constant refreshing just adds stress without adding information.

Conclusion 

Start focusing on the syllabus, pattern, expected post structure before UP SuperTET 2026 Notification Out because it’s released, you won’t get enough time to prepare after that. There’s no confirmed vacancy count but there’s a guessing number, the competition will be higher. 

Prepare like the exam is close, because structurally it looks like it is, but don’t let unverified numbers shape your expectations or your plans.

Always cross-check every information on the official website of UP Super TET 2026 Notification Out before acting on any detail published by educational sites.

Leave a Comment

Your email address will not be published. Required fields are marked *

Scroll to Top