Collateral vs No Collateral Loan Amount Where Collateral Starts Making Financial Sense

Collateral vs No Collateral Loan

Ask most people whether a secured loan beats an unsecured one, and they’ll say yes without blinking — lower interest rate, obviously better. That’s the assumption. It’s also where the math quietly falls apart, because a lower rate on paper doesn’t always mean a lower cost in your pocket. Don’t get confused about Collateral vs No Collateral Loan, understand where it matters.

Whether collateral actually saves you money depends on how much you’re borrowing, and more specifically, on what kind of asset you’re pledging to get that lower rate.

This isn’t a “secured is always cheaper” point. It’s about the exact moment moves depending on the collateral where the interest-rate discount stops being eaten alive by fees, valuation costs, and paperwork.

What Changes When You Add Collateral to a Loan

A collateral loan amount decision comes down to three things shifting at once, not just the rate.

The interest rate drops, because the lender’s risk drops. If you default, they recover the loan by selling or auctioning the pledged asset. As of late 2026, unsecured personal loans in India typically run 11–18% per year for a reasonably qualified borrower, and unsecured business loans usually start closer to 16%. Gold loans from banks price between roughly 8.5% and 12%, and loans against property (LAP) generally fall between 8.5% and 14%, though NBFC gold loans for weaker profiles can climb well past 20%.

Fixed costs show up that don’t exist on an unsecured loan. Asset valuation, legal verification, mortgage registration, sometimes insurance on the pledged asset. These are flat charges — they don’t scale down for a small loan the way percentage-based interest does.

Your money moves slower, and your asset stops being liquid. A personal loan can land in your account same-day. A property-backed loan needs valuation, title checks, and registration, which can take one to three weeks. During that time, and for the life of the loan, that asset is off the table if you need to sell it, gift it, or use it as collateral again elsewhere.

That third point is the one people underweight, and it matters more as the loan amount grows, not less which is part of why there’s no single “collateral is worth it above this number” answer.

The Real Threshold Depends on Which Asset You’re Pledging

The breakeven point isn’t one number in Collateral vs No Collateral Loan. It’s a different number for every type of collateral, because the fixed costs attached to each one are wildly different.

Gold or fixed-deposit collateral has almost no fixed-cost floor. A gold loan can be sanctioned in under an hour, valuation is done on the spot, and processing fees run 0.25–1% of the loan amount — often just a few hundred rupees on a small ticket. Because there’s barely any fixed cost to clear, a gold loan can make financial sense on amounts as small as ₹50,000–₹1 lakh. The rate gap versus an unsecured loan (often 4–8 percentage points) starts saving you money almost immediately.

Property as collateral (LAP) is the opposite case. Valuation fees, legal verification, and mortgage registration or stamp duty typically add up to somewhere between ₹15,000 and ₹30,000, depending on the state and lender — and that’s before you factor in the two-to-three-week processing time. On a small loan, that fixed cost can wipe out most or all of the interest savings. LAP generally only starts making financial sense somewhere in the ₹5–8 lakh range, and it becomes clearly worthwhile above ₹10 lakh, where the fixed costs shrink to a rounding error against the total interest saved.

Vehicle or equipment-backed business loans sit in between — moderate valuation costs, faster processing than property, and a breakeven point that usually lands somewhere in the ₹2–4 lakh range.

A Quick Numbers Comparison 

Here’s a simplified comparison over a 3-year tenure, using a representative unsecured rate of 15–16% against a representative secured rate of 10% (gold loan) or 10% (LAP), before fixed costs:

Loan AmountInterest Paid Unsecured (~16%)Interest Paid Secured (~10%)Raw Interest SavedTypical LAP Fixed CostsNet Saving After Fixed Costs
₹1,00,000~₹25,000~₹16,000~₹9,000N/A (use gold loan, not LAP)Gold loan: still net positive
₹2,00,000~₹53,000~₹32,000~₹21,000~₹20,000Roughly breakeven
₹5,00,000~₹1,33,000~₹81,000~₹52,000~₹20,000~₹32,000 saved
₹15,00,000~₹3,98,000~₹2,42,000~₹1,56,000~₹25,000~₹1,31,000 saved

Note: these are illustrative figures based on representative rate bands, reducing-balance EMI math, and typical fee ranges reported by Indian lenders as of August 2026. 

The pattern holds regardless of the exact numbers: 

On a ₹1 lakh loan, a gold loan wins easily because there’s almost no fixed cost standing between you and the rate discount. On a ₹2 lakh loan taken as a property-backed loan specifically, the fixed costs and the interest savings roughly cancel out — which is exactly why lenders rarely push LAP that small in the first place. By ₹5 lakh and above, the fixed cost stops mattering and the rate gap does all the work.

When Collateral Still Doesn’t Make Sense, Even Above the Threshold

Crossing the breakeven number doesn’t automatically make collateral the right call. A few situations flip the decision back toward unsecured, even at a large loan amount and you started searching for  Collateral vs No Collateral Loan.

  • You need the money in days, not weeks. An unsecured personal loan can disburse within 24–48 hours. A property loan’s valuation and registration process can eat two to three weeks — a real cost if the need is urgent (medical, a time-bound business opportunity, an admission deadline).
  • The asset has a use you’d lose access to. Gold jewelry you might need to sell or gift, or a property you’re planning to sell within the loan tenure, becomes harder to move once it’s pledged. Foreclosure and part-release processes add time and fees of their own.
  • Your income is genuinely unstable. Secured loans still get called in on default — the lender auctions the asset. If repayment is uncertain, adding “losing the collateral” on top of “damaged credit score” is a worse outcome than an unsecured default alone, all else equal.
  • The rate gap has shrunk. RBI rate cuts through 2025 and 2026 have compressed the spread between top-tier unsecured personal loans (some starting near 10%) and secured options in certain cases. Always compare Collateral vs No Collateral Loan live quotes — a hypothetical rate gap on a post isn’t the rate you’ll actually be offered.

Which One Should You Pick Between Collateral vs No Collateral Loan?

Match the collateral type to the loan size, not the other way round:

  • Borrowing under ₹2 lakh and you own gold or have a fixed deposit sitting idle? Pledge it — the fixed-cost floor is low enough that it almost always wins over an unsecured loan.
  • Borrowing ₹2–5 lakh? Run the actual numbers from at least two lenders before deciding. This is the genuine grey zone where fees can cancel out the rate advantage.
  • Borrowing ₹5 lakh or more and you have a property or a high-value asset to pledge? Collateral almost always wins on cost, provided you can tolerate the slower disbursal and the asset being locked up for the tenure.
  • Need the money within a week, regardless of amount? Unsecured is usually the only realistic option, and the speed premium is worth paying for.

The rate on the sanction letter is only half the decision. The other half is whether your loan amount is big enough to make the fixed costs of pledging that asset disappear into the background — and that number changes depending on what you’re pledging, not just how much you’re borrowing.

Read More 👉 Your Credit Score Ignores 90% of Your Financial Life — What Your First Credit Card Changes 

Conclusion

Collateral doesn’t automatically make a loan cheaper if you understand at what point it financially makes sense then you won’t get confused ever. The loan amount, the asset you pledge, and the rate difference all have to work in your favour

Which kind of loan you are seeking is also a matter, Gold or FD-backed loans can make sense even at smaller amounts because their upfront costs are low, while other higher loans such as property-backed loans usually need a much larger ticket before the interest savings outweigh valuation, legal, and registration costs.

Collateral vs No Collateral Loan is not a big confusion, there is no universal ₹5 lakh or ₹10 lakh cutoff where collateral suddenly becomes worth it. So you must understand where your interest savings finally outweigh the real cost and inconvenience of pledging the asset. 
Leave a Comment

Your email address will not be published. Required fields are marked *

UP Anganwadi Bharti 2026 — District-Wise Vacancies & Recruitment Details

UP Anganwadi Bharti 2026

UP Anganwadi Bharti 2026 recruitment is live and you can apply if the application portal is still live in your district. There’s no one deadline for the recruitment drive because it has a lot of separate district-level drives. It offers various posts such as Karyakatri and Sahayika, so these are open for females only.

First, understand the structure, eligibility, and selection process for UP Anganwadi Bharti then apply with all the required documents.

ParameterDetails
Recruitment NameUP Anganwadi Bharti 2026 (ICDS, Uttar Pradesh) 
Conducting AuthorityDistrict Programme Officer (DPO), Bal Vikas Seva evam Pushtahar Vibhag, UP 
Department / SchemeIntegrated Child Development Services (ICDS), Women & Child Development, UP 
Posts OfferedAnganwadi Worker (Karyakartri), Mini Worker, Anganwadi Helper / Sahayika 
Total Vacancies (Indicative)~60,000–61,600+ posts 
Eligibility Only female candidates, 10th / 12th pass
Residency ConditionCandidate must be resident of the same village/ward of the Anganwadi centre for which she applies
Application FeeNo fee for any category (General/OBC/EWS/SC/ST) 
Notification & Application WindowMain notification from Nov 2025; applications open/close district-wise through early–mid 2026 
Salary (Indicative)Around ₹5,500 – ₹12,000 per month 
Official WebsiteClick Here

Structure of UP Anganwadi Bharti 2026 — District by District

The notification is out from each district for the recruitment under the state government which directed the Department of Women and Child Development, to fill vacant Anganwadi Karyakatri (Worker) and Anganwadi Sahayika (Helper) posts across Uttar Pradesh. Instead of one recruitment drive, each District Programme Officer releases and manages notification and recruitment for their district at different times.

DistrictPostsLast date to apply
Jhansi223 (across 9 CDPOs)7 /September /2026
Maharajganj3051 /September /2026
Chitrakoot92 (23 Karyakatri + 69 Sahayika)5 /September /2026
HamirpurActive16/September/ 2026
BalrampurActive23 /September /2026
Amroha (J.P. Nagar)105 (across 7 projects)24 /September /2026

Earlier in the year, Bagpat and Kannauj ran their own window for 760 combined posts, applying from 25 June to 16 July 2026 — that cycle is closed, and candidates there are now waiting on the merit list.

Who Can Apply For UP Anganwadi Post

A few conditions hold across nearly every district notification:

  • Only female candidates are eligible — there’s no male category in this recruitment. 
  • Female candidates should be between 18 and 45 years, calculated as on 1 July 2025. Relaxation given only reserved category.
  • Anganwadi Karyakatri posts sometimes require an Intermediate marksheet, depending on the district rules. 
  • Helper (Sahayika) posts have historically carried a lower bar in some districts, occasionally as low as 8th pass.

The condition that trips up the most applicants isn’t age or education — it’s domicile. You can’t apply to whichever district has the most vacancies. Each post is tied to a specific ward (in urban areas) or gram/nyaya panchayat (in rural areas), and you must be a permanent resident of that exact unit. A vacancy list in Jhansi is not open to a resident of Kanpur, even within the same state.

Read More 👉 UP SuperTET Vacancy Notification 2026: Check Out Details, Dates, & Eligibility

Vacancies Numbers Are Huge

The total vacancies are more than 60000 across the state. Open your district’s latest 2026 notification PDF to check the vacancy number.

DistrictPost TypeVacanciesKey Detail
FatehpurWorker + Helper389150 Worker + 239 Helper (Aug–Sept 2026)
BandaWorker122Last date 22 Sept 2026
HamirpurWorker80Last date 16 Sept 2026
UnnaoWorker336Last date 11 Aug 2026
GhaziabadHelper341Last date 07 Aug 2026
JhansiWorker (Karyakatri)223Across 9 projects; last date 07 Sept 2026
Kanpur NagarHelper (Sahayika)307Across 12 projects; last date 05 Sept 2026
KushinagarWorker245Project-wise split available
KushinagarHelper (Sahayika)214Separate Helper notification
MaharajganjWorker + Helper305164 Worker + 141 Helper
SonbhadraWorker201Project-wise vacancy table available
MuzaffarnagarWorker146Anganwadi Worker posts only
GhazipurHelper1,352Among larger Helper batches
BulandshahrWorker + Helper678Combined posts
BagpatHelper374Helper-only batch
AzamgarhHelper265Helper-only batch

Selection Process & Application Fee

There’s no written test and, in the vast majority of district notifications reviewed so far, no interview either. Selection is by merit list, built from your marks in 10th, 12th, and graduation, all being equal. There’s no application fee for any category, including SC, ST, PwBD, and general female candidates — this recruitment is free to apply for, full stop.

Salary Of UP Anganwadi Posts

A ₹10,000/month for Anganwadi Worker, ₹7,500 for Mini Worker, and ₹4,500 for Helper as honorarium (not salary — these are Anganwadi posts, not salaried government service, and the distinction affects things like PF and pension eligibility). 

Getting Your Application In Before Your Window Closes

Applications go through upanganwadibharti.in 

On the homepage, you’ll find a running list of “active” district notifications with their upload and closing dates; this list changes weekly as new districts come online and others close.

Fill your details correctly in the form and submit with all the necessary documents attached. There is no application fee, so apply early and correctly.

The real trap here is timing, not eligibility. Most district windows stay open for only two to four weeks from the upload date — Hamirpur’s notification, for example, went up on 27 August and closes 16 September, an 18-day window. 

Bookmark the official portal itself, and search for your specific ward or gram panchayat, not just your district name; that’s the actual unit your eligibility is judged against.

Documents Required To Apply

Gather your documents first before your district application portal goes live. The necessary documents are listed in the notification PDF but you can also catch it here:

  • Your education proof – any 10th, 12th, and graduation marksheets, 
  • Domicile certificate for resident confirmation, 
  • Caste certificate (if you belong to reserved category), 
  • Aadhaar/ PAN Card, and 
  • A recent passport size photograph 
  • Signature on the blank page

Get ready with all these documents before your ward’s notification even drops.

Read More 👉 Planning MBBS or Master’s Abroad? Country-Wise Costs, Loan Limits and Lenders

Conclusion

UP Anganwadi Bharti 2026 notification is out but recruitment is active in some districts and closed in few districts. If the recruitment is active in your region then apply now before it gets closed. The vacancy numbers are huge, more than 60,000 posts are vacant and these seats are only open for females. 

But you must be the resident of that village to apply, and the documents must be prepared including your adhaar, high school marksheet, domicile certificate etc. You can apply for free but check the notification before you apply for the Karyakatri and Sahayika position.

Leave a Comment

Your email address will not be published. Required fields are marked *

Best Laptops for Coding and Programming: Top Picks for Every Budget

Best Laptops for Coding and Programming

If you are in the last semester of B.Tech or you got the first internship, and it requires VS Code, three Docker containers, Android Studio’s emulator, and eighteen Chrome tabs open at once on a laptop your parents bought you in 2021 with 4GB of RAM. That’s the moment most Indian coders realise their machine is the bottleneck, not their skills. And they started looking for the Best Laptops for Coding and Programming.

A gaming laptop’s RTX 4070 is dead weight if you’re building REST APIs all day, and a fanless ultrabook will choke the moment you spin up a local Postgres instance alongside two VMs. What actually matters for most development work — web, app, backend, data — is RAM headroom, a fast NVMe SSD, sustained CPU performance, and a keyboard you can survive eight hours on. A dedicated GPU only earns its price tag if you’re doing CUDA-based ML work, training models locally, or running the Android Studio emulator constantly.

Make sure that your laptop has 16GB RAM, not 8GB — Chrome alone with dev tools open can eat 4-6GB. Picking 24-32GB when you’re running Docker and VMs together. If there are SDKs, node_modules folders, and Android SDK files that take up to 50 GB itself then pick 512GB NVMe SSD. The best CPUs of current-gen are Intel Core Ultra 5, AMD Ryzen 5/7, or Apple M-series and these are the best options for IDEs and compilers. Coders don’t need a higher-end chip unless they’re compiling large codebases consistently. 

You must understand that laptop prices in India move fast, sometimes 8-10% within a few weeks around sale events. Every price below is what these models were listed at in the first half of August 2026 on Flipkart, Amazon, or the brand’s own India store — treat them as a strong reference point, not gospel, and check the live price before you check out.

Common Mistakes Indian Buyers Make When Choosing a Coding Laptop

The “i5 always beats i3” assumption costs people money every single sale season. Code compilation goes smoother in a 13th Gen Core i3 with 16GB RAM laptop than 11th Gen i5 with 8GB, because for coding, RAM headroom and SSD speed is more important than processor tag on it. Check the generation and RAM on it. 

The second mistake is buying a gaming laptop “just in case” you need the GPU later. Unless you already know you’re headed into machine learning, computer vision, or heavy Android emulator work, that RTX card is dead weight adding to the price, the heat, and the battery drain — money better spent on RAM or storage.

The third mistake which most ‘students and I’ made was to pick a laptop with a good processor and ignore the screen size and keyboard which is necessary for coding. They bothered a lot when you sit for 8 hours with it and fix errors. If you are shopping online then check practical reviews or sit with it on a story.

Read More 👉 Top Lightweight Student Laptops to Buy in 2026

The 11 Best Laptops for Coding in India 

1. Apple MacBook Air 13 (M4, 16GB/256GB)

This is the finest and most expensive laptop but offers excellent performance with Apple M4 chip, 16GB unified memory, 256GB SSD, that help running programs smoothly. It doesn’t get shut down when you are working in a campus because 18 hours of battery life makes it possible with no fan noise.

With price around ₹89,990-97,900, macOS delivers a Unix-based environment — a native terminal, Homebrew, and zero WSL workarounds. So there is no need for WSL during your production, you can just focus on your development tools. However, if you are installing Xcode, Docker Desktop, and multiple projects then a 256GB SSD is less than you need for your project. The files are big and you need more space so pick 512GB version if your budget allows.

Students enrolled in a Full-stack and iOS development programs that require macOS and not Windows can select this laptop for their best use.

2. ASUS Vivobook S16 OLED (Core Ultra 5 225H, 16GB/512GB) 

ASUS offers not just a laptop but a digital book with 16-inch OLED display for ₹85,990. With Intel Core Ultra 5 225H processor, 16GB LPDDR5X, 512GB SSD, of space it runs every software and program very smoothly. You can use this machine for multi-tasking and production on a genuinely large, colour-accurate screen that helps in working in a single laptop with split-pane coding without an extra monitor on one side. 

You must be aware that OLED panels are more prone to burn-in with static IDE toolbars left on screen for hours so be careful with that. Most people recommend to dim the brightness or use auto-hide dock settings. Otherwise it’s the best machine for developers who want big screens on work or on campus without lugging a 17-inch brick.

3. ASUS Zenbook 14 OLED (Core Ultra 7 255H, 32GB/1TB) 

Raise the budget and buy ASUS Zenbook 14 OLED at ₹1,31,990. If you need to run large codebases and softwares like Docker, two VMs, and a browser with 20 tabs simultaneously then you need a system that is built on Intel Core Ultra 7 255H, 32GB LPDDR5X, 1TB SSD. Not any other laptop is worth at this price point than ASUS with 14-inch 3K OLED, Thunderbolt 4

There is no drawback than its premium price for a 14-inch laptop. But this is the best piece for Data Scientists and Backend Engineers doing heavy multitasking who are not planning to buy another laptop for the next four years.

4. Lenovo IdeaPad Slim 5 (Ryzen AI 5 330, 16GB/512GB)

If your budget allows, you can check out the Lenovo IdeaPad Slim 5 laptop specs. An AMD Ryzen AI 5 330 processor which gives excellent performance, 16GB RAM, 512GB SSD in  ₹97,890. Best for coders with 14-inch display, and an integrated NPU for on-device AI tasks. 

Its value is increasing day-by-day because AMD’s price-to-performance here beats most Intel equivalents at this exact price point. But the issue is RAM is soldered on some variants so carefully check the exact model and the upgradation system before you buy it. Either way this is the best laptop for developers who want better performance.

5. Lenovo ThinkPad E14 Gen 5 (13th Gen Core i5-1335U, 16GB/512GB) 

If your budget is low and you want a laptop on which you can easily run large codebases then this ₹74,990 Lenovo ThinkPad E14 Gen 5 is best for you. It built on Intel Core i5-1335U and offering space of 16GB RAM, 512GB SSD which makes it perfect for backend and enterprise developers. 

When you sit for hours on coding and typing then you realize ThinkPad keyboards with spill-resistant are amazing and 14-inch WUXGA IPS display for working on multiple softwares. But it won’t be good in integrated graphics and also plain IPS panels feel dated next to the OLED competition at this price.

6. HP OmniBook 3 (AMD Ryzen AI 300 series) 

HP OmniBook 3 is available at just ₹69,999 with features that any coder needs for their production. AMD Ryzen AI 300 processor with a 50 TOPS NPU which remarkably out-performs every task and other laptop at this price point. The big display of 14-inch and 15.6-inch, both are available with FHD display, HP True Vision camera. 

But the power that the display consumes is high, it tops out at 250 nits so this is not good for working outdoors where you can’t get a power source. Overall laptop performance is good enough for students and early-career developers who have less budget.

7. Dell Inspiron 15 3520 (12th Gen Core i5-1235U, 16GB/512GB) 

Intel Core i5-1235U (12th Gen) laptop is fantastic for web developers or early backend developers who want the nearest service center and have less budget. It comes with 16GB DDR4, 512GB SSD which is good for handling compilation with a big screen of 15.6-inch but 120Hz brightness of display is not good enough to see for 8 hours or outside. That doesn’t matter for coders because they mostly do coding inside and in-office so modern AI-focused processor at this competitive price is a good choice.

8. Acer Aspire Lite AL15-41 (Ryzen 5 5625U, 16GB/512GB) 

AMD Ryzen 5 5625U is good but the U series might get stuck during multi-tasking so it is good only for college students who started learning coding. Space is given for running IDE smoothly and compilation with 16GB DDR4, 512GB SSD but do not run any task simultaneously. The 15.6-inch FHD display and metal body is convenient for students to carry it for college.

One thing about the Acer Aspire Lite is good that they give a proper 16GB configuration, not 8GB at just ₹56,990. It is rare to find this kind of laptop which supports Docker and multiple IDE instances open without raising any issue.

9. Acer Aspire 3 A324-53 (13th Gen Core i3, 16GB/512GB) 

Acer Aspire 3 offers 13th Gen i3 with 16GB RAM, provides sufficient performance for coding and beats older i5 laptops in day-to-day development work. The newer processor matters more than the i5 badge because coding needs a system who handles new libraries and data. The tech evolves every year that’s why upgrades or new versions support more tasks and software easily than older models.

Specifications are Intel Core i3 13th Gen, 16GB RAM, 512GB SSD are given at ₹46,900 which is affordable for most of the students and new developers who need VS Code, Python, and Java to run smoothly. 15.6-inch FHD IPS is good for coding so it won’t affect on eyes but there is no discrete graphics and a plain plastic chassis, it’s designed for work rather than premium looks. 

10. Lenovo LOQ 15ARP9 (Ryzen 7 7435H, 24GB RAM, RTX 4060 8GB)

The RTX 4060 is a great pick for developers who are working for CUDA-based machine learning, local AI models, andAndroid Studio emulator running full-speed with hardware acceleration. As ML engineers, Android developers who lean on the emulator daily need AMD Ryzen 7 7435H, 24GB RAM, 512GB SSD, NVIDIA RTX 4060 8GB, all of it.

Anyone doing local AI/GPU work can afford it in ₹1,03,290. But it’s actually built for gaming purposes and battery life is shorter so it is difficult to work without sitting near a power source. 

11. HP OmniBook 5 (Snapdragon X Elite, 16GB/1TB) 

You can get a Qualcomm Snapdragon X Elite X1-26-100 processor, 16GB RAM, 1TB SSD for ₹87,990 from HP. don;t get confused because it uses an ARM-based processor so you can expect issues of compatibility while running some development tools. Its always-on connectivity, and Copilot+ PC support is amazing with excellent battery life that can easily last through a full workday. You can buy it if you work mostly in browser-based IDEs, lightweight scripting, or cloud-hosted dev environments but check your specific toolchain before buying.

MacBook Air M4 vs ASUS Vivobook S16 OLED: The Real Choice Most Buyers Face

Most people narrow this list down to “Mac or Windows,” so here’s the direct comparison:

MacBook Air M4 (16GB/256GB)ASUS Vivobook S16 OLED (16GB/512GB)
Price₹89,990-97,900₹85,990
Storage256GB (upgrade recommended)512GB
Battery lifeUp to 18 hoursRoughly 8-10 hours real-world
OS/toolingmacOS, native Unix terminalWindows 11, WSL2 for Linux tooling
Best trade-offBattery and build quality, less storageMore storage and screen real estate, shorter battery

And if your stack includes iOS, native Unix tools, or you’re often travelling without a charger, the MacBook Air wins. If you’re on Windows-only enterprise tools, need the extra storage right away, or want a larger screen for the same price, the Vivobook S16 is the superior purchase. 

Which One Should You Actually Buy?

If you are a first year budget student then Acer Aspire 3 A324-53 is the decent option. Its 16GB RAM and price under ₹47,000 make it more appropriate for coding than a costlier i5 laptop with just 8GB RAM. If you want better all-round performance and more potential to grow, the Acer Aspire Lite AL15-41 or Lenovo IdeaPad Slim 5 are decent choices for Docker and running multiple IDEs without breaking the bank at under ₹80,000. 

If you’re doing CUDA, local ML training, or heavy Android emulator work, skip everything else and get the Lenovo LOQ with the RTX 4060 — no other laptop here will keep up. And if you want a machine that will still feel fast in three years and don’t mind paying for it, it comes down to the MacBook Air M4 for Unix-native workflows or the ASUS Zenbook 14 OLED if you’re staying on Windows and want 32GB as standard.

A quick note on operating system, since it comes up in every comments section: Linux dual-boot is still viable on nearly every Windows laptop on this list if you’d rather skip WSL2 entirely, though ThinkPads and the Acer/Dell budget picks tend to have the smoothest driver support for that route. 

macOS gives you native Unix without the dual-boot hassle, but locks you out of any Windows-only enterprise software your future employer might require — worth checking if you’re already targeting a specific industry like banking or government-adjacent IT, where Windows is still often mandated.

Check current pricing on Flipkart, Amazon.in, Croma, or the brand’s official India store before buying — several of these models moved 8% or more in the past month alone, in both directions. And if a listing shows a price noticeably below everything here, treat it as a flag to double-check the seller and warranty terms rather than an automatic win.

Read More 👉 Best Student Laptops for School and University in 2026

Conclusion 

When you are searching for the Best Laptops for Coding and Programming, you are expecting one simple answer but it isn’t. The best one is the one which fits in your budget, works efficiently, and is durable to handle all your workload. So make a list of 2-3 laptops which come into your budget and work needs then compare their pricing and look for a special discount offer before buying it.

If you are buying online then check practical reviews and videos from people who have actually used it before and work on it so you can get an idea whether it is good for you or not.

Leave a Comment

Your email address will not be published. Required fields are marked *

Best Noise-Cancelling Headphones for Online Classes and Mock Tests 

Headphones

You’re 40 minutes into a 3-hour mock test, deep into the reasoning section, and someone two floors down starts drilling a wall. Or it’s your neighbor’s TV bleeding through during a live online class, right when the teacher explains the one concept you actually needed. With best Noise-Cancelling Headphones, it is possible to block the noise out the room, stays comfortable for hours, and doesn’t die halfway through a session. 

As that kind of interruption doesn’t just annoy you — it costs you marks and attention you can’t get back. The right pair of Noise-Cancelling Headphones for online classes and mock tests is meant for this. Not just any Headphones — most people don’t need studio-grade audio for a lecture or a test window. Here are best picks that actually do that, across different budgets.

Why ANC Matters More for Exams Than for Music

Active noise cancellation in short ANC, helps prevent outside noise with an inverse sound wave by using a microphone and it is so effective on low-frequency and steady sound like traffic, fans, washing machine, TV, and construction site but less effective random sharp noises like barking or door slamming.

For a 2-3 hour mock test, that steady cancellation is what keeps your focus from draining. For live classes, you also need a decent mic, since ANC alone won’t help your teacher hear you over a ceiling fan.

Best Noise-Cancelling Headphones for Online Classes and Mock Tests

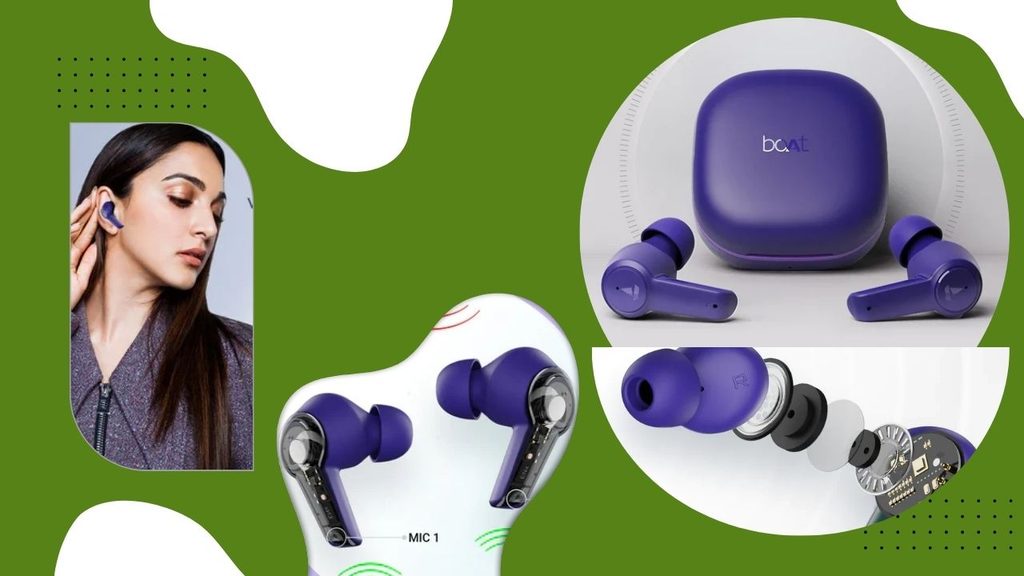
1. boAt Airdopes 413 ANC — ₹1,999

  • 25dB Active Noise Cancellation
  • ENx dual-mic technology for calls
  • ~20 hours total battery (earbuds + case)
  • In-ear TWS design


This is about as cheap as real ANC gets in India, and it holds up for what it is — steady background noise gets noticeably duller, which is the whole point during a test. The case battery isn’t huge, so charge it the night before a long mock test rather than assuming it’ll carry you through a full day.

Best for: the tightest possible budget where any real ANC beats none.

2. Boult Audio Omega — ₹2,499

  • Active Noise Cancellation + separate ENC chip for calls
  • 4 mics per stem, touch controls
  • ~32 hours total battery (8hr earbuds + 24hr case)
  • Dedicated Game Mode for low latency

The separate ENC chip is the standout here — it’s built for call clarity, which matters if your online classes involve a lot of back-and-forth with the teacher rather than passive listening. If you are also looking for gaming purposes, not just for mock test sessions then low-latency mode is an additional benefit in Boult Audio Omega.

Best for: students who have live classes and online courses to attend rather than recorded lectures.

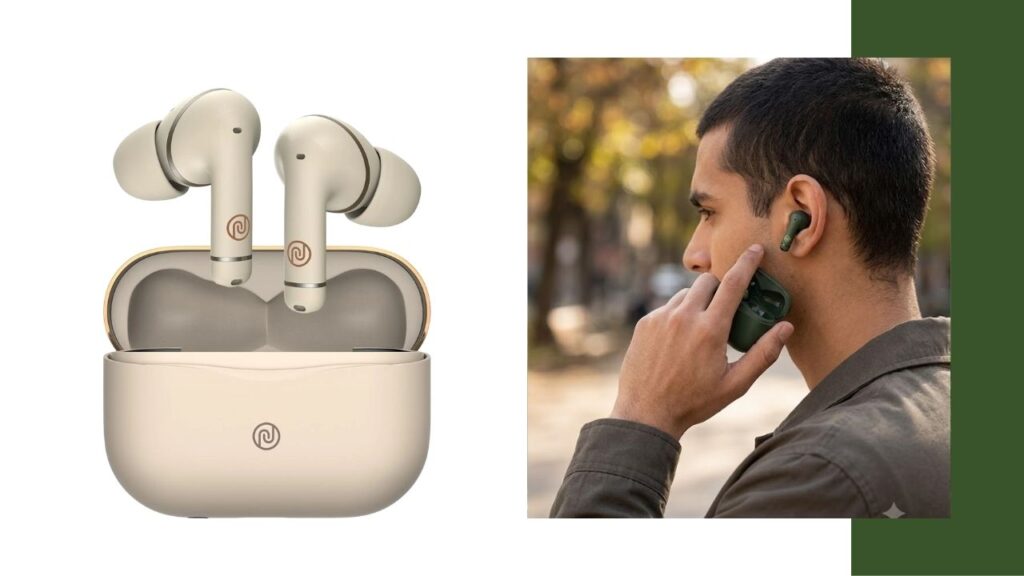
3. Noise Buds Solo — ₹2,999

  • Active Noise Cancellation with switchable Transparency mode
  • 10mm driver, touch controls for calls/music/voice assistant
  • ~36 hours total battery (7hr earbuds + case)
  • Interchangeable eartips for fit
Noise Buds Solo


The 36-hour total battery is the best in this budget tier, and the switchable Transparency mode is genuinely handy — flip it on for five minutes if someone’s calling you from another room, without pulling an earbud out mid-test. Interchangeable eartips also make a bigger difference than you might realize; a bad seal will ruin passive noise isolation even before ANC activates. 

Best for: the best all-round earbud pick under ₹3,000 if battery life is your priority.

Read More👉 Best Laptops for Coding and Programming: Top Picks for Every Budget

4. boAt Rockerz 450 ANC — ₹2,499–2,999

  • Hybrid ANC (up to 25dB reduction)
  • 20-hour battery life with ANC on
  • 40mm dynamic drivers, BEAST mode for low-latency audio
  • On-ear, foldable design
boAt Rockerz 450 ANC


This is the one to get if you just need to shut out a noisy house without spending a month’s pocket money. The ANC won’t touch a jackhammer, but it flattens fan noise, traffic hum, and a TV in the next room reasonably well. The ear cushions get a little warm after 2+ hours, and call clarity is average — fine for a mock test, less ideal if you’re live-unmuting often in class.

Best for: students on a tight budget who mainly need ANC for silent, focused test-taking.

5. Soundcore Q20i — ₹4,298

  • Hybrid ANC with Indoor/Outdoor/Transport modes
  • 40-hour battery life with ANC on
  • Soft protein-leather earcups
  • Wired mode available (3.5mm) when the battery does die
Soundcore Q20i


The battery life here is the real selling point — 40 hours means you could go through an entire mock-test series for a week without touching the charger. The Indoor mode specifically tunes the ANC for steady household noise rather than street sound, which is exactly the scenario most Indian students are dealing with. The bass is a bit boosted for critical listening, but for lectures and tests that’s irrelevant.

Best for: anyone who forgets to charge things — this Noise-Cancelling Headphones forgives you.

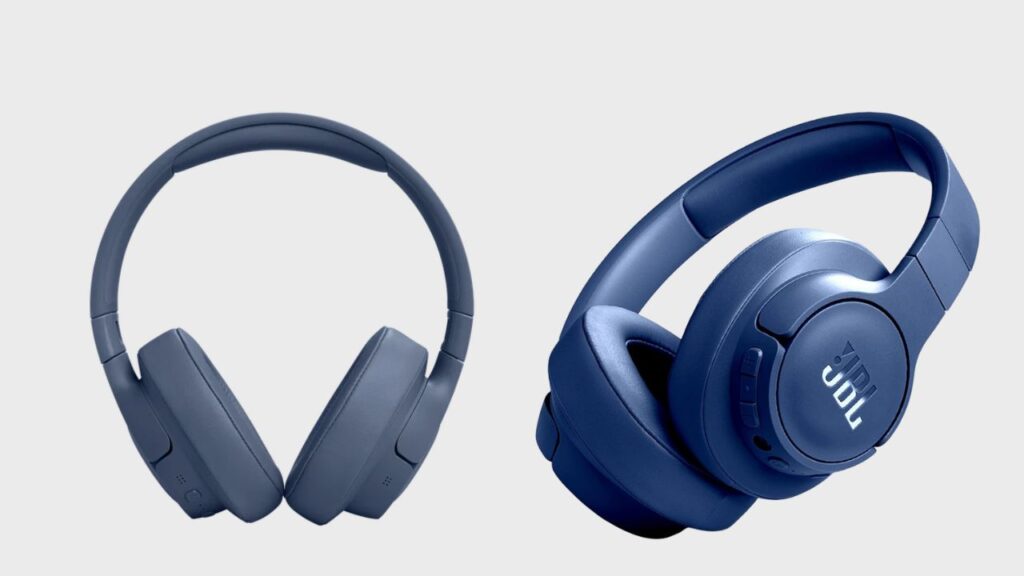
6. JBL Tune 770NC — ₹8,999–10,999

  • Adaptive ANC that responds very quickly to the surrounding noise automatically
  • 50-hour battery life (ANC off), around 44 hours with ANC on
  • Multipoint Bluetooth (connect to phone and laptop simultaneously)
  • 40mm drivers with JBL Signature Sound
JBL Tune 770NC

The multipoint pairing is genuinely useful if you attend classes on a laptop but take calls or check notifications on your phone — no fumbling with Bluetooth settings mid-lecture. Adaptive ANC means it automatically dials up cancellation when your maid starts sweeping and dials back down when it’s quiet, instead of a fixed on/off toggle. Bass is JBL’s usual signature — punchy, a little forward — which some people love and others find a bit much for spoken-word content.

Best for: students juggling both a laptop for classes and a phone for everything else.

7. Soundcore Space Q45 — ₹9,999 (often available around ₹8,500–9,000 on sale)

  • Adaptive ANC rated up to 98% noise reduction
  • 50-hour battery life with ANC on
  • LDAC support for Hi-Res audio over Bluetooth
  • Memory foam earcups, app-based custom EQ

This is the closest thing to flagship-level ANC without paying flagship prices. The 98% noise reduction figure holds up well against consistent background noise — the kind you get from a busy street or a joint family household during the day. Good memory foam cushions really do make a difference during a 3-hour test because your ears are not sore at the end. The app is actually useful, allowing you to choose a “study” EQ preset that cuts mid-bass boom, making spoken word clearer while you’re studying or attending lectures.

Best for: the best all-round pick if you want near-premium ANC without the premium price tag.

Read More👉 Best Student Loans for College Students

8. Sony WH-1000XM5 — ₹29,990

  • Industry-leading ANC with 8-microphone array and dual processors
  • 30-hour battery life with ANC on
  • Speak-to-Chat: automatically pauses audio when you start talking
  • Precise Voice Pickup Technology for clearer calls
Sony WH-1000XM5

If your budget stretches this far, the XM5 is close to overkill for a student use case — but that’s not a bad thing. A duo which makes you feel like you are sitting in an exam hall rather than your house. When you’re nervous your voice gets lower that people sitting behind the system couldn’t understand but Sony WH-1000XM5 gives an automatic Speak-to-Chat feature that pauses automatically if you say something out loud and passes your lower voice very smoothly. But this is too expensive for students but college students who strictly need can buy it on EMI

Best for: students who treat this as a long-term investment across school, coaching, and eventually work-from-home use.

Sony WH-1000XM5 vs Soundcore Space Q45

Sony WH-1000XM5Soundcore Space Q45
Price₹29,990₹9,999
ANC strengthBest-in-class, handles sudden noise tooExcellent against steady noise, weaker on sudden sharp sounds
Battery (ANC on)30 hours50 hours
Mic quality for classesBest on this listGood, not exceptional
Value for a student budgetLow — premium pricingHigh — near-flagship ANC at a third of the price

If money weren’t a factor, the XM5 wins outright. For a student budget, though, the Space Q45 gets you 80-90% of the noise-cancelling experience for roughly a third of the price, plus a longer battery — which matters more than most people expect once exam season gets long.

Which Noise-Cancelling Headphones Should You Buy?

If you’re prepping for a single exam cycle and want the smallest possible spend, go with the boAt Rockerz 450 ANC or the Soundcore Q20i — either will hold up fine for mock tests where mic quality doesn’t matter. If you’re attending daily online classes on top of tests and need reliable multipoint connectivity, the JBL Tune 770NC earns its price. 

And if you’re looking for one pair that will cover you throughout years of coaching, college, and then working remotely, the Soundcore Space Q45 is the best value for money on this list, with the Sony WH-1000XM5 as the upgrade option if budget genuinely isn’t an issue. 

All of Noise-Cancelling Headphones are available on Amazon.in and Flipkart, boAt and Sony also sell directly from their own India stores if you want manufacturer warranty support without a third party seller in the mix. Prices above reflect typical listings as of August 2026 and do fluctuate with sale events — worth a quick price-check before you check out.

boAt Rockerz 450 ANC vs Noise Buds Solo

boAt Rockerz 450 ANC (Over-ear)Noise Buds Solo (Earbuds)
Price₹2,499–2,999₹2,999
Noise blockingANC + passive seal from ear cupsANC only, weaker passive isolation
Comfort for 2-3 hr sessionsBetter for most — no in-ear fatigueSome users get ear fatigue past 90 min
Battery20 hours~36 hours total (earbuds + case)
PortabilityFoldable but bulkierFits in a pocket

If you’re choosing between a headphone and earbuds at roughly the same price, format matters more than spec sheets here. Over-ear wins on raw silence for a long test window; earbuds win on battery life and portability if you’re carrying them between home, coaching class, and a library.

Read More 👉 How to Apply for a Student Loan to Get a Higher Education & Make Career

Conclusion

Best Noise-Cancelling Headphones for online class and mock tests are not always the expensive ones. For most students, the Soundcore Space Q45 provides the best combination of ANC, comfort, battery life, and price, while the boAt Rockerz 450 ANC and Soundcore Q20i are better choices for those on a tighter budget. 

If money is not an issue, the Sony WH-1000XM5 offers the best overall experience. In the end, decide based on the length of your studies, the noise level of your environment and whether you need better microphones or portability in addition to noise cancellation. 

Leave a Comment

Your email address will not be published. Required fields are marked *

Switching Jobs? Don’t Ignore Your EPF, NPS, and Mutual Fund Investments 

Jobs

Your resignation letter is signed, the new offer is accepted, and you’re ready for switching Jobs but what happens to the EPF account and should the new company’s NPS enrollment change anything about how you’re already investing through mutual funds? Don’t Ignore your EPF, NPS and Mutual Fund which most people already are doing.

The EPF vs NPS vs mutual funds decision isn’t really one choice — it’s three separate accounts with three different rules, and a job switch is exactly the moment most people either transfer things correctly or lose track of money they’ve already earned.

What Is EPF, NPS, and Mutual Funds

EPF — 8.25% for FY 2025-26, third year running at that rate, govt-backed, EEE (contribution, interest, withdrawal all tax-free if you cross 5 years’ continuous service). Mandatory for salaried staff at covered establishments; you don’t really “choose” this one, you’re already in it.

NPS — Market-linked, mix of equity/debt/govt bonds you can allocate; extra ₹50,000 deduction under 80CCD(1B) on top of the 80C limit. At exit, minimum 40% of the corpus must go into an annuity — you don’t get the whole pot in cash, and annuity payout rates in India have historically been mediocre (5–6% range).

Mutual funds — No lock-in except ELSS (3 years); LTCG/STCG taxed, no EEE treatment. Best long-run equity return potential of the three, but zero forced discipline — nothing stops you from redeeming during a panic.

Don’t Ignore Your EPF, NPS, and Mutual Funds After Switching Job

Your EPF doesn’t “carry over” automatically. A lot of people assume EPF just follows them to the new job. It doesn’t — not unless you actually transfer it.

When you leave a company, your EPF account under that employer becomes inactive. Your new employer opens a fresh account. If you don’t link the two using your UAN (Universal Account Number), you end up with multiple EPF accounts scattered across your career. Each one earns interest for a while, but an account that stays inactive for 36 months stops earning interest altogether.

How To Set Up Your EPF Account After Job Switch

  • Use the “One Employee One EPF Account” (OEEOA) transfer request on the EPFO portal, or let your new employer initiate it.
  • Don’t withdraw your EPF just because it feels like “extra cash” during the job switch. Withdrawing before 5 years of continuous service makes it taxable, and you lose out on decades of compounding.
  • Check your UAN is correctly linked to Aadhaar and your new employer’s establishment ID — half of all transfer delays come from mismatched KYC details.

The instinct to cash out is understandable when you’re between Jobs and expenses are piling up. But EPF is one of the few instruments giving you a stable, tax-free return over the long run. Treat withdrawal as a last resort, not a bonus.

Read More 👉 Your Credit Score Ignores 90% of Your Financial Life — What Your First Credit Card Changes 

Check Your NPS Before Leaving the Company

Your NPS account isn’t tied to your employer at all. It’s tied to you, through your PRAN (Permanent Retirement Account Number). So technically, nothing needs to be “transferred.”

But there’s a catch. If your NPS contribution was happening through your employer under the corporate NPS model, that contribution stops the day you resign. Your new employer may or may not offer an NPS benefit. If they don’t, your account doesn’t close but it goes silent unless you start contributing on your own through the eNPS platform or a POP (Point of Presence).

What to check:

  • Confirm your new employer’s NPS deduction is active and linked to your existing PRAN — don’t let them create a second one by mistake.
  • If your new company doesn’t offer NPS, decide if you want to keep contributing voluntarily. Many people simply let it sit, which defeats the purpose of consistent, long-term retirement investing.
  • Update your bank and nominee details after the switch — this is the most commonly skipped step.

NPS rewards discipline more than any other retirement product because of how compounding and low fund management costs stack up over 20-30 years. A gap of even a couple of years in contributions has a real, measurable impact on your final corpus.

Mutual funds: the SIPs nobody remembers to check

Job switches usually come with a change in salary account, and that’s where mutual fund SIPs quietly break. If your SIP auto-debit was linked to your old salary account and you close that account (or stop maintaining the minimum balance), your SIP simply fails. Most people don’t notice for months — until they check their portfolio and realize three or four SIP cycles never went through.

What to do immediately after switching:

Re-link your SIP mandates to your new primary bank account, or keep enough balance in the old one until the transition is smooth.

Review your asset allocation. A new job often means a new salary, new expenses, maybe new financial goals (relocation, higher rent, a shorter or longer commute cost). Your SIP amounts should reflect your current life, not your old one.

If you got a signing bonus or relocation allowance, resist the urge to let it sit in a savings account. Even a lump sum top-up into an existing fund puts that money to work instead of losing value to inflation.

What Happens If You Neglect These Procedures

None of this is complicated. It’s just easy to postpone because nothing about it feels urgent in the middle of a job change. But delayed EPF transfers lose interest. Paused NPS contributions lose compounding years you can’t get back. Broken SIPs mean missed market cycles.

A Jobs switch is one of the few moments where you’re forced to look at your entire financial setup at once — new salary, new perks, new expenses. Use that moment. Spend one weekend afternoon logging into EPFO, checking your PRAN, and confirming your SIPs are active. It’s boring, unglamorous work. It’s also the difference between a retirement corpus that actually reflects your career and one that has quiet, unexplained gaps in it.

Your new job deserves your excitement. Your old investments deserve five minutes of your attention before you move on.

Read More 👉 Collateral vs No Collateral Loan Amount Where Collateral Starts Making Financial Sense

Conclusion

Switching Jobs is exciting but don’t ignore your EPF, NPS, and mutual funds investment as it is a chance to reset your financial checklist. Your EPF needs to be transferred, your NPS needs to stay linked to your PRAN, and your mutual fund SIPs need to keep running without interruption.

You don’t have to choose between EPF vs NPS vs mutual funds, understanding the role each plays in your long-term financial plan is important. EPF provides retirement stability, NPS adds a dedicated retirement investment option, while mutual funds offer greater flexibility and growth potential.

Leave a Comment

Your email address will not be published. Required fields are marked *

Your Dollar Income Isn’t Fixed: How INR Volatility Changes Freelancers Earning 

INR Volatility

If you are a student or IT engineer and have a side freelancing business then exchange rate updates is the second in your search list. Once you understand Impact of Exchange Rates On Freelancers In India and how it moves forward then you can earn a little more. Let’s take a look at some important points to understand INR Volatility isn’t about what you’re actually thinking.

You raised the invoice in August. $1,000, net 30, client in Austin. By the time the payment actually lands in your account in September, the number in rupees isn’t what you calculated when you sent it. Maybe it’s more. Maybe it’s less. Either way, you didn’t do anything different — the client paid exactly what they owed — and your income still moved. 

That gap is what most freelancers mean when they say the rupee is “volatile,” and most of them are only half right about what that word actually costs or earns them. 

Current Changes In INR Volatility 

As of September 9, the dollar was trading around ₹95.13, after touching two-month highs near ₹94.4 the week before on the back of sustained Reserve Bank of India intervention. Zoom out to the 12-month view, the rupee has weakened roughly 8% against the dollar over the past year. For a freelancer billing in USD, that’s not a warning sign — it’s a raise you didn’t ask for.

Run the math on a flat $1,000 invoice. At a rate near ₹88 (roughly where the pair sat a year ago, working backward from the reported annual move — treat this as an approximation, not a verified historical quote), that invoice cleared around ₹88,000. 

At today’s rate, the same $1,000 clears closer to ₹95,000. Same client, same scope, same invoice — ₹7,000 more in your account, before any platform fees. If your Gigs, your budgeting, or your client pricing only accounts for the dollar amount, you’re missing the part of your income that moved on its own.

Why “Volatile” Doesn’t Mean “Falling” 

If you thought “the rupee is volatile” means “the rupee is always losing value, brace yourself.” But that’s not what volatility means, and it’s not what the data shows. The rupee gained about 0.9% in the week leading into September 9, with the RBI actively defending the band using its foreign exchange reserves. A currency that can move up or down 1% in a week, depending on which government or central bank decides to act, is unpredictable — not one-directional.

The near-term pressure right now is coming from oil. Brent crude jumped roughly 8% to around $97 a barrel after US-Iran tensions escalated, and India imports the overwhelming majority of the crude it uses, so a sustained spike pushes the rupee the other way — weaker, which again works in a dollar earner’s favor, but also raises input costs across the economy, indirectly squeezing the Indian clients some freelancers also serve. 

Layer on the US Federal Reserve’s meeting scheduled for September 15–16, where a rate move could swing global dollar demand overnight, and you’ve got a currency pair reacting to three or four separate levers in the same month. Betting on “the rupee only goes one way” is how freelancers get caught flat when it doesn’t.

Read More 👉 UP Anganwadi Bharti 2026 — District-Wise Vacancies & Recruitment Details

Impact of Exchange Rates On Freelancers In India

Here’s the part that costs freelancers real money and rarely makes it into the currency conversation: the spread between the rate you see on Google and the rate you actually receive. This gap is usually bigger than the market’s actual weekly movement. And it fills only when you understand Impact of Exchange Rates On Freelancers In India.

PayPal is the most expensive route by a wide margin — a cross-border transaction surcharge that can run up to 4.4%, stacked with a currency markup of roughly 3.5–4.5%, pushes total cost toward 6% on some routes. 

Payoneer, common for Upwork and Fiverr payouts, charges around 1% to move funds to your bank plus an FX markup that can reach 2% on withdrawal into a different currency — so a $2,000 month can quietly lose $50–60 to fees that never show up as a single visible number. 

Wise is the outlier: it settles at the mid-market rate — the actual number you’d see on Google — with a transparent fee that’s usually under 1% for most USD-to-INR transfers, which is why it’s become the default for freelancers paid directly by clients rather than through a marketplace.

None of that shows up when you’re only watching the headline USD/INR number. A freelancer who tracks the exchange rate obsessively but invoices through PayPal is optimizing the wrong variable.

Read More 👉 Foreign Education Loan Currency Explained: How INR Depreciation Can Increase Your Loan Cost 

How To Check Your USD Income is Moving Forward

Stop checking “what’s the rupee doing today” in isolation. Three things move it, and all three are trackable without a finance degree: RBI intervention behavior (visible in how tightly the rate is held to a band, like the ₹94.5–95.3 range this week), Fed rate decisions (scheduled, public, and usually priced in days ahead), and oil price swings (Brent crude, since India’s import bill is the direct transmission line into rupee weakness or strength).

Practically, that means two things for how you run your freelance income. First, match your payout method to your income source — Payoneer if most of your work comes through marketplaces, Wise if you invoice direct clients — because the fee gap between them is often larger than a month’s currency movement. 

Second, if you’re pricing recurring retainers in USD, revisit them quarterly rather than annually; an 8% currency shift plus a fee structure you haven’t audited in a year is easily a 10–12% swing in what a “fixed” retainer actually pays you in rupees.

Your dollar invoice was never the number that mattered. The rupee number that hits your account is — and that number has three separate forces acting on it before you even get to the part your payment platform quietly takes.

Read More 👉 Planning MBBS or Master’s Abroad? Country-Wise Costs, Loan Limits and Lenders

Conclusion 

For Indian freelancers, earning in dollars doesn’t mean earning a fixed amount. The USD/INR rate, RBI and Fed decisions, oil prices, and payment-platform fees can all change what finally reaches your bank account. A $1,000 invoice can be worth noticeably more or less in rupees without the client changing a thing.

The smart move isn’t to predict the impact of Exchange Rates On Freelancers In India. It’s to understand how currency movements affect your real income, compare payout fees, and review your USD pricing regularly. For IT students planning to freelance or work with overseas clients, learning this early can help turn Dollar Income into something you can actually budget around.

Leave a Comment

Your email address will not be published. Required fields are marked *

Scroll to Top