Best Lightweight Sunglasses for Student Life 

Sunglasses

A pair of sunglasses in a college backpack is a choice of your comfort. When the college campus is large and you need to walk in direct sunheat or you go out randomly somewhere with your friends and your eyes start to burn in the heat. That’s where you start hunting for Best Lightweight Sunglasses for students, the best is the one which gives you comfort, weightless, and perfect for your face.

What Actually Matters for Campus-Ready Sunglasses

Frame weight comes down to material, not brand name. TR-90 and polycarbonate frames flex instead of snapping when they get crushed in a bag, and they sit lighter on the nose during a three-hour library stretch than metal or thick acetate does. UV protection — specifically UV400 — isn’t optional no matter how cheap the pair is; it’s the one spec that protects your eyes rather than your outfit. 

Polarization is worth paying a little more for if you’re on a bike or scooter daily, since it cuts glare off wet roads and car windshields far better than plain tinted lenses. And because these things get lost, borrowed by roommates, or sat on at least once a year, price-to-replacement-cost matters more here than it would for a pair you’d baby at home.

The 5 Best Lightweight Sunglasses for Students 

1. Fastrack Polarized Wayfarers and Aviators

Price: ₹950–₹5,000 | Frame: TR-90 polycarbonate | Lens: UV400, polarized options | Best for: tightest-budget daily wear
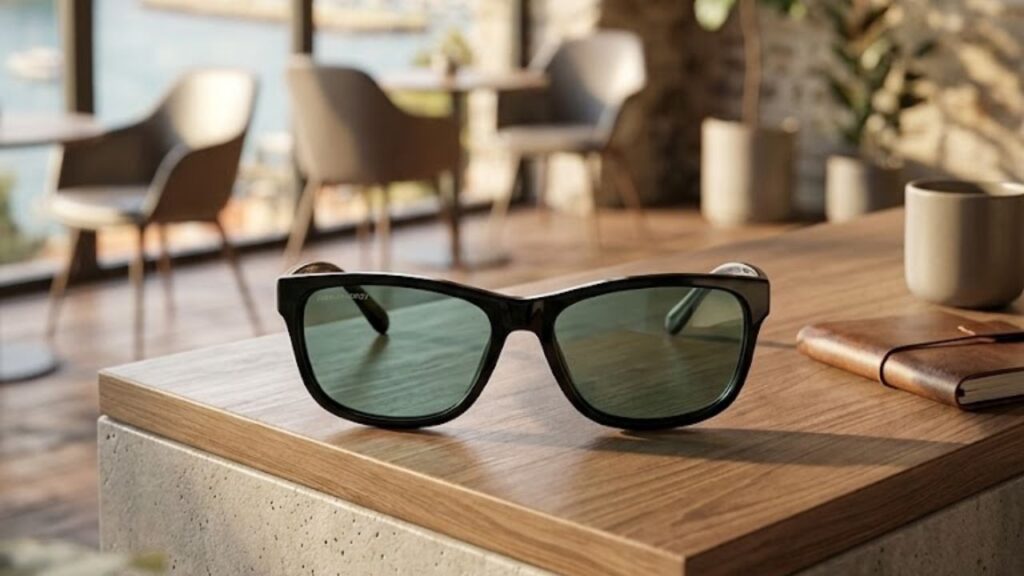

Fastrack’s entry-level polarized range starts under ₹1,000 and still comes with a 1-year warranty on lenses and frames, which is unusual at that price point. The TR-90 build is genuinely flexible — it survives the kind of backpack abuse a rigid acetate frame won’t. The trade-off is build quality at the very bottom of that price range: some buyers report the cheapest models feeling plasticky compared to what ₹2,000+ gets you in the same lineup. Good for someone who wants a backup pair as much as a main one.

2. Vincent Chase by Lenskart

Price: From ₹999, polarized from ₹1,299 | Frame: TR90 | Lens: 100% UV protected, polarized | Best for: best value-for-money on a first “real” pair
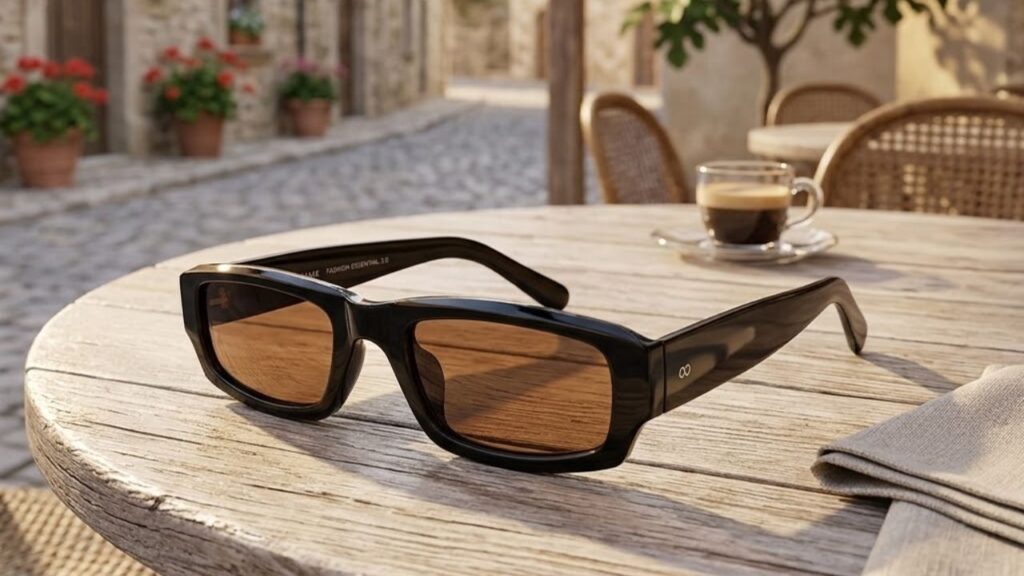

Vincent Chase is Lenskart’s in-house line, and it’s built around the same TR90 material for the same reason — daily wear without weight. The advantage over Fastrack is availability: Lenskart runs frequent Buy 1 Get 1 offers on this line, which effectively gets you a backup pair for the price of one. The catch is that heavy discounting means style availability shifts often, so a specific frame you like online today may not be there in three months if you need a replacement in the exact same shape.

3. OPIUM Eyewear

Price: ₹1,500–₹5,000 | Frame: lightweight polycarbonate | Lens: UV400, polarized, AVS coating | Best for: students who scratch or drop glasses often
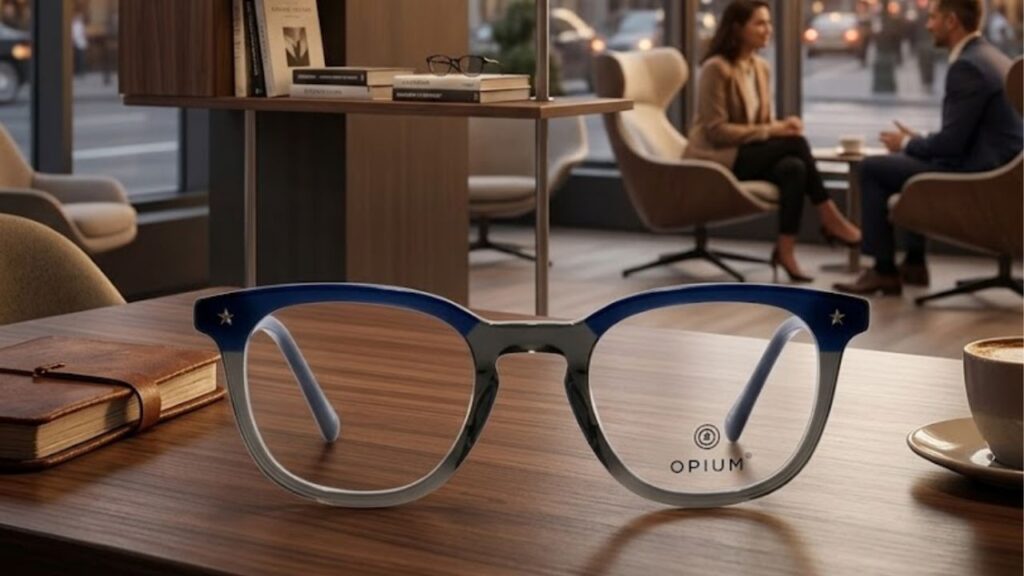

OPIUM’s AVS lens coating adds hydrophobic, oleophobic, and anti-static properties on top of standard UV/polarized protection — practically, that means fewer smudges from fingerprints and better scratch resistance when the lenses rub against keys or coins loose in a bag. It sits a notch above Fastrack and Vincent Chase in price, which is the real trade-off: you’re paying for lens durability, not a jump in style tier.

4. IDEE

Price: ₹899–₹1,499 | Frame: lightweight, sporty builds | Lens: UV protected | Best for: gym, sports, or an active daily commute
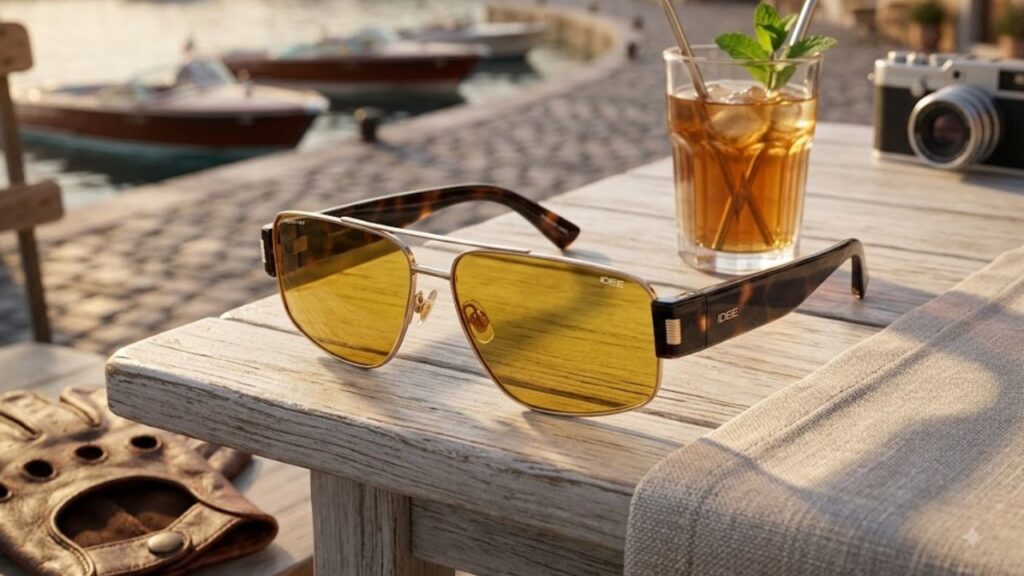

IDEE leans into bold, sporty designs — wraparounds and neon accents rather than classic wayfarer shapes — and stays cheap while doing it. If your daily routine includes a run, a cycle to campus, or intramural sports, the closer-wrap fit holds better than a flat wayfarer frame. The limitation is versatility: the sportier shapes don’t double as well for a formal event or an internship interview the way a classic frame does.

5. Ray-Ban (Aviator / Wayfarer)

Price: roughly ₹7,000–₹15,000 depending on style and retailer | Frame: acetate/metal | Lens: UV400, optional polarized | Best for: one pair meant to last through all four years

Ray-Ban is the outlier on this list by price, and it’s here for a specific reason: it’s the one pair that isn’t disposable. The Original Wayfarer and Aviator have been in continuous production since 1952 and 1937 respectively, which means replacement parts, nose pads, and repairs are easy to find at any optician years later — something none of the budget brands above can promise. It only makes sense if you can absorb the upfront cost and genuinely won’t be swapping styles every semester.

The Real Face-Off of Fastrack & Vincent Chase 

These two get compared constantly because they’re the two brands most students actually cross-shop, so here’s the direct read:

FastrackVincent Chase
Entry price₹950₹999
Polarized entry priceIncluded in mid-rangeFrom ₹1,299
Warranty1 year (lens + frame)Standard return window, no stated 1-yr warranty
Where to buyFastrack’s own site, Titan Eye+, Flipkart, Tata CLiQLenskart, Amazon.in
Recurring offersOccasional salesFrequent Buy 1 Get 1

If warranty coverage matters more to you than getting two pairs, Fastrack wins. If you’d rather have a spare pair sitting in a drawer for when the first one inevitably gets sat on, Vincent Chase’s BOGO structure is hard to beat on pure economics.

Which One Should You Actually Buy?

If your budget is genuinely under ₹1,200 and you just need something functional for the sun on your walk to class, get the Fastrack or Vincent Chase entry model — there’s no meaningful difference in daily performance between them at that price. If you’re riding a two-wheeler daily, prioritize a polarized lens over anything else on this list; glare off a windshield or wet road is a real safety issue, not just comfort. 

If you’re the person who’s cracked three pairs of earphones and lost two water bottles this year, don’t buy OPIUM or Ray-Ban — buy the cheapest polarized Fastrack you can find and expect to replace it. And if you’ve got one splurge in your accessory budget for the year and want something that’ll still be wearable at your graduation photos, the Ray-Ban is the only pair on this list built to actually last that long.

One habit that extends your sunglasses lifespan –  a hard case, not the soft pouch that comes in the box. Most lens scratches on student sunglasses don’t happen while wearing them, they happen loose in a bag next to keys and a laptop charger.

Read More👉 iPhone 18 Pro on EMI: A Complete Buying Guide

Conclusion

The Best Lightweight Sunglasses for Everyday Student Life aren’t always expensive. Whatever you opt for, be sure to focus on UV400 protection, a lightweight frame, a comfortable fit, and polarization for when glare is an issue. Toss a hard case In Addition your backpack, and even a modest pair can make it through life on the daily grind of college. Pocket your case for your backpack and even a thrifty pair can easily keep up with daily college life. 
Leave a Comment

Your email address will not be published. Required fields are marked *

Best Noise-Cancelling Headphones for Online Classes and Mock Tests 

Headphones

You’re 40 minutes into a 3-hour mock test, deep into the reasoning section, and someone two floors down starts drilling a wall. Or it’s your neighbor’s TV bleeding through during a live online class, right when the teacher explains the one concept you actually needed. With best Noise-Cancelling Headphones, it is possible to block the noise out the room, stays comfortable for hours, and doesn’t die halfway through a session. 

As that kind of interruption doesn’t just annoy you — it costs you marks and attention you can’t get back. The right pair of Noise-Cancelling Headphones for online classes and mock tests is meant for this. Not just any Headphones — most people don’t need studio-grade audio for a lecture or a test window. Here are best picks that actually do that, across different budgets.

Why ANC Matters More for Exams Than for Music

Active noise cancellation in short ANC, helps prevent outside noise with an inverse sound wave by using a microphone and it is so effective on low-frequency and steady sound like traffic, fans, washing machine, TV, and construction site but less effective random sharp noises like barking or door slamming.

For a 2-3 hour mock test, that steady cancellation is what keeps your focus from draining. For live classes, you also need a decent mic, since ANC alone won’t help your teacher hear you over a ceiling fan.

Best Noise-Cancelling Headphones for Online Classes and Mock Tests

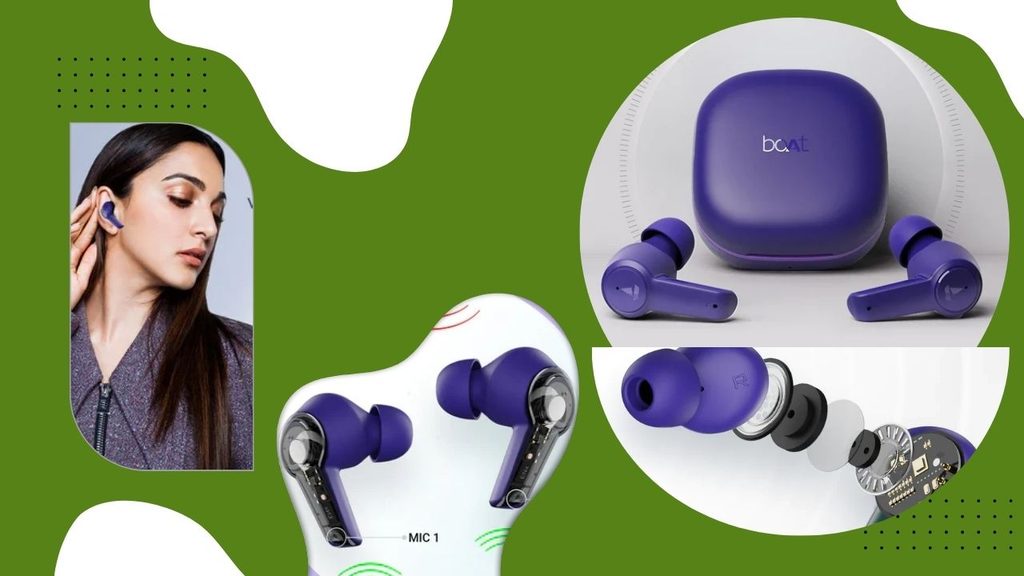
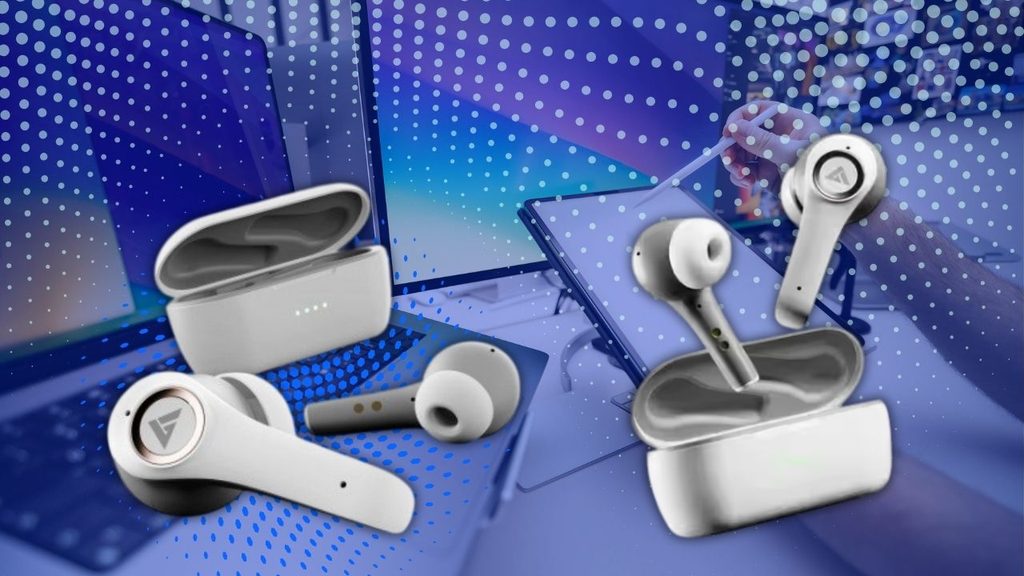
1. boAt Airdopes 413 ANC — ₹1,999

  • 25dB Active Noise Cancellation
  • ENx dual-mic technology for calls
  • ~20 hours total battery (earbuds + case)
  • In-ear TWS design


This is about as cheap as real ANC gets in India, and it holds up for what it is — steady background noise gets noticeably duller, which is the whole point during a test. The case battery isn’t huge, so charge it the night before a long mock test rather than assuming it’ll carry you through a full day.

Best for: the tightest possible budget where any real ANC beats none.

2. Boult Audio Omega — ₹2,499

  • Active Noise Cancellation + separate ENC chip for calls
  • 4 mics per stem, touch controls
  • ~32 hours total battery (8hr earbuds + 24hr case)
  • Dedicated Game Mode for low latency

The separate ENC chip is the standout here — it’s built for call clarity, which matters if your online classes involve a lot of back-and-forth with the teacher rather than passive listening. If you are also looking for gaming purposes, not just for mock test sessions then low-latency mode is an additional benefit in Boult Audio Omega.

Best for: students who have live classes and online courses to attend rather than recorded lectures.

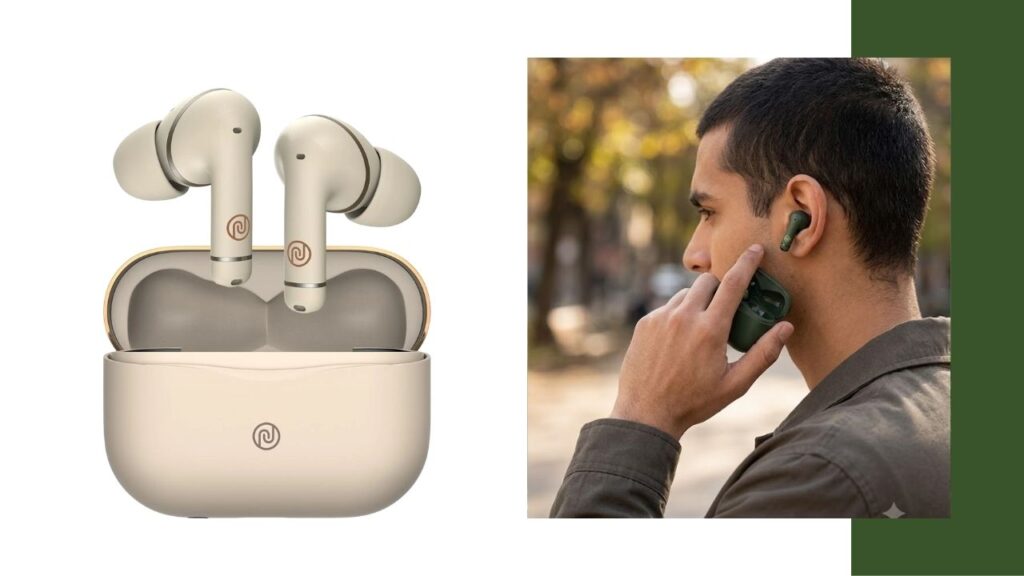
3. Noise Buds Solo — ₹2,999

  • Active Noise Cancellation with switchable Transparency mode
  • 10mm driver, touch controls for calls/music/voice assistant
  • ~36 hours total battery (7hr earbuds + case)
  • Interchangeable eartips for fit
Noise Buds Solo


The 36-hour total battery is the best in this budget tier, and the switchable Transparency mode is genuinely handy — flip it on for five minutes if someone’s calling you from another room, without pulling an earbud out mid-test. Interchangeable eartips also make a bigger difference than you might realize; a bad seal will ruin passive noise isolation even before ANC activates. 

Best for: the best all-round earbud pick under ₹3,000 if battery life is your priority.

Read More👉 Best Laptops for Coding and Programming: Top Picks for Every Budget

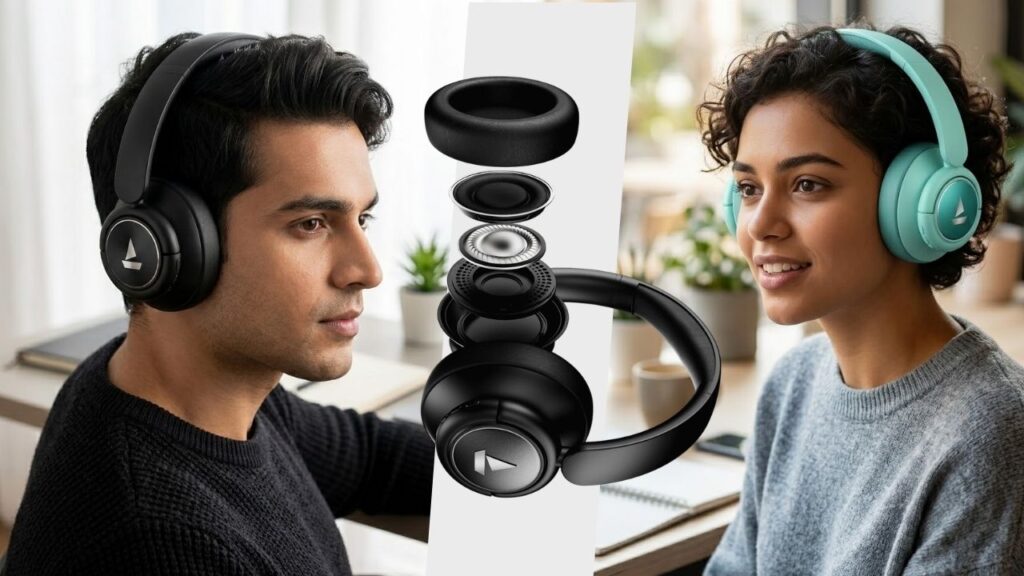
4. boAt Rockerz 450 ANC — ₹2,499–2,999

  • Hybrid ANC (up to 25dB reduction)
  • 20-hour battery life with ANC on
  • 40mm dynamic drivers, BEAST mode for low-latency audio
  • On-ear, foldable design
boAt Rockerz 450 ANC


This is the one to get if you just need to shut out a noisy house without spending a month’s pocket money. The ANC won’t touch a jackhammer, but it flattens fan noise, traffic hum, and a TV in the next room reasonably well. The ear cushions get a little warm after 2+ hours, and call clarity is average — fine for a mock test, less ideal if you’re live-unmuting often in class.

Best for: students on a tight budget who mainly need ANC for silent, focused test-taking.

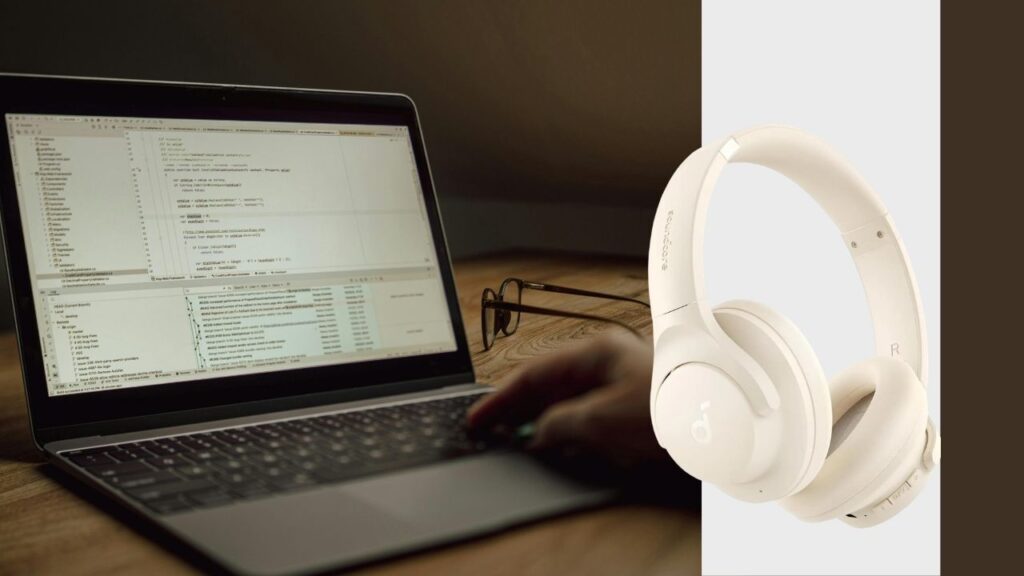
5. Soundcore Q20i — ₹4,298

  • Hybrid ANC with Indoor/Outdoor/Transport modes
  • 40-hour battery life with ANC on
  • Soft protein-leather earcups
  • Wired mode available (3.5mm) when the battery does die
Soundcore Q20i


The battery life here is the real selling point — 40 hours means you could go through an entire mock-test series for a week without touching the charger. The Indoor mode specifically tunes the ANC for steady household noise rather than street sound, which is exactly the scenario most Indian students are dealing with. The bass is a bit boosted for critical listening, but for lectures and tests that’s irrelevant.

Best for: anyone who forgets to charge things — this Noise-Cancelling Headphones forgives you.

6. JBL Tune 770NC — ₹8,999–10,999

  • Adaptive ANC that responds very quickly to the surrounding noise automatically
  • 50-hour battery life (ANC off), around 44 hours with ANC on
  • Multipoint Bluetooth (connect to phone and laptop simultaneously)
  • 40mm drivers with JBL Signature Sound
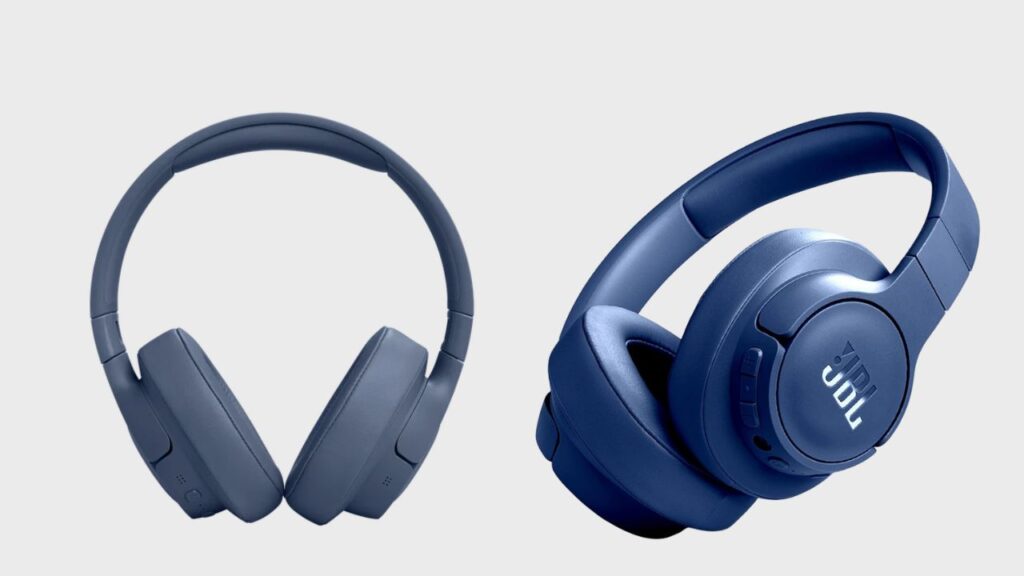
JBL Tune 770NC

The multipoint pairing is genuinely useful if you attend classes on a laptop but take calls or check notifications on your phone — no fumbling with Bluetooth settings mid-lecture. Adaptive ANC means it automatically dials up cancellation when your maid starts sweeping and dials back down when it’s quiet, instead of a fixed on/off toggle. Bass is JBL’s usual signature — punchy, a little forward — which some people love and others find a bit much for spoken-word content.

Best for: students juggling both a laptop for classes and a phone for everything else.

7. Soundcore Space Q45 — ₹9,999 (often available around ₹8,500–9,000 on sale)

  • Adaptive ANC rated up to 98% noise reduction
  • 50-hour battery life with ANC on
  • LDAC support for Hi-Res audio over Bluetooth
  • Memory foam earcups, app-based custom EQ

This is the closest thing to flagship-level ANC without paying flagship prices. The 98% noise reduction figure holds up well against consistent background noise — the kind you get from a busy street or a joint family household during the day. Good memory foam cushions really do make a difference during a 3-hour test because your ears are not sore at the end. The app is actually useful, allowing you to choose a “study” EQ preset that cuts mid-bass boom, making spoken word clearer while you’re studying or attending lectures.

Best for: the best all-round pick if you want near-premium ANC without the premium price tag.

Read More👉 Best Student Loans for College Students

8. Sony WH-1000XM5 — ₹29,990

  • Industry-leading ANC with 8-microphone array and dual processors
  • 30-hour battery life with ANC on
  • Speak-to-Chat: automatically pauses audio when you start talking
  • Precise Voice Pickup Technology for clearer calls
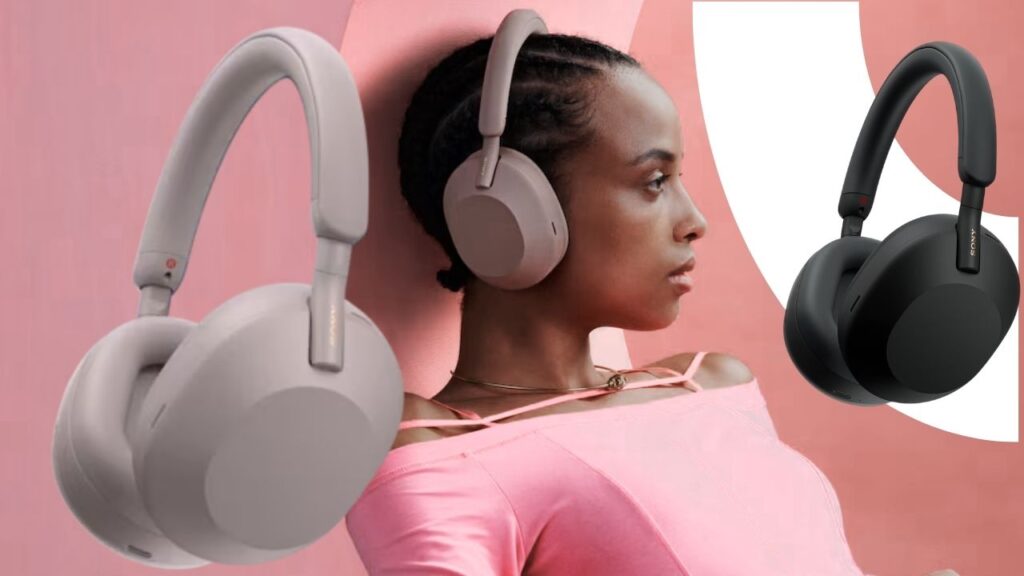
Sony WH-1000XM5

If your budget stretches this far, the XM5 is close to overkill for a student use case — but that’s not a bad thing. A duo which makes you feel like you are sitting in an exam hall rather than your house. When you’re nervous your voice gets lower that people sitting behind the system couldn’t understand but Sony WH-1000XM5 gives an automatic Speak-to-Chat feature that pauses automatically if you say something out loud and passes your lower voice very smoothly. But this is too expensive for students but college students who strictly need can buy it on EMI

Best for: students who treat this as a long-term investment across school, coaching, and eventually work-from-home use.

Sony WH-1000XM5 vs Soundcore Space Q45

Sony WH-1000XM5Soundcore Space Q45
Price₹29,990₹9,999
ANC strengthBest-in-class, handles sudden noise tooExcellent against steady noise, weaker on sudden sharp sounds
Battery (ANC on)30 hours50 hours
Mic quality for classesBest on this listGood, not exceptional
Value for a student budgetLow — premium pricingHigh — near-flagship ANC at a third of the price

If money weren’t a factor, the XM5 wins outright. For a student budget, though, the Space Q45 gets you 80-90% of the noise-cancelling experience for roughly a third of the price, plus a longer battery — which matters more than most people expect once exam season gets long.

Which Noise-Cancelling Headphones Should You Buy?

If you’re prepping for a single exam cycle and want the smallest possible spend, go with the boAt Rockerz 450 ANC or the Soundcore Q20i — either will hold up fine for mock tests where mic quality doesn’t matter. If you’re attending daily online classes on top of tests and need reliable multipoint connectivity, the JBL Tune 770NC earns its price. 

And if you’re looking for one pair that will cover you throughout years of coaching, college, and then working remotely, the Soundcore Space Q45 is the best value for money on this list, with the Sony WH-1000XM5 as the upgrade option if budget genuinely isn’t an issue. 

All of Noise-Cancelling Headphones are available on Amazon.in and Flipkart, boAt and Sony also sell directly from their own India stores if you want manufacturer warranty support without a third party seller in the mix. Prices above reflect typical listings as of August 2026 and do fluctuate with sale events — worth a quick price-check before you check out.

boAt Rockerz 450 ANC vs Noise Buds Solo

boAt Rockerz 450 ANC (Over-ear)Noise Buds Solo (Earbuds)
Price₹2,499–2,999₹2,999
Noise blockingANC + passive seal from ear cupsANC only, weaker passive isolation
Comfort for 2-3 hr sessionsBetter for most — no in-ear fatigueSome users get ear fatigue past 90 min
Battery20 hours~36 hours total (earbuds + case)
PortabilityFoldable but bulkierFits in a pocket

If you’re choosing between a headphone and earbuds at roughly the same price, format matters more than spec sheets here. Over-ear wins on raw silence for a long test window; earbuds win on battery life and portability if you’re carrying them between home, coaching class, and a library.

Read More 👉 How to Apply for a Student Loan to Get a Higher Education & Make Career

Conclusion

Best Noise-Cancelling Headphones for online class and mock tests are not always the expensive ones. For most students, the Soundcore Space Q45 provides the best combination of ANC, comfort, battery life, and price, while the boAt Rockerz 450 ANC and Soundcore Q20i are better choices for those on a tighter budget. 

If money is not an issue, the Sony WH-1000XM5 offers the best overall experience. In the end, decide based on the length of your studies, the noise level of your environment and whether you need better microphones or portability in addition to noise cancellation. 

Leave a Comment

Your email address will not be published. Required fields are marked *

How to Start a Mineral Water Business: Complete Guide

Mineral Water Business

Students who want to start a business while studying that will grow with time when they get passed out but don’t know how to start a mineral water business, stay consistent and understand everything step-by-step. Why the Mineral Water Business ? Because it’s easy and needs less investment so students can easily work it out.

In every area there’s someone on a bicycle, two or three 20-litre cans strapped to the back seat, making rounds before the 9 a.m. lecture. And you’re wondering about the cost per can, number of houses in the block, weekly demand and deciding to start a mineral water business. It sounds like the side income you’ve been looking for.

It’s not a bad instinct. Even if you don’t have six months of free time, and lakhs of rupees sitting idle. You can still set up your small business amid juggling a timetable, a hostel curfew, and exam weeks. Here’s what actually applies if you’re starting this while you’re still enrolled.

Mineral Water Business Is Different From Packaged Drinking Water

The label gets used loosely, and that’s where a lot of first-time entrepreneurs trip up. Under Indian standards, “natural mineral water” (IS 13428) and “packaged drinking water” (IS 14543) are two different categories. The natural mineral water is sourced from a protected mineral spring, while packaged drinking water is the RO-and-UV purified water in cans and bottles that almost every local plant actually sells. 

If you’ve ever seen a delivery guy with unbranded 20-litre cans, that’s packaged drinking water, not mineral water in the technical sense — even though everyone calls it “mineral water” on the street.

It matters because both categories legally require BIS certification if you’re selling them in a sealed, labelled container under a brand name. FSSAI registration is a separate, additional requirement that applies to anyone in the food and water supply chain — manufacturer, distributor, or reseller. 

Skipping either one isn’t a grey area; local FDA teams do seal unlicensed plants, and it happens more often than people expect. If you don’t have much money then you can apply for FSSAI certification to start with.

The Reality of Setting Up A Brand of Water

If the plan is to manufacture and bottle your own brand, here’s the honest range, based on current supplier and consultancy listings — treat these as ballpark figures and verify locally, since they shift by state, capacity, and vendor:

  • BIS/ISI certification facilitation through a consultant typically runs somewhere in the ₹35,000–₹70,000 range.
  • Entry-level packaged drinking water machinery (RO plant, filling, capping) starts around ₹2.4 lakh for lower-capacity units and climbs past ₹13 lakh for higher-capacity setups.
  • A full project — machinery, water-testing lab, premises — can land around ₹25 lakh once you include everything, which is roughly the scale seen in real project reports built for government-backed loans like PMEGP, financed mostly through a bank loan plus KVIC margin-money subsidy.

None of that is pocket money, and the setup timeline — BIS testing cycles, layout approval, machinery installation — usually runs months, not weeks. It’s a business for after you graduate, or for a family that already owns a plant.

Read More 👉 Best Noise-Cancelling Headphones for Online Classes and Mock Tests 

How to Start a Mineral Water Business While Studying

The workaround isn’t to skip compliance — it’s to skip manufacturing. Instead of building a plant, tie up with a local packaged drinking water plant that already holds FSSAI and BIS certification, and become their reseller or delivery partner in a specific area you can actually cover between classes.

You’ll still need your own FSSAI Basic Registration — it’s mandatory for anyone distributing or reselling food and water products, not just manufacturers, but it’s a low-cost, online process aimed at businesses with turnover under ₹12 lakh a year. No lab, no machinery, no factory inspection required at this tier.

However, you can’t put your own brand name on someone else’s water without their manufacturer backing you under their BIS license. Either sell openly under the supplier’s existing brand as their authorized reseller, or have a documented dealership arrangement. Your own labelled brand is the manufacturing route above — a later-stage move, not a starting point.

How to Manage Your Business While Attending Classes

A few things make the difference between this staying manageable and it eating your semester:

  • Keep the radius tight. Your own hostel block, one PG cluster, or a few shops near campus — something you can cover in under 15 minutes so it fits around lecture slots.
  • Vet suppliers in person. Visit two or three candidate plants, ask to physically see their FSSAI certificate and BIS license number rather than taking their word for it.
  • Apply for FSSAI Basic Registration early — it’s inexpensive and doesn’t take long, but it’s not something to leave until customers are already asking for it.
  • Run subscriptions, not daily orders. A weekly or monthly can subscription over WhatsApp is far easier to manage during exam weeks than fielding one-off orders every day.
  • Budget for the deposit cycle. Most local can systems run on a refundable can deposit — commonly in the ₹50–100 range per can, though this varies by supplier. That money is tied up as working capital until the empty can comes back, not profit you can spend.
  • GST registration only becomes mandatory once turnover crosses ₹40 lakh a year for goods in most states (lower in a few special-category states). Most student-run operations won’t hit that in year one.

Where Student Water Businesses Usually Fail

Three patterns show up repeatedly, and they’re worth naming before you start rather than after:

Treating it as passive income when it’s really a logistics job — someone has to physically move 20-kilogram cans at a fixed time, every week, including exam season. Letting the deposit-cash mismatch creep up — if thirty cans are out with customers and only ten deposits have come back, the working capital gap is real and it stalls reorders. 

And trying to compete on price against an established local operator who already owns the plant and the delivery network — a student reseller almost never wins that fight, and shouldn’t try. The actual pitch is convenience: reliable timing around class hours, UPI payment, water dropped right at the door. 

Read More 👉 Business Ideas for Students With Zero Investment — Easy Startup Guide

Where To Begin Your Mineral Water Business?

  • Skip the machinery quote for now. Call two local packaged drinking water plants and ask if they take resellers. 
  • Apply for your FSSAI Basic Registration online. 
  • Then run a 20-can pilot in your own hostel or nearby block before spending a rupee on anything beyond that. 
  • If the pilot survives one full exam cycle without a missed delivery, you’ll know whether this is a real business or just a good week.

Conclusion

Understanding how to Start a Mineral Water Business as a student is different from starting as a manufacturer. So don’t follow large-level business instruction points, begin with less investment and short area to cover. 

While attending your classes, you can set up your side business for passive income and it gets succeeded then you can turn it into a large-scale business. Apply FSSAI registration and track down your reliable provider who already has a water plant industry. Expand the network in the hostel and nearby block to easily deliver the mineral water cans.

Stay consistent and don’t get bored in just one week, keep up with the idea and you’ll get a success. 

Leave a Comment

Your email address will not be published. Required fields are marked *

Best App To Get Instant Loan Without Salary Slip 

Best App To Get Instant Loan Without Salary Slip

Your landlord isn’t waiting, the hospital isn’t waiting, and your bank’s personal loan officer just told you to come back “once you have three months of payslips.” That forces you to google for the Best App To Get Instant Loan Without Salary Slip because you need ₹20,000 urgently. Because there is no payslip coming from a freelancer, or small start ups owner.

This is the exact gap that a new generation of lending apps was built to close. Instead of a salary slip, they read your bank statements, your PAN and Aadhaar history, your UPI transaction pattern, and sometimes your GST filings, and turn that into a credit decision in minutes. 

However, “no salary slip” doesn’t mean “no scrutiny” and it definitely doesn’t mean every app claiming this is safe to use. Below are the Best App To Get Instant Loan Without Salary Slip, let’s see what they actually cost, and how to tell a legitimate lender from a data-harvesting clone before you hand over your Aadhaar.

Why Salary Slips Stopped Being the Only Option

Banks built their lending rules around one kind of borrower: someone with a fixed monthly salary landing on the same date, from the same employer, verifiable on a letterhead. That description fits a shrinking share of India’s workforce. Freelancers, gig-platform workers, small traders, and contract staff earn real, trackable income — it just doesn’t arrive in payslip form.

Digital lenders solved this by switching the input. Instead of a payslip, they pull 3–12 months of bank statements to see how much money moves through your account and how consistently. Self-employed applicants can usually substitute ITR filings, GST returns, or business account statements. 

Some apps go further and factor in your digital footprint — how long you’ve held your phone number, your UPI activity, even your app usage patterns to build a risk score. None of this is charity; it’s just a different, faster underwriting model, and it’s why approval on these apps can take minutes instead of the two-week wait typical of a bank.

Skipping The Salary Slip Doesn’t Mean The Requirement of Documents Ends

Skipping the salary slip doesn’t mean skipping documentation — it just shifts what counts as proof. Across the apps below, the standard ask is a PAN card, Aadhaar for e-KYC, and 3–6 months of bank statements showing regular inflows. 

Self-employed applicants typically add one of: ITR filings for the last one or two years, GST returns if registered, or a business current-account statement. A few apps, like Fibe and mPokket, lean more heavily on alternative signals — how long you’ve had your phone number, your UPI transaction frequency, even basic device data — specifically for applicants who have no ITR or GST paperwork to show at all. 

None of this is optional paperwork replaced by “trust us” — every legitimate lender still needs some way to estimate whether you can repay, it’s just reading your cash flow instead of your employer’s letterhead.

Best Instant Loan Apps Without a Salary Slip Are Listed

1. KreditBee — Best for Small, Fast Loans With No CIBIL History

KreditBee lends through Krazybee Services, an RBI-registered NBFC, and is built for speed on smaller ticket sizes. Loan amounts run from about ₹5,000 up to ₹10 lakh, with tenures between 3 and 60 months. 

Interest rates officially start at 12% p.a., but that floor is reserved for the strongest profiles — most first-time or thin-file borrowers land closer to 24–29.95% p.a., and self-employed applicants specifically are often quoted in the 16–29.95% range. 

Processing fees can run up to roughly 4–5% of the loan amount, deducted upfront from disbursal. The minimum income requirement is just ₹10,000 a month, and a CIBIL score isn’t mandatory. 

Best for: someone who needs ₹10,000–₹50,000 fast and doesn’t have a credit history yet — not for large-ticket borrowing, since the cost climbs fast at that end.

2. Navi — Best for Lower Rates and Larger Loan Amounts

Navi, backed by Navi Finserv, is an app to check if your credit score is solid and you need more money for longer. Loan amounts stretch from around ₹10,000 to ₹20 lakh (some listings show up to ₹10 lakh depending on the product), with tenures up to 84 months. 

Rates start near 9.9–9.99% p.a. for borrowers with a CIBIL score of 700+, but can rise to 29–45% p.a. for weaker profiles — a wider spread than most competitors, so the advertised low rate isn’t guaranteed. 

Processing fees range from 0% to about 4% plus GST. Both salaried and self-employed applicants are eligible with a minimum score of roughly 650. 

Best for: self-employed borrowers with a decent credit file who want a bigger loan without a bank’s paperwork.

3. Fibe (formerly EarlySalary) — Best for Speed

Fibe is an RBI-registered NBFC-P2P platform (license N-13.02139) built around a two-minute approval promise, using an AI model that scans over 100 data points instead of a payslip. Loan amounts go up to ₹5 lakh, rates start at 12% p.a., and it’s known for letting borrowers with no CIBIL score qualify by leaning on digital and social-footprint signals instead. It’s particularly active in Tier-2 and Tier-3 cities where bank branches and traditional documentation checks are less accessible. 

Best for: first-time borrowers who need money today and can accept a higher rate in exchange for near-instant disbursal.

4. PaySense — Best for Consistent Self-Employed Income

PaySense, run on PayU Finance India’s lending infrastructure, uses risk-based pricing rather than one flat rate, so two applicants for the same amount can get different offers. Published eligibility asks for a minimum monthly income of ₹18,000 for salaried applicants and ₹20,000 for self-employed ones, with interest rates typically quoted between 14% and 36% p.a. depending on profile. It accepts a low or even zero CIBIL score, which makes it accessible, but that flexibility shows up in the rate you’re offered. 

PaySense is the Best App To Get Instant Loan Without Salary Slip for self-employed borrowers with steady, provable cash flow who don’t yet have a strong credit file.

5. MoneyView — Best for Tier-2/Tier-3 Self-Employed Borrowers

MoneyView is frequently the first recommendation for salaried applicants outside metro cities and for self-employed or gig workers who want minimal paperwork. It’s positioned between the small-ticket apps and the larger NBFC lenders, with loan amounts up to around ₹10 lakh and rates generally in the low-to-mid double digits for stronger profiles, rising for thinner files — broadly comparable to KreditBee’s range, though it’s often described as steadier on collection practices in user reviews. 

Best for: borrowers outside major metros who want a mid-sized loan without a Tier-1-city credit profile.

6. mPokket — Best for Students and Thin-File Gig Workers

mPokket is built specifically for people the traditional system ignores entirely — students and gig workers with little or no credit history. Loan sizes are smaller than the others on this list, aimed at short-term, small-amount needs like covering a bill or a temporary cash gap rather than a big-ticket expense. It shouldn’t be treated as a recurring source of funds — the sizes and terms make it best suited to occasional, short-duration borrowing. 

Best for: students or new-to-credit gig workers who need a small amount and have nowhere else to turn.

Read More 👉 How to Start a Mineral Water Business: Complete Guide

How To Get an Instant Personal Loan Through Paytm, PhonePe, GPay, and Bhim

The same apps you use to split a dinner bill or pay your electricity bill can also get you a loan — often within minutes. Here’s how each one actually works:

Paytm

Open the Paytm app, head to the “Loans & Credit Cards” section, and tap “Personal Loan.” Paytm lets you apply anytime for an instant loan online in about two minutes, with a fully digital process and loan amounts ranging from ₹5,000 to ₹15 lakh, flexible tenure, and the option to foreclose anytime. 

Paytm doesn’t lend the money itself — it partners with RBI-regulated NBFCs and banks who actually underwrite and disburse the loan. You’ll go through PAN and Aadhaar-based KYC either way.

PhonePe

Same idea, different app. PhonePe doesn’t hand out loans directly — it has partnered with various banks and NBFCs to offer instant loans, so you can apply without ever leaving the app.  Loan amounts go up to ₹5 lakh, repayable over tenures of up to 60 months, at rates starting around 13% per annum, with the approved amount transferred straight to your bank account.  Most lenders here look for a stable income and a credit score around 650 or higher.

Google Pay

Google Pay follows the same partner-lending model as Paytm and PhonePe — it doesn’t lend directly but connects you to its NBFC and bank partners for a pre-approved or application-based personal loan inside the app, with KYC handled digitally via Aadhaar and PAN.

BHIM

This one surprises people, since BHIM is best known as NPCI’s bare-bones UPI app. But it’s expanded: BHIM now lets you explore a personal loan without leaving the app, again through its network of lending partners rather than lending in-house.

How to Check an App Isn’t a Scam Before You Apply

RBI does not license individual apps — it regulates the bank or NBFC behind them. That distinction is the entire safety check:

  • Find the named NBFC or bank. A legitimate app discloses its lending partner clearly in the app, on the Play Store listing, or in the loan agreement. If you can’t find a specific company name, stop.
  • Verify that name on rbi.org.in or the RBI’s Digital Lending Apps directory before you submit any documents.
  • Never pay upfront. Processing fees, “insurance,” or “security deposits” requested before disbursal are the single most common fraud pattern. Legitimate lenders deduct fees from the loan amount after approval, not before.
  • Check what permissions it wants. A real KYC process needs your camera for a selfie and basic identity/banking access — not your full contact list, photo gallery, SMS logs, or call history. Apps that demand those are usually building leverage for harassment-based recovery later, not assessing creditworthiness.
  • Look for a Key Fact Statement (KFS). RBI’s digital lending rules require one before disbursal, listing the all-in APR, not just a headline interest rate. A “1% per month” rate can look harmless until the APR reveals fees stacked on top.
  • Confirm a named grievance officer with a phone number and email — not just a generic contact form.

If two or more of these are missing, treat the app as a red flag regardless of its Play Store rating, which is not proof of regulatory legitimacy. Because the best app to get instant loan doesn’t mean every app is trustworthy.

Advertising Rate Is Always Different From Actual Amount You Receive in Your Account

Headline interest rates on these apps are quoted per annum, but the real cost shows up in the APR, once processing fees and GST on those fees are added in. A concrete example: on a KreditBee loan disbursed at roughly ₹1 lakh, one published breakdown shows a ₹4,000 processing fee (4%), ₹720 GST on that fee, and ₹10 in documentation charges — pushing the effective APR to 29.66%, even though the headline rate for that borrower’s tier read lower. 

The amount that actually lands in the bank account was around ₹95,270, not the full ₹1 lakh. This is exactly what the Key Fact Statement is meant to expose, and it’s why comparing apps on their advertised “starting from” rate alone is close to useless — always ask for the APR and the net disbursal amount before accepting an offer, not just the interest rate.

Read More 👉 How to Apply for an Education Loan Online

Which App Should You Consider For Instant Personal Loan?

  • If you’re a gig worker or freelancer with no credit history and need a small amount fast, start with KreditBee or Fibe. 
  • If you’re self-employed with steady bank statements and want a lower rate on a bigger amount, check Navi or MoneyView first and let your CIBIL score decide between them. 
  • If you’re a student or new to credit entirely, mPokket is built for exactly that gap, but treat it as a short-term bridge, not a repeat solution. 

Conclusion

Whichever  Best App To Get Instant Loan Without Salary Slip you land on, run it through the RBI-verification checklist above before you type in your PAN — that two-minute check is what separates a fair loan from a very expensive mistake.

The absence of a salary slip requirement is a documentation shortcut, not a signal that the loan is free of risk. A ₹20,000 loan at 28% p.a. with a 4% upfront fee still needs to be repaid on schedule, and missed EMIs on these apps report to CIBIL just like a bank loan would. 

Borrow the amount you need for the problem in front of you, not the maximum the app is willing to approve — the higher your sanctioned limit looks, the more tempting it is to take more than the situation actually calls for.

Note: Rates, loan limits, and fees above reflect published figures as of mid-2026 and change frequently based on lender policy and individual credit profile — confirm current terms in-app before applying.

Leave a Comment

Your email address will not be published. Required fields are marked *

How AI Could Change India’s Digital Public Infrastructure

Digital Public Infrastructure 

The shift from traditional systems to Digital India raises concerns about public privacy and security, as greater reliance on digital systems can create new opportunities for fraud and scams. Aadhaar is one pillar of what the government now calls India’s Digital Public Infrastructure and how AI could change that DPI for making it faster and more reliable is the biggest evolution.

Every month, close to 20 million people across India get turned away by a fingerprint scanner or a face-authentication camera that’s supposed to hand them a subsidised ration bag, a pension, or a bank withdrawal. That failure rate — a little over 6% of roughly 312 million Aadhaar-based authentications attempted monthly has stayed almost unchanged for a decade, according to UIDAI’s own parliamentary disclosures. 

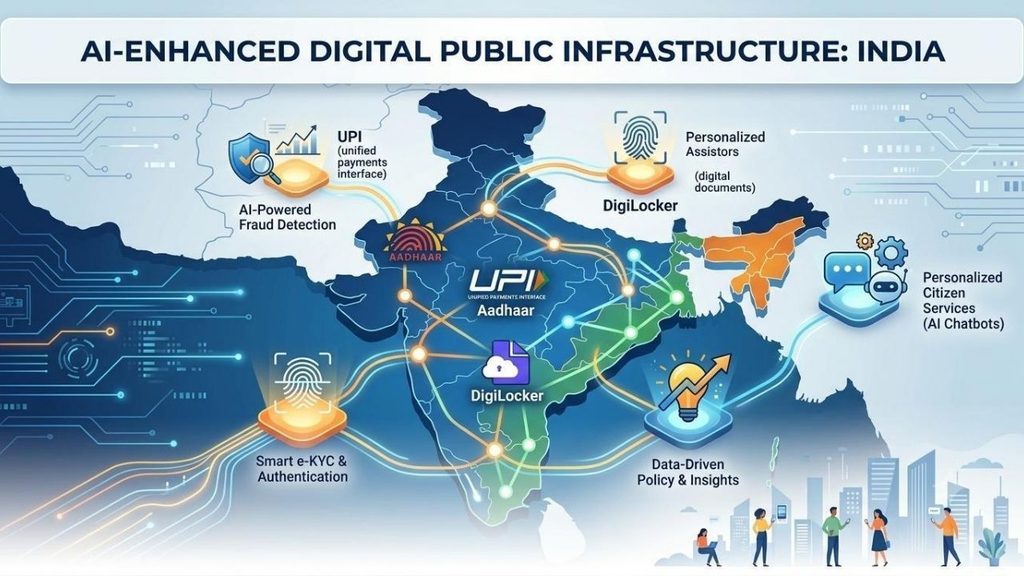
It’s a strange fact to sit with, because DPI includes the stack of identity, payments, and data-sharing rails — Aadhaar, UPI, DigiLocker, Account Aggregator, ONDC — that more than a billion Indians touch, often without realising it. AI is now being wired into nearly every one of those rails. Some of it is already live and working. 

What Is India’s Digital Public Infrastructure 

Aadhaar is the identity layer — a biometric ID held by nearly every adult in the country. UPI is the payments layer, the real-time system that lets any bank app talk to any other. DigiLocker and Account Aggregator are the document and data-sharing layers, letting people share verified paperwork or consented financial records instead of photocopies. 


ONDC is the newest piece, an attempt to do for e-commerce what UPI did for payments: an open network any app can plug into, rather than one company owning the marketplace. 

Each of these was built as plumbing — deliberately boring, interoperable infrastructure. AI is the first layer being added on top that isn’t boring at all, and it’s arriving fastest in fraud detection, credit, language, and now shopping.

Fraud Detection at a Scale No Human Team Can Watch

UPI now clears more than 750 million transactions a day, a number NPCI expects to keep climbing toward a billion. At that volume, catching fraud after the money has moved is close to useless — NPCI’s fraud-detection platform processes roughly 2 terabytes of transaction data daily and needs to score risk within about 20 milliseconds, fast enough to block a payment before it settles. 

Its MuleHunter AI tool has already flagged more than 4.7 lakh mule accounts — the disposable, borrowed accounts fraud rings use to bounce stolen money through four to six hops before cashing out. 

NPCI is now piloting what it calls a “federated model” with three or four banks: instead of pooling everyone’s raw transaction data in one place, banks and NPCI compare AI-generated risk scores on a customer, getting the benefit of shared pattern-matching without centralising anyone’s actual financial history. 

NPCI’s leadership has said openly that the next leg of UPI’s growth depends on AI doing three jobs at once — catching fraud, extending credit based on payment history, and onboarding the next half-billion users through voice and regional-language interfaces instead of English-only screens.

Half of India Still Can’t Access Bank Credit

For decades, an MSME owner without three years of clean, bankable paperwork was mostly invisible to formal lenders — not un-creditworthy, just un-scoreable. 

The Account Aggregator framework, built on the RBI’s 2016 Master Direction and NITI Aayog’s Data Empowerment and Protection Architecture, changed the plumbing: with a customer’s explicit consent, a lender can now pull real bank statements, GST filings, and insurance records through a single encrypted pipe instead of chasing PDFs. 

As of the framework’s fourth anniversary in 2025, 112 financial institutions had gone live on both sides of that pipe, with hundreds more connected as data providers or users. AI models sit on top of that data flow, and lenders report the payoff is real: industry estimates put improvements in default-prediction accuracy at 15 to 25%, and processing times that used to run one to three weeks are increasingly settled same-day. 

This isn’t unregulated black-box lending, though — RBI’s digital lending rules require a lender to explain, in terms a risk officer or auditor can actually interrogate, why a model approved or rejected an application, which puts a real ceiling on how opaque these systems are allowed to get.

Read More 👉 Apple iPhone Duo Changes the Cost Effectively With These Methods

No More Language Barrier: Treating Language Like Infrastructure

India has more than one language and an AI layer that drops the barrier between languages is Bhashini. In India, MeitY’s National Language Translation Mission became fully AI-powered translation engines and it now sits underneath every government services app from January 2026. Portals like DigiLocker, UMANG, e-Shram running into 22 Indian languages. 


A Bhashini-powered voice assistant called Kumbh Sahaiyak used a Llama-based model to field pilgrim questions in 11 languages in real time — arguably the clearest proof yet that a DPI project can meet people in their own language at genuine crowd scale, not just in a pilot deck. If India’s Digital Public Infrastructure’s whole promise was ever about reaching people who can’t fill out an English form, Bhashini is the piece actually doing that, one API call at a time.

The Part AI Might Not Fix: Aadhaar’s Exclusion Problem

The government’s current bet is that AI-driven face authentication — rather than fingerprint or iris scanning, which struggle with a manual labourer’s worn fingerprints or an elderly person’s cataracts — will close that 6.5% failure gap. 

It’s already been tested at real scale with UIDAI ran a face-authentication proof of concept at NEET-UG 2025 exam centres with the NTA and NIC, and by 2026 similar AI-camera verification, backed by liveness checks and a fingerprint or manual fallback, was standard at UPSC exam halls. Officials describe the results as promising. 

Researchers who’ve actually gone door to door are less convinced: a survey across 32 villages in Jharkhand by economist Jean Drèze and co-authors found exclusion errors running as high as 20% in areas where biometric authentication was required for every ration purchase — and critics note that swapping fingerprints for face scans doesn’t remove the underlying design flaw, which is that a single biometric check, controlled by a ration dealer or bank teller rather than the beneficiary, decides whether someone eats that month. 

There’s a second, quieter concern sitting alongside is the more AI systems sit on top of Aadhaar-linked data — UPI payments, SIM registrations, app logins — the easier it becomes to assemble a detailed behavioural profile of someone, usually described publicly as fraud prevention rather than surveillance. Both things can be true at once. 

AI-based face authentication may genuinely cut into the 20-million-a-month failure count, and the same infrastructure may quietly expand what the state and private platforms can see about a person’s life. That tension, not a clean technical fix, is the actual story here.

Agents That Could Soon Shop and Transact for You

The newest layer is barely a layer yet. ONDC, India’s government-backed alternative to Amazon and Flipkart, runs on the open-source Beckn protocol, which had onboarded more than 900 network participants across grocery, food delivery, mobility, and financial services by 2026. 

FIDE, the nonprofit behind Beckn, has already demonstrated BecknGPT — an experimental agent that lets a ChatGPT-style assistant browse and complete an ONDC purchase on a shopper’s behalf and mainstream apps including Swiggy, BigBasket, and Flipkart have started exposing their catalogues directly to AI shopping assistants. 

It’s genuinely early, more demo than daily habit right now. But the direction matters: if UPI proved India could build a public payments rail that private apps compete on top of, ONDC plus AI agents is the government’s bet that the same model can work for commerce itself, without any single platform owning discovery.

Read More 👉 Bihar STET 2026 Online Form Out: Check Exam Syllabus and Pattern To Get Teacher Job

Why Other Countries Are Copying India’s Homework

Whatever India’s Digital Public Infrastructure domestic wrinkles, India has turned it into one of its more effective diplomatic exports. 

During its 2023 G20 presidency, India pushed Digital Public Infrastructure as a global development model, the framework receiving endorsement from 20 member nations. By 2026, the cooperation agreements between India and other 23—24 countries have been signed for helping them build their own version of Aadhaar, UPI, or DigiLocker by sharing open-source blueprints rather than selling a finished product. 


UPI itself is already live in eight-plus countries, from the UAE and Singapore to France and Mauritius, and Kenya is reportedly building a national digital-identity stack directly modelled on India’s approach. 

Analysts who track this call it the “Aadhaar Paradox”: India is exporting a model with real, unresolved problems at home — the exclusion numbers above, heavy market concentration in UPI apps, ongoing data-protection debates — alongside genuine, population-scale successes that few other countries have managed. 

Both halves of that sentence are true, and any AI layer India bolts onto its own DPI will likely travel abroad along with everything else.

What Determines Changing India’s Digital Public Infrastructure With AI Goes Well

A few concrete things to watch over the next year, rather than general optimism about AI transforming governance. 

First, whether NPCI’s 30% market-share cap for individual UPI apps — currently set to take effect December 31, 2026 — actually holds this time, since two apps still control more than 80% of transaction volume and AI-driven credit and voice features could widen that gap further or finally give smaller players something to compete on. 

Second, whether UIDAI’s AI-based face authentication measurably moves the 6.5% Aadhaar failure rate in its next couple of annual disclosures, or whether as analyzer expect — it just changes which biometric ends up failing people. 

None of these are settled yet. Both will tell you, faster than any government press release, whether AI made India’s Digital Public Infrastructure more inclusive, or just faster at doing the same thing to the same people.

Read More 👉 NBEMS NEET PG Answer Key 2026: How To Download & Calculate Your Score

Conclusion 

AI could make India’s Digital Public Infrastructure faster, more accessible, and better at handling problems that humans simply cannot manage at this scale. From spotting fraud across UPI transactions to helping lenders understand small businesses and breaking language barriers, the benefits are already becoming visible. 

But the bigger question isn’t whether AI can make India’s Digital Public Infrastructure more efficient. It’s whether it can make it more inclusive without creating new problems along the way. Aadhaar’s authentication failures, concerns around data profiling, and the risk of AI-powered systems becoming harder to challenge show why speed alone isn’t enough.

India has already built the digital rails. The next phase is about deciding how intelligently, transparently, and fairly AI runs on top of them. The success of that shift will depend not just on better models, but on whether the people using these systems actually have fewer barriers when they need them most.

Leave a Comment

Your email address will not be published. Required fields are marked *

Bihar STET 2026 Online Form Out: Check Exam Syllabus and Pattern To Get Teacher Job

Bihar STET

Bihar STET 2026 Online Form Out on August 17 2026 and the last date to fill that form is September 15, 2026. Apply early to avoid last minute errors and server breaks, to score in Bihar State Eligibility Test (BSTET/STET 2026) examination, understand the exam syllabus and pattern.  

Download the official notification of Bihar STET 2026 to get all the details about eligibility, how to apply, and confirmed date for examination. While understanding the exam pattern which gets you selected.

Why Bihar STET 2026 Is Necessary For Teachers

Bihar STET — the Secondary Teacher Eligibility Test — isn’t a recruitment exam by itself. It’s a qualifying test conducted by BSEB that makes you eligible to apply for teaching posts in Bihar government-recognized schools, the same way BPSC TRE recruitment cycles have required in recent years. 

Clear it once, and BSEB now treats the certificate as valid for life rather than expiring after a few years, which is a meaningful change from the older TET/STET cycles where candidates had to keep re-qualifying. 

That’s the real reason so many people apply even when there’s no active teacher vacancy notification running at the same time — it’s a credential you bank for whichever recruitment drive comes next.

Bihar STET 2026 Important Dates

Save these dates into your calendar so don’t miss the day. Check updates on the official site every week for the exam date.

EventDate/Details
Notification released14/August/2026
Online application start17/August/2026
Original last date31/August/2026
Extended last date for application and fee payment15/September/2026
Official portalsThe dedicated application portal at stetregistration.cbrt.co.in
Exam DateThe exam date itself has not been officially announced. 

Eligibility Criteria for Paper 1 and Paper 2

The minimum age is 21 years as on August 1, 2026, confirmed consistently across the notification coverage. The upper limit is reported as 37 years for general candidates in some write-ups and as high as 42 for reserved and women candidates in others — since this figure hasn’t been consistent, check the age-relaxation table in the PDF notification itself before you rule yourself out.

Academic eligibility splits cleanly by paper:

  • Paper 1 (Secondary level, Classes 9–10): a Bachelor’s degree in the relevant subject with at least 50% marks, plus a B.Ed from an NCTE-recognized institution.
  • Paper 2 (Higher Secondary level, Classes 11–12): a Master’s degree in the relevant subject with at least 50% marks, plus a B.Ed.

Computer Science applicants are exempt from the mandatory B.Ed requirement if they meet the notification’s alternate qualification combinations, and the reduced qualifying marks, fee concessions, and age relaxations are only available to candidates with permanent Bihar domicile. 

Apply from outside the state, and you’re processed as a general-category male candidate regardless of your actual category — a detail that trips up a fair number of applicants from neighboring states every cycle.

Read More 👉 Your Dollar Income Isn’t Fixed: How INR Volatility Changes Freelancers Earning 

Bihar STET 2026 Online Form Fee Structure

The fee depends on category and on whether you’re applying for one paper or both:

  • General, BC, and EWS candidates: ₹960 for one paper, ₹1,440 for both
  • SC, ST, and PwD candidates: ₹760 for one paper, ₹1,140 for both

The fee is not refundable if you don’t pass the examination as this is the processing fee of your application.

Bihar STET 2026 Exam Pattern

Both papers follow the same structural pattern:

Exam ParticularsDetails
ModeComputer-Based Test (CBT)
Total questions150 multiple-choice questions
Total marks150 marks
Marks per question1 mark
Duration150 minutes (2 hours 30 minutes)
Negative markingNo negative marking

Of the 150 marks, 100 come from your chosen subject and the remaining 50 come from a section common to every candidate — Arts of Teaching and Other Competencies, covering General Knowledge, Reasoning Ability, Environmental Science, basic Mathematics, and Teaching Aptitude. 

Read More 👉 SSC CPO SI CAPF Online Form 2026

What To Study For Bihar STET Examination?

The subject-specific syllabus for Paper 1 broadly mirrors the graduate-level curriculum taught across Bihar’s universities. For Paper 2, it steps up to the graduate honours-level syllabus used for that subject in state universities — meaningfully deeper than Paper 1, which is worth remembering if you’re eyeing both papers back to back.

Your subject accounts for two-thirds of the total marks, so subject depth should be where most of your study hours go. But don’t write off the 50-mark common section as an afterthought — because most candidates do treat it as an afterthought, a candidate who actually revises General Knowledge, Reasoning, Environmental Science, and Teaching Aptitude systematically picks up an edge that’s disproportionate to how little competition they face there.

How to Apply for Bihar STET 2026

  1. Go to the official application portal of Bihar STET.
  2. Start a new registration and fill in basic details — name, mobile number, email.
  3. Verify your mobile number via OTP; a login ID and password get generated and sent to you.
  4. Log in and complete your personal and educational details in the application form.
  5. Upload a recent photograph, signature, and the required certificates.
  6. Pay the application fee online through the available payment modes.
  7. Submit the form and save or print the confirmation copy.

Several candidates in this cycle have reported that correction options after final submission are limited. Double-check your subject choice, category, and uploaded documents before you hit submit rather than assuming you can fix it afterward.

Selection Process and Certificate Validity

There’s no interview or separate merit round for STET itself — selection is based purely on your normalized CBT score against the qualifying threshold for your category. 

General category candidates need 50% to qualify; SC, ST, PwD, and women candidates need 40%. Once you clear that bar, BSEB issues a certificate that, under current policy, doesn’t expire — meaning you carry that eligibility forward into whichever Bihar teacher recruitment drive (including future BPSC TRE rounds) comes next, rather than needing to re-clear STET every cycle.

Read More 👉 Apple iPhone Duo Changes the Cost Effectively With These Methods

Conclusion

Bihar STET 2026 Online Form Out in August and now the deadline is coming, so you still have time to apply for the teacher eligibility test. Knowing the exam syllabus and pattern will help you get a high score and open many opportunities.

The one thing worth deciding today is whether you’re eligible for both papers — because qualifying for STET is separate from being recruited into a specific post, applying for both when you meet both qualification bars simply widens which recruitment drives you can walk into later without paying for and sitting through a second STET cycle. 

And since the exam date isn’t out yet, don’t waste energy hunting for a leaked schedule — put that time into the subject syllabus instead, since that’s the one variable in this entire process that’s already fully in your control.

Leave a Comment

Your email address will not be published. Required fields are marked *

Scroll to Top