SSC CPO SI CAPF Online Form 2026

SSC CPO SI CAPF

The SSC CPO SI CAPF Online Form 2026 finally went live on 10 September, now you can go on the official website to fill it. The official notification of SSC CPO brings fewer seats and a reshuffled exam pattern. The Staff Selection Commission has opened applications for CPO Sub-Inspector posts in Delhi Police and Central Armed Police Force (CAPF) Exam 2026.

The window runs from 10 September to 30 September 2026, 11 PM, and if past years are anything to go by, the SSC server tends to buckle in the last 48 hours. Registering early isn’t just good advice, it’s basic risk management.

DetailsInformation
Exam nameSSC Sub-Inspector in Delhi Police and CAPFs Examination 2026
Conducting bodyStaff Selection Commission
Total vacancies1,871
Application modeOnline
Online application begins10 September 2026
Last date to apply30 September 2026
Official websitessc.gov.in
Application fee₹100 for applicable candidates
Fee exemptionWomen, SC, ST and Ex-Servicemen candidates

Vacancies SSC CPO Are Numbered This Year

There are a total 1,871 vacancies for 2026 announced by SSC which is less in numbers from last year. Even after CISF’s new Fire wing added 234 posts to the count. Still it doesn’t beat last year’s vacancy count. 

SSC CPO SI male seats rose from 142 to 205 and SI female vacancies doubled from 70 to 112 this year. CAPF SI (GD) postings, which usually get higher in number, have shrunk considerably this year.

Sub-Inspector in CAPF seats for male are 1173 and 147 for females. So the total empty seats in CAPF are 1320.

Sub-Inspector (Fire) in CISF also vacant for 234 male candidates. The category-wise distribution of seats is also accessible from the official notification. The conclusion is general category male seats are more in numbers than other categories or females.

Eligibility For SSC CPO in 2026 

Education and Age Limit For SI: Any bachelor degree from a recognised university is accepted. Candidates’ age must lie between 20 to 25 years for Delhi Police SI and CAPF SI. The age relaxation is given for 3-years (OBC) and 5 years (SC/ST).

CISF SI (Fire) runs on a separate, wider band of 18 to 30 years, so if you’ve aged out of the general SSC CPO bracket, this is worth a second look.

Male applicants for Delhi Police SI (Executive) must hold a valid LMV driving licence — both motorcycle and car — on the day of the physical test, not on the day of application. If you don’t have one yet, start the process now; RTOs aren’t fast. 

Read More 👉 Your Dollar Income Isn’t Fixed: How INR Volatility Changes Freelancers Earning 

Physical Standards For SSC CPO SI Post 

Candidate categoryMale heightMale chestFemale height
General/OBC/SC/EWS170 cm80 cm unexpanded, 85 cm expanded157 cm
Candidates from specified hill areas, North-Eastern States and Sikkim165 cm80 cm unexpanded, 85 cm expanded155 cm
Scheduled Tribe candidates162.5 cm77 cm unexpanded, 82 cm expanded154 cm

Physical Endurance Test for SI Post

CandidateEventRequirement
Male100-metre race16 seconds
Male1.6-kilometre race6.5 minutes
MaleLong jump3.65 metres in 5 attempts
MaleHigh jump1.2 metres in 3 attempts
Female100-metre race18 seconds
Female800-metre race4 minutes
FemaleLong jump2.7 metres in 3 attempts
FemaleHigh jump0.9 metre in 3 attempts

What’s Changed in the SSC CPO SI CAPF Online Form 2026 Exam Pattern

SSC has restructured both papers for this cycle, and different question counts and marks splits for Paper I and Paper II. 

Paper I remains the general screening test covering Reasoning, General Awareness, Quantitative Aptitude, and English Comprehension, and Paper II is the English Language and Comprehension paper, with negative marking of 0.25 for wrong answers carried over from the previous pattern. 

For the exact number of questions and marks per section, go to the official notification PDF provided by the Staff Selection Commission.

How To Apply — SSC CPO SI CAPF Application Form

  1. Visit on the official website mentioned in the above overview.
  2. If you already have a One Time Registration (OTR) profile, log in and apply directly against the SSC SI in Delhi Police and CAPFs Examination, 2026 listing. 
  3. New applicants need to register first. 
  4. SSC is pushing Aadhaar-based authentication hard this cycle — opt into it, because it exempts you from photo and signature rejections on formatting grounds and saves you from carrying printed photo ID to the exam centre. 
  5. The photograph itself has to be captured live through the application at the time of registration; you can’t upload an old passport photo. 
  6. Signatures go in as a JPEG between 10 and 20 KB. 
  7. General, OBC, and EWS candidates pay a ₹100 application fee; women, SC/ST, PwBD, and ex-servicemen candidates are exempt, as usual.
  8. Once you’ve paid and submitted, use the preview option before final submission of SSC CPO SI CAPF online form— corrections later are limited to a fixed window (8 to 10 October, per current reporting) and won’t cover every field.

Salary of Sub-Inspector in Delhi Police and Central Armed Police Force

Salary is given under Pay Level 6 of the 7th Pay Commission, candidates who get selected for SI post going to earn up to ₹35,400 which rise up to ₹1,12,400. The total in-hand salary of a SSC CPO SI CAPF is somewhere between ₹55,000 and ₹75,000 a month by adding allowances.

The fixed salary of Sub-Inspector is shared with you after the selection depending upon the location of your post, as metro postings pull the number toward the higher end because of city-category HRA.

Read More👉 UP SuperTET Vacancy Notification 2026: Check Out Details, Dates, & Eligibility

Conclusion

Fill SSC CPO SI CAPF Online Form 2026 now to secure your seat because waiting for the last hour means you can make a mistake while filling the form in hurry or the site will crash down at the last minute and you’ll miss the chance.

So don’t take that risk and apply now for Sub-Inspector, prepare for the theory examination as well as physical standards. Check the eligibility and get your documents ready before going to fill the form.

Leave a Comment

Your email address will not be published. Required fields are marked *

How to Start a Mineral Water Business: Complete Guide

Mineral Water Business

Students who want to start a business while studying that will grow with time when they get passed out but don’t know how to start a mineral water business, stay consistent and understand everything step-by-step. Why the Mineral Water Business ? Because it’s easy and needs less investment so students can easily work it out.

In every area there’s someone on a bicycle, two or three 20-litre cans strapped to the back seat, making rounds before the 9 a.m. lecture. And you’re wondering about the cost per can, number of houses in the block, weekly demand and deciding to start a mineral water business. It sounds like the side income you’ve been looking for.

It’s not a bad instinct. Even if you don’t have six months of free time, and lakhs of rupees sitting idle. You can still set up your small business amid juggling a timetable, a hostel curfew, and exam weeks. Here’s what actually applies if you’re starting this while you’re still enrolled.

Mineral Water Business Is Different From Packaged Drinking Water

The label gets used loosely, and that’s where a lot of first-time entrepreneurs trip up. Under Indian standards, “natural mineral water” (IS 13428) and “packaged drinking water” (IS 14543) are two different categories. The natural mineral water is sourced from a protected mineral spring, while packaged drinking water is the RO-and-UV purified water in cans and bottles that almost every local plant actually sells. 

If you’ve ever seen a delivery guy with unbranded 20-litre cans, that’s packaged drinking water, not mineral water in the technical sense — even though everyone calls it “mineral water” on the street.

It matters because both categories legally require BIS certification if you’re selling them in a sealed, labelled container under a brand name. FSSAI registration is a separate, additional requirement that applies to anyone in the food and water supply chain — manufacturer, distributor, or reseller. 

Skipping either one isn’t a grey area; local FDA teams do seal unlicensed plants, and it happens more often than people expect. If you don’t have much money then you can apply for FSSAI certification to start with.

The Reality of Setting Up A Brand of Water

If the plan is to manufacture and bottle your own brand, here’s the honest range, based on current supplier and consultancy listings — treat these as ballpark figures and verify locally, since they shift by state, capacity, and vendor:

  • BIS/ISI certification facilitation through a consultant typically runs somewhere in the ₹35,000–₹70,000 range.
  • Entry-level packaged drinking water machinery (RO plant, filling, capping) starts around ₹2.4 lakh for lower-capacity units and climbs past ₹13 lakh for higher-capacity setups.
  • A full project — machinery, water-testing lab, premises — can land around ₹25 lakh once you include everything, which is roughly the scale seen in real project reports built for government-backed loans like PMEGP, financed mostly through a bank loan plus KVIC margin-money subsidy.

None of that is pocket money, and the setup timeline — BIS testing cycles, layout approval, machinery installation — usually runs months, not weeks. It’s a business for after you graduate, or for a family that already owns a plant.

Read More 👉 Best Noise-Cancelling Headphones for Online Classes and Mock Tests 

How to Start a Mineral Water Business While Studying

The workaround isn’t to skip compliance — it’s to skip manufacturing. Instead of building a plant, tie up with a local packaged drinking water plant that already holds FSSAI and BIS certification, and become their reseller or delivery partner in a specific area you can actually cover between classes.

You’ll still need your own FSSAI Basic Registration — it’s mandatory for anyone distributing or reselling food and water products, not just manufacturers, but it’s a low-cost, online process aimed at businesses with turnover under ₹12 lakh a year. No lab, no machinery, no factory inspection required at this tier.

However, you can’t put your own brand name on someone else’s water without their manufacturer backing you under their BIS license. Either sell openly under the supplier’s existing brand as their authorized reseller, or have a documented dealership arrangement. Your own labelled brand is the manufacturing route above — a later-stage move, not a starting point.

How to Manage Your Business While Attending Classes

A few things make the difference between this staying manageable and it eating your semester:

  • Keep the radius tight. Your own hostel block, one PG cluster, or a few shops near campus — something you can cover in under 15 minutes so it fits around lecture slots.
  • Vet suppliers in person. Visit two or three candidate plants, ask to physically see their FSSAI certificate and BIS license number rather than taking their word for it.
  • Apply for FSSAI Basic Registration early — it’s inexpensive and doesn’t take long, but it’s not something to leave until customers are already asking for it.
  • Run subscriptions, not daily orders. A weekly or monthly can subscription over WhatsApp is far easier to manage during exam weeks than fielding one-off orders every day.
  • Budget for the deposit cycle. Most local can systems run on a refundable can deposit — commonly in the ₹50–100 range per can, though this varies by supplier. That money is tied up as working capital until the empty can comes back, not profit you can spend.
  • GST registration only becomes mandatory once turnover crosses ₹40 lakh a year for goods in most states (lower in a few special-category states). Most student-run operations won’t hit that in year one.

Where Student Water Businesses Usually Fail

Three patterns show up repeatedly, and they’re worth naming before you start rather than after:

Treating it as passive income when it’s really a logistics job — someone has to physically move 20-kilogram cans at a fixed time, every week, including exam season. Letting the deposit-cash mismatch creep up — if thirty cans are out with customers and only ten deposits have come back, the working capital gap is real and it stalls reorders. 

And trying to compete on price against an established local operator who already owns the plant and the delivery network — a student reseller almost never wins that fight, and shouldn’t try. The actual pitch is convenience: reliable timing around class hours, UPI payment, water dropped right at the door. 

Read More 👉 Business Ideas for Students With Zero Investment — Easy Startup Guide

Where To Begin Your Mineral Water Business?

  • Skip the machinery quote for now. Call two local packaged drinking water plants and ask if they take resellers. 
  • Apply for your FSSAI Basic Registration online. 
  • Then run a 20-can pilot in your own hostel or nearby block before spending a rupee on anything beyond that. 
  • If the pilot survives one full exam cycle without a missed delivery, you’ll know whether this is a real business or just a good week.

Conclusion

Understanding how to Start a Mineral Water Business as a student is different from starting as a manufacturer. So don’t follow large-level business instruction points, begin with less investment and short area to cover. 

While attending your classes, you can set up your side business for passive income and it gets succeeded then you can turn it into a large-scale business. Apply FSSAI registration and track down your reliable provider who already has a water plant industry. Expand the network in the hostel and nearby block to easily deliver the mineral water cans.

Stay consistent and don’t get bored in just one week, keep up with the idea and you’ll get a success. 

Leave a Comment

Your email address will not be published. Required fields are marked *

Google Launches Fitbit Air in India: Features, Price and Availability

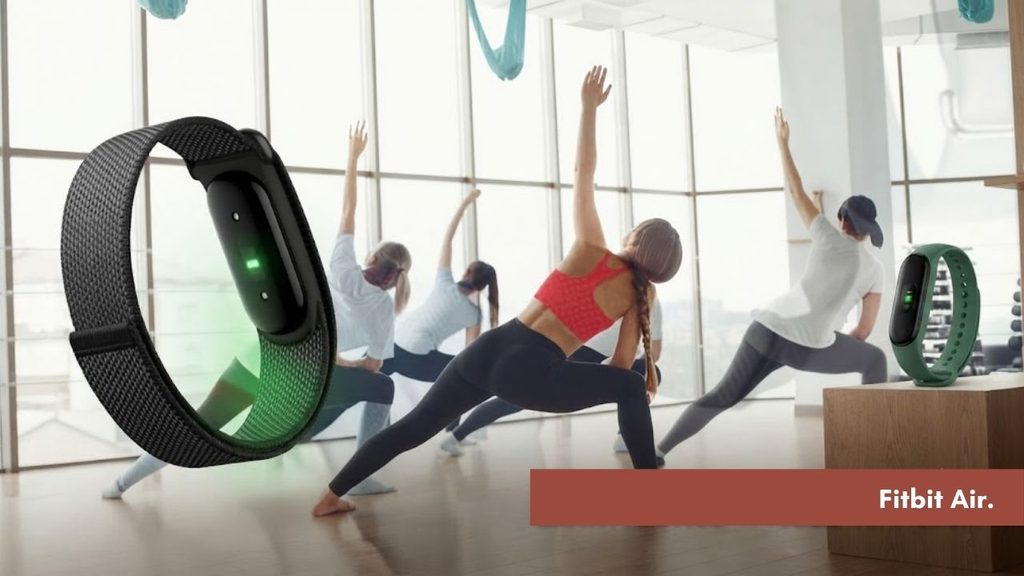
Fitbit Air

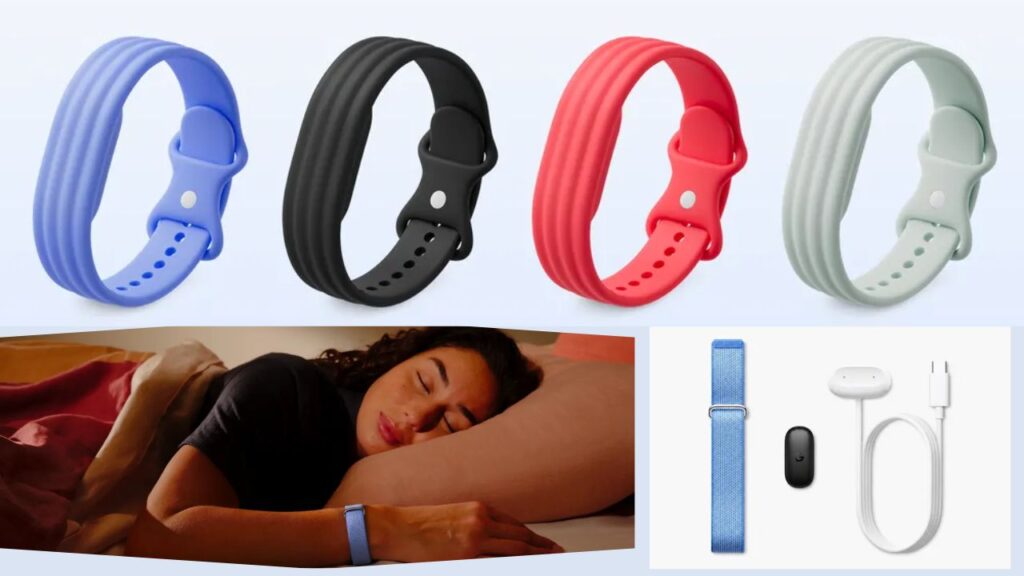
Picture a fitness tracker you forget you’re wearing. It has no screen to check mid-meeting and no buzz on your wrist at 2 a.m. That’s the idea behind the Fitbit Air. Google has now launched it in India at ₹13,999, with sales starting October 2. It’s the company’s smallest and lightest FitBit yet, and it arrives in a market where most people expect a wearable to have a display. 

The Fitbit Air isn’t a smartwatch. It’s a small sensor “pebble” that sits in a band and tracks your body in the background. Everything you want to read, like sleep scores, workout recaps and heart trends, lives in the Google Health app on your phone.

This isn’t a brand-new product. Google announced the Fitbit Air globally on May 7, 2026, with US shipping from May 26. India is getting it about four months later.

Fitbit Air Price in India And Launch Offers

The India price is ₹13,999 for all four colours. The box includes a three-month trial of Google Health Premium. That trial matters because it unlocks the Google Health Coach, the AI assistant Google built this tracker around.

For comparison, the US price is $99.99. Indian buyers will pay noticeably more than the US sticker price. On bank offers, buyers using eligible HDFC Bank and ICICI Bank cards get ₹1,000 cashback at launch, and it can be combined with six-month no-cost EMI. The exact terms may vary depending on the bank’s conditions.

Google Health Premium will cost is different in India after the trial ends. In the US, it runs $9.99 a month. Google hasn’t shared an Indian figure in the launch details, so check the Google Store listing before you buy.

More Helpful : Voice-to-Notes Tools for Students

What Fitbit Air Features Tracks And How Long It Lasts

Sensors

Google says the sensors cover 24/7 heart rate, heart rhythm monitoring with Afib alerts, SpO2, resting heart rate, heart rate variability, and sleep stages and duration. However, Google’s own footnote says the Afib feature is not available in all countries. So it is still unconfirmed whether it will be switched on in India at launch. If irregular-rhythm alerts are a deciding factor for you, verify this first.

Battery life is the other reliable feature 

Google claims up to a week per charge, and five minutes of fast charging gives you roughly a full day. Those numbers come from Google’s own pre-production testing, so real-world results may be lower.

Workout tracking is where the Google Health Coach comes in 

The Air detects common activities automatically, and you can also start a session from the app. With Premium, you can snap a photo of a cardio machine or a gym whiteboard routine and have it logged.

Hardware details from the global launch:

SpecFitbit Air
DisplayNone
WeightAbout 5 g for the pod alone, 12 g with a band
Water resistance50 metres 
BatteryUp to 7 days (Google’s claim)
Phone supportAndroid 11 or higher, iOS 16.4 or higher
Colours (India)Obsidian, Berry, Lavender, Fog

A reviewer at The5KRunner reported that the Air has no built-in GPS, so run distances will depend on your phone. 

Bands

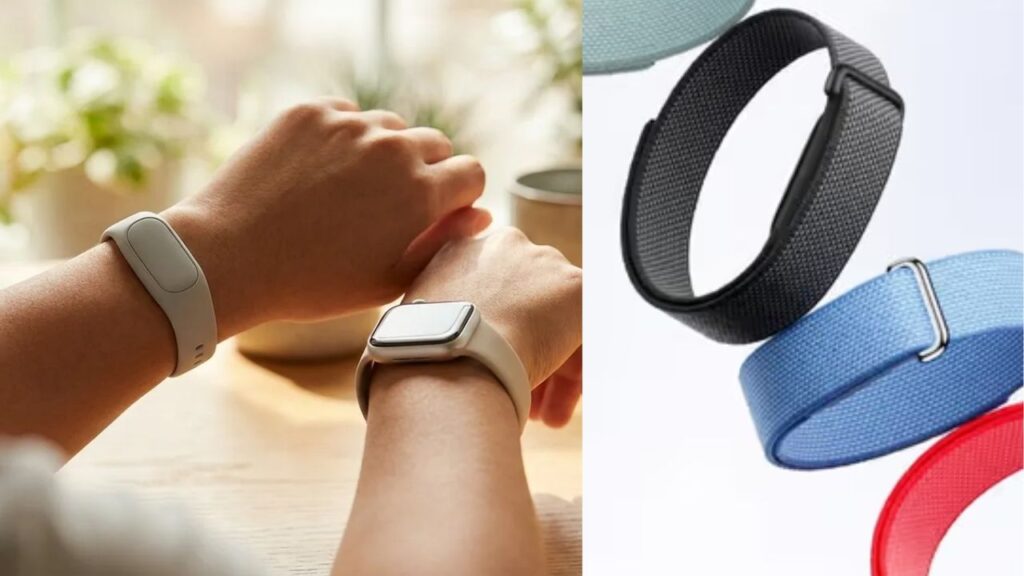
The pebble pops out, so you can swap bands. The Performance Loop, made from recycled materials, comes in the box. The sweatproof Active Band and the dressier Elevated Modern Band are sold separately. India pricing for those extra bands wasn’t available at the current time.

Fitbit Air Availability In India

The Fitbit Air goes on sale October 2 through the Google Store, Flipkart, Croma, Reliance Digital and Vijay Sales. That offline spread is a smart move for a product people may want to try on first. A screenless tracker is odd enough that holding one makes it easier to understand.

👉 Explore More: Apple iPhone Duo Cost-Effective Methods

Fitbit Air vs Whoop: How Does it Compare?

The obvious rival is Whoop, which pioneered the screenless band. The 5.0 is bulkier, at about 27 g with its band, and rated for 10 metres of water resistance. The bigger difference is the business model. 

Whoop requires a membership starting at $199 a year, while the Fitbit Air’s core tracking works without a required subscription. WHOOP’s current India pricing and availability weren’t clear, so the comparison below uses US pricing only. 

Beyond that, the Fitbit Air competes with cheaper straps like the Amazfit Helio Strap and with Fitbit’s own older display trackers. Those give you a screen for similar money. If you want to glance at the time or your heart rate mid-run, a screenless band is a step backward.

Conclusion

You can buy a Fitbit Air if sleep and recovery data matter more to you than notifications, you already like the Google ecosystem. If you’ve been curious about Whoop but dislike paying a yearly fee. Then it makes you confused, what you need matters most. The Fitbit Air is more comfortable to use around 24/7. A 12 g band is easier to wear to bed than a smartwatch.

Skip it if you want on-wrist GPS, quick glances at stats, or music and payments. Also hold off if the Premium price after the three-month trial is unclear to you, since the Coach is the main reason to choose this over cheaper trackers.

Wait for the October 2 listings, check the final Premium pricing and bank-offer terms, and compare against any display tracker you’re considering at ₹13,999. Then decide which one you can need.

Leave a Comment

Your email address will not be published. Required fields are marked *

Best App To Get Instant Loan Without Salary Slip 

Best App To Get Instant Loan Without Salary Slip

Your landlord isn’t waiting, the hospital isn’t waiting, and your bank’s personal loan officer just told you to come back “once you have three months of payslips.” That forces you to google for the Best App To Get Instant Loan Without Salary Slip because you need ₹20,000 urgently. Because there is no payslip coming from a freelancer, or small start ups owner.

This is the exact gap that a new generation of lending apps was built to close. Instead of a salary slip, they read your bank statements, your PAN and Aadhaar history, your UPI transaction pattern, and sometimes your GST filings, and turn that into a credit decision in minutes. 

However, “no salary slip” doesn’t mean “no scrutiny” and it definitely doesn’t mean every app claiming this is safe to use. Below are the Best App To Get Instant Loan Without Salary Slip, let’s see what they actually cost, and how to tell a legitimate lender from a data-harvesting clone before you hand over your Aadhaar.

Why Salary Slips Stopped Being the Only Option

Banks built their lending rules around one kind of borrower: someone with a fixed monthly salary landing on the same date, from the same employer, verifiable on a letterhead. That description fits a shrinking share of India’s workforce. Freelancers, gig-platform workers, small traders, and contract staff earn real, trackable income — it just doesn’t arrive in payslip form.

Digital lenders solved this by switching the input. Instead of a payslip, they pull 3–12 months of bank statements to see how much money moves through your account and how consistently. Self-employed applicants can usually substitute ITR filings, GST returns, or business account statements. 

Some apps go further and factor in your digital footprint — how long you’ve held your phone number, your UPI activity, even your app usage patterns to build a risk score. None of this is charity; it’s just a different, faster underwriting model, and it’s why approval on these apps can take minutes instead of the two-week wait typical of a bank.

Skipping The Salary Slip Doesn’t Mean The Requirement of Documents Ends

Skipping the salary slip doesn’t mean skipping documentation — it just shifts what counts as proof. Across the apps below, the standard ask is a PAN card, Aadhaar for e-KYC, and 3–6 months of bank statements showing regular inflows. 

Self-employed applicants typically add one of: ITR filings for the last one or two years, GST returns if registered, or a business current-account statement. A few apps, like Fibe and mPokket, lean more heavily on alternative signals — how long you’ve had your phone number, your UPI transaction frequency, even basic device data — specifically for applicants who have no ITR or GST paperwork to show at all. 

None of this is optional paperwork replaced by “trust us” — every legitimate lender still needs some way to estimate whether you can repay, it’s just reading your cash flow instead of your employer’s letterhead.

Best Instant Loan Apps Without a Salary Slip Are Listed

1. KreditBee — Best for Small, Fast Loans With No CIBIL History

KreditBee lends through Krazybee Services, an RBI-registered NBFC, and is built for speed on smaller ticket sizes. Loan amounts run from about ₹5,000 up to ₹10 lakh, with tenures between 3 and 60 months. 

Interest rates officially start at 12% p.a., but that floor is reserved for the strongest profiles — most first-time or thin-file borrowers land closer to 24–29.95% p.a., and self-employed applicants specifically are often quoted in the 16–29.95% range. 

Processing fees can run up to roughly 4–5% of the loan amount, deducted upfront from disbursal. The minimum income requirement is just ₹10,000 a month, and a CIBIL score isn’t mandatory. 

Best for: someone who needs ₹10,000–₹50,000 fast and doesn’t have a credit history yet — not for large-ticket borrowing, since the cost climbs fast at that end.

2. Navi — Best for Lower Rates and Larger Loan Amounts

Navi, backed by Navi Finserv, is an app to check if your credit score is solid and you need more money for longer. Loan amounts stretch from around ₹10,000 to ₹20 lakh (some listings show up to ₹10 lakh depending on the product), with tenures up to 84 months. 

Rates start near 9.9–9.99% p.a. for borrowers with a CIBIL score of 700+, but can rise to 29–45% p.a. for weaker profiles — a wider spread than most competitors, so the advertised low rate isn’t guaranteed. 

Processing fees range from 0% to about 4% plus GST. Both salaried and self-employed applicants are eligible with a minimum score of roughly 650. 

Best for: self-employed borrowers with a decent credit file who want a bigger loan without a bank’s paperwork.

3. Fibe (formerly EarlySalary) — Best for Speed

Fibe is an RBI-registered NBFC-P2P platform (license N-13.02139) built around a two-minute approval promise, using an AI model that scans over 100 data points instead of a payslip. Loan amounts go up to ₹5 lakh, rates start at 12% p.a., and it’s known for letting borrowers with no CIBIL score qualify by leaning on digital and social-footprint signals instead. It’s particularly active in Tier-2 and Tier-3 cities where bank branches and traditional documentation checks are less accessible. 

Best for: first-time borrowers who need money today and can accept a higher rate in exchange for near-instant disbursal.

4. PaySense — Best for Consistent Self-Employed Income

PaySense, run on PayU Finance India’s lending infrastructure, uses risk-based pricing rather than one flat rate, so two applicants for the same amount can get different offers. Published eligibility asks for a minimum monthly income of ₹18,000 for salaried applicants and ₹20,000 for self-employed ones, with interest rates typically quoted between 14% and 36% p.a. depending on profile. It accepts a low or even zero CIBIL score, which makes it accessible, but that flexibility shows up in the rate you’re offered. 

PaySense is the Best App To Get Instant Loan Without Salary Slip for self-employed borrowers with steady, provable cash flow who don’t yet have a strong credit file.

5. MoneyView — Best for Tier-2/Tier-3 Self-Employed Borrowers

MoneyView is frequently the first recommendation for salaried applicants outside metro cities and for self-employed or gig workers who want minimal paperwork. It’s positioned between the small-ticket apps and the larger NBFC lenders, with loan amounts up to around ₹10 lakh and rates generally in the low-to-mid double digits for stronger profiles, rising for thinner files — broadly comparable to KreditBee’s range, though it’s often described as steadier on collection practices in user reviews. 

Best for: borrowers outside major metros who want a mid-sized loan without a Tier-1-city credit profile.

6. mPokket — Best for Students and Thin-File Gig Workers

mPokket is built specifically for people the traditional system ignores entirely — students and gig workers with little or no credit history. Loan sizes are smaller than the others on this list, aimed at short-term, small-amount needs like covering a bill or a temporary cash gap rather than a big-ticket expense. It shouldn’t be treated as a recurring source of funds — the sizes and terms make it best suited to occasional, short-duration borrowing. 

Best for: students or new-to-credit gig workers who need a small amount and have nowhere else to turn.

Read More 👉 How to Start a Mineral Water Business: Complete Guide

How To Get an Instant Personal Loan Through Paytm, PhonePe, GPay, and Bhim

The same apps you use to split a dinner bill or pay your electricity bill can also get you a loan — often within minutes. Here’s how each one actually works:

Paytm

Open the Paytm app, head to the “Loans & Credit Cards” section, and tap “Personal Loan.” Paytm lets you apply anytime for an instant loan online in about two minutes, with a fully digital process and loan amounts ranging from ₹5,000 to ₹15 lakh, flexible tenure, and the option to foreclose anytime. 

Paytm doesn’t lend the money itself — it partners with RBI-regulated NBFCs and banks who actually underwrite and disburse the loan. You’ll go through PAN and Aadhaar-based KYC either way.

PhonePe

Same idea, different app. PhonePe doesn’t hand out loans directly — it has partnered with various banks and NBFCs to offer instant loans, so you can apply without ever leaving the app.  Loan amounts go up to ₹5 lakh, repayable over tenures of up to 60 months, at rates starting around 13% per annum, with the approved amount transferred straight to your bank account.  Most lenders here look for a stable income and a credit score around 650 or higher.

Google Pay

Google Pay follows the same partner-lending model as Paytm and PhonePe — it doesn’t lend directly but connects you to its NBFC and bank partners for a pre-approved or application-based personal loan inside the app, with KYC handled digitally via Aadhaar and PAN.

BHIM

This one surprises people, since BHIM is best known as NPCI’s bare-bones UPI app. But it’s expanded: BHIM now lets you explore a personal loan without leaving the app, again through its network of lending partners rather than lending in-house.

How to Check an App Isn’t a Scam Before You Apply

RBI does not license individual apps — it regulates the bank or NBFC behind them. That distinction is the entire safety check:

  • Find the named NBFC or bank. A legitimate app discloses its lending partner clearly in the app, on the Play Store listing, or in the loan agreement. If you can’t find a specific company name, stop.
  • Verify that name on rbi.org.in or the RBI’s Digital Lending Apps directory before you submit any documents.
  • Never pay upfront. Processing fees, “insurance,” or “security deposits” requested before disbursal are the single most common fraud pattern. Legitimate lenders deduct fees from the loan amount after approval, not before.
  • Check what permissions it wants. A real KYC process needs your camera for a selfie and basic identity/banking access — not your full contact list, photo gallery, SMS logs, or call history. Apps that demand those are usually building leverage for harassment-based recovery later, not assessing creditworthiness.
  • Look for a Key Fact Statement (KFS). RBI’s digital lending rules require one before disbursal, listing the all-in APR, not just a headline interest rate. A “1% per month” rate can look harmless until the APR reveals fees stacked on top.
  • Confirm a named grievance officer with a phone number and email — not just a generic contact form.

If two or more of these are missing, treat the app as a red flag regardless of its Play Store rating, which is not proof of regulatory legitimacy. Because the best app to get instant loan doesn’t mean every app is trustworthy.

Advertising Rate Is Always Different From Actual Amount You Receive in Your Account

Headline interest rates on these apps are quoted per annum, but the real cost shows up in the APR, once processing fees and GST on those fees are added in. A concrete example: on a KreditBee loan disbursed at roughly ₹1 lakh, one published breakdown shows a ₹4,000 processing fee (4%), ₹720 GST on that fee, and ₹10 in documentation charges — pushing the effective APR to 29.66%, even though the headline rate for that borrower’s tier read lower. 

The amount that actually lands in the bank account was around ₹95,270, not the full ₹1 lakh. This is exactly what the Key Fact Statement is meant to expose, and it’s why comparing apps on their advertised “starting from” rate alone is close to useless — always ask for the APR and the net disbursal amount before accepting an offer, not just the interest rate.

Read More 👉 How to Apply for an Education Loan Online

Which App Should You Consider For Instant Personal Loan?

  • If you’re a gig worker or freelancer with no credit history and need a small amount fast, start with KreditBee or Fibe. 
  • If you’re self-employed with steady bank statements and want a lower rate on a bigger amount, check Navi or MoneyView first and let your CIBIL score decide between them. 
  • If you’re a student or new to credit entirely, mPokket is built for exactly that gap, but treat it as a short-term bridge, not a repeat solution. 

Conclusion

Whichever  Best App To Get Instant Loan Without Salary Slip you land on, run it through the RBI-verification checklist above before you type in your PAN — that two-minute check is what separates a fair loan from a very expensive mistake.

The absence of a salary slip requirement is a documentation shortcut, not a signal that the loan is free of risk. A ₹20,000 loan at 28% p.a. with a 4% upfront fee still needs to be repaid on schedule, and missed EMIs on these apps report to CIBIL just like a bank loan would. 

Borrow the amount you need for the problem in front of you, not the maximum the app is willing to approve — the higher your sanctioned limit looks, the more tempting it is to take more than the situation actually calls for.

Note: Rates, loan limits, and fees above reflect published figures as of mid-2026 and change frequently based on lender policy and individual credit profile — confirm current terms in-app before applying.
Leave a Comment

Your email address will not be published. Required fields are marked *

Best Lightweight Sunglasses for Student Life 

Sunglasses

A pair of sunglasses in a college backpack is a choice of your comfort. When the college campus is large and you need to walk in direct sunheat or you go out randomly somewhere with your friends and your eyes start to burn in the heat. That’s where you start hunting for Best Lightweight Sunglasses for students, the best is the one which gives you comfort, weightless, and perfect for your face.

What Actually Matters for Campus-Ready Sunglasses

Frame weight comes down to material, not brand name. TR-90 and polycarbonate frames flex instead of snapping when they get crushed in a bag, and they sit lighter on the nose during a three-hour library stretch than metal or thick acetate does. UV protection — specifically UV400 — isn’t optional no matter how cheap the pair is; it’s the one spec that protects your eyes rather than your outfit. 

Polarization is worth paying a little more for if you’re on a bike or scooter daily, since it cuts glare off wet roads and car windshields far better than plain tinted lenses. And because these things get lost, borrowed by roommates, or sat on at least once a year, price-to-replacement-cost matters more here than it would for a pair you’d baby at home.

The 5 Best Lightweight Sunglasses for Students 

1. Fastrack Polarized Wayfarers and Aviators

Price: ₹950–₹5,000 | Frame: TR-90 polycarbonate | Lens: UV400, polarized options | Best for: tightest-budget daily wear


Fastrack’s entry-level polarized range starts under ₹1,000 and still comes with a 1-year warranty on lenses and frames, which is unusual at that price point. The TR-90 build is genuinely flexible — it survives the kind of backpack abuse a rigid acetate frame won’t. The trade-off is build quality at the very bottom of that price range: some buyers report the cheapest models feeling plasticky compared to what ₹2,000+ gets you in the same lineup. Good for someone who wants a backup pair as much as a main one.

2. Vincent Chase by Lenskart

Price: From ₹999, polarized from ₹1,299 | Frame: TR90 | Lens: 100% UV protected, polarized | Best for: best value-for-money on a first “real” pair


Vincent Chase is Lenskart’s in-house line, and it’s built around the same TR90 material for the same reason — daily wear without weight. The advantage over Fastrack is availability: Lenskart runs frequent Buy 1 Get 1 offers on this line, which effectively gets you a backup pair for the price of one. The catch is that heavy discounting means style availability shifts often, so a specific frame you like online today may not be there in three months if you need a replacement in the exact same shape.

3. OPIUM Eyewear

Price: ₹1,500–₹5,000 | Frame: lightweight polycarbonate | Lens: UV400, polarized, AVS coating | Best for: students who scratch or drop glasses often


OPIUM’s AVS lens coating adds hydrophobic, oleophobic, and anti-static properties on top of standard UV/polarized protection — practically, that means fewer smudges from fingerprints and better scratch resistance when the lenses rub against keys or coins loose in a bag. It sits a notch above Fastrack and Vincent Chase in price, which is the real trade-off: you’re paying for lens durability, not a jump in style tier.

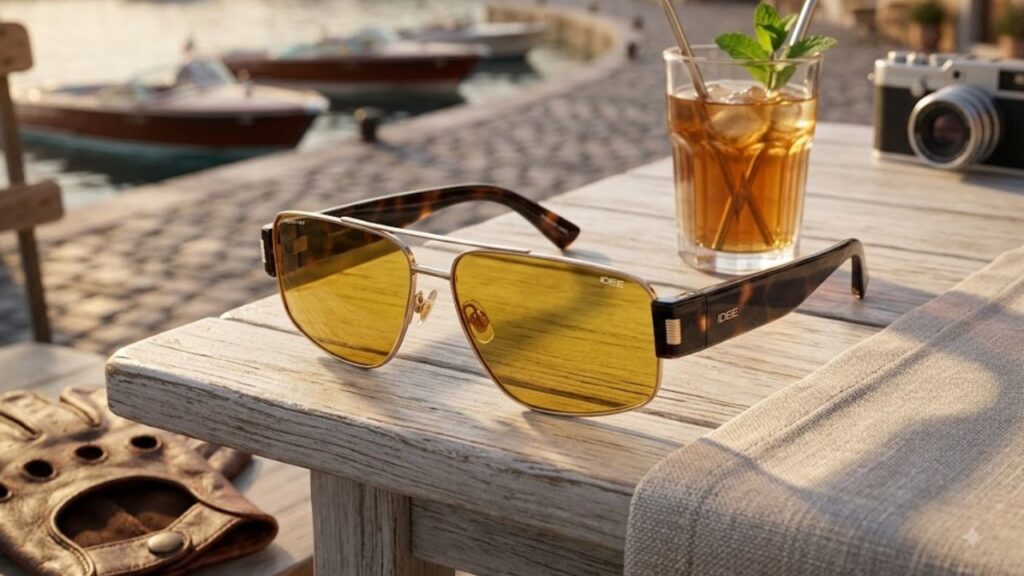
4. IDEE

Price: ₹899–₹1,499 | Frame: lightweight, sporty builds | Lens: UV protected | Best for: gym, sports, or an active daily commute


IDEE leans into bold, sporty designs — wraparounds and neon accents rather than classic wayfarer shapes — and stays cheap while doing it. If your daily routine includes a run, a cycle to campus, or intramural sports, the closer-wrap fit holds better than a flat wayfarer frame. The limitation is versatility: the sportier shapes don’t double as well for a formal event or an internship interview the way a classic frame does.

5. Ray-Ban (Aviator / Wayfarer)

Price: roughly ₹7,000–₹15,000 depending on style and retailer | Frame: acetate/metal | Lens: UV400, optional polarized | Best for: one pair meant to last through all four years

Ray-Ban is the outlier on this list by price, and it’s here for a specific reason: it’s the one pair that isn’t disposable. The Original Wayfarer and Aviator have been in continuous production since 1952 and 1937 respectively, which means replacement parts, nose pads, and repairs are easy to find at any optician years later — something none of the budget brands above can promise. It only makes sense if you can absorb the upfront cost and genuinely won’t be swapping styles every semester.

The Real Face-Off of Fastrack & Vincent Chase 

These two get compared constantly because they’re the two brands most students actually cross-shop, so here’s the direct read:

FastrackVincent Chase
Entry price₹950₹999
Polarized entry priceIncluded in mid-rangeFrom ₹1,299
Warranty1 year (lens + frame)Standard return window, no stated 1-yr warranty
Where to buyFastrack’s own site, Titan Eye+, Flipkart, Tata CLiQLenskart, Amazon.in
Recurring offersOccasional salesFrequent Buy 1 Get 1

If warranty coverage matters more to you than getting two pairs, Fastrack wins. If you’d rather have a spare pair sitting in a drawer for when the first one inevitably gets sat on, Vincent Chase’s BOGO structure is hard to beat on pure economics.

Which One Should You Actually Buy?

If your budget is genuinely under ₹1,200 and you just need something functional for the sun on your walk to class, get the Fastrack or Vincent Chase entry model — there’s no meaningful difference in daily performance between them at that price. If you’re riding a two-wheeler daily, prioritize a polarized lens over anything else on this list; glare off a windshield or wet road is a real safety issue, not just comfort. 

If you’re the person who’s cracked three pairs of earphones and lost two water bottles this year, don’t buy OPIUM or Ray-Ban — buy the cheapest polarized Fastrack you can find and expect to replace it. And if you’ve got one splurge in your accessory budget for the year and want something that’ll still be wearable at your graduation photos, the Ray-Ban is the only pair on this list built to actually last that long.

One habit that extends your sunglasses lifespan –  a hard case, not the soft pouch that comes in the box. Most lens scratches on student sunglasses don’t happen while wearing them, they happen loose in a bag next to keys and a laptop charger.

Read More👉 iPhone 18 Pro on EMI: A Complete Buying Guide

Conclusion

The Best Lightweight Sunglasses for Everyday Student Life aren’t always expensive. Whatever you opt for, be sure to focus on UV400 protection, a lightweight frame, a comfortable fit, and polarization for when glare is an issue. Toss a hard case In Addition your backpack, and even a modest pair can make it through life on the daily grind of college. Pocket your case for your backpack and even a thrifty pair can easily keep up with daily college life. 

Leave a Comment

Your email address will not be published. Required fields are marked *

UP Anganwadi Bharti 2026 — District-Wise Vacancies & Recruitment Details

UP Anganwadi Bharti 2026

UP Anganwadi Bharti 2026 recruitment is live and you can apply if the application portal is still live in your district. There’s no one deadline for the recruitment drive because it has a lot of separate district-level drives. It offers various posts such as Karyakatri and Sahayika, so these are open for females only.

First, understand the structure, eligibility, and selection process for UP Anganwadi Bharti then apply with all the required documents.

ParameterDetails
Recruitment NameUP Anganwadi Bharti 2026 (ICDS, Uttar Pradesh) 
Conducting AuthorityDistrict Programme Officer (DPO), Bal Vikas Seva evam Pushtahar Vibhag, UP 
Department / SchemeIntegrated Child Development Services (ICDS), Women & Child Development, UP 
Posts OfferedAnganwadi Worker (Karyakartri), Mini Worker, Anganwadi Helper / Sahayika 
Total Vacancies (Indicative)~60,000–61,600+ posts 
Eligibility Only female candidates, 10th / 12th pass
Residency ConditionCandidate must be resident of the same village/ward of the Anganwadi centre for which she applies
Application FeeNo fee for any category (General/OBC/EWS/SC/ST) 
Notification & Application WindowMain notification from Nov 2025; applications open/close district-wise through early–mid 2026 
Salary (Indicative)Around ₹5,500 – ₹12,000 per month 
Official WebsiteClick Here

Structure of UP Anganwadi Bharti 2026 — District by District

The notification is out from each district for the recruitment under the state government which directed the Department of Women and Child Development, to fill vacant Anganwadi Karyakatri (Worker) and Anganwadi Sahayika (Helper) posts across Uttar Pradesh. Instead of one recruitment drive, each District Programme Officer releases and manages notification and recruitment for their district at different times.

DistrictPostsLast date to apply
Jhansi223 (across 9 CDPOs)7 /September /2026
Maharajganj3051 /September /2026
Chitrakoot92 (23 Karyakatri + 69 Sahayika)5 /September /2026
HamirpurActive16/September/ 2026
BalrampurActive23 /September /2026
Amroha (J.P. Nagar)105 (across 7 projects)24 /September /2026

Earlier in the year, Bagpat and Kannauj ran their own window for 760 combined posts, applying from 25 June to 16 July 2026 — that cycle is closed, and candidates there are now waiting on the merit list.

Who Can Apply For UP Anganwadi Post

A few conditions hold across nearly every district notification:

  • Only female candidates are eligible — there’s no male category in this recruitment. 
  • Female candidates should be between 18 and 45 years, calculated as on 1 July 2025. Relaxation given only reserved category.
  • Anganwadi Karyakatri posts sometimes require an Intermediate marksheet, depending on the district rules. 
  • Helper (Sahayika) posts have historically carried a lower bar in some districts, occasionally as low as 8th pass.

The condition that trips up the most applicants isn’t age or education — it’s domicile. You can’t apply to whichever district has the most vacancies. Each post is tied to a specific ward (in urban areas) or gram/nyaya panchayat (in rural areas), and you must be a permanent resident of that exact unit. A vacancy list in Jhansi is not open to a resident of Kanpur, even within the same state.

Read More 👉 UP SuperTET Vacancy Notification 2026: Check Out Details, Dates, & Eligibility

Vacancies Numbers Are Huge

The total vacancies are more than 60000 across the state. Open your district’s latest 2026 notification PDF to check the vacancy number.

DistrictPost TypeVacanciesKey Detail
FatehpurWorker + Helper389150 Worker + 239 Helper (Aug–Sept 2026)
BandaWorker122Last date 22 Sept 2026
HamirpurWorker80Last date 16 Sept 2026
UnnaoWorker336Last date 11 Aug 2026
GhaziabadHelper341Last date 07 Aug 2026
JhansiWorker (Karyakatri)223Across 9 projects; last date 07 Sept 2026
Kanpur NagarHelper (Sahayika)307Across 12 projects; last date 05 Sept 2026
KushinagarWorker245Project-wise split available
KushinagarHelper (Sahayika)214Separate Helper notification
MaharajganjWorker + Helper305164 Worker + 141 Helper
SonbhadraWorker201Project-wise vacancy table available
MuzaffarnagarWorker146Anganwadi Worker posts only
GhazipurHelper1,352Among larger Helper batches
BulandshahrWorker + Helper678Combined posts
BagpatHelper374Helper-only batch
AzamgarhHelper265Helper-only batch

Selection Process & Application Fee

There’s no written test and, in the vast majority of district notifications reviewed so far, no interview either. Selection is by merit list, built from your marks in 10th, 12th, and graduation, all being equal. There’s no application fee for any category, including SC, ST, PwBD, and general female candidates — this recruitment is free to apply for, full stop.

Salary Of UP Anganwadi Posts

A ₹10,000/month for Anganwadi Worker, ₹7,500 for Mini Worker, and ₹4,500 for Helper as honorarium (not salary — these are Anganwadi posts, not salaried government service, and the distinction affects things like PF and pension eligibility). 

Getting Your Application In Before Your Window Closes

Applications go through upanganwadibharti.in 

On the homepage, you’ll find a running list of “active” district notifications with their upload and closing dates; this list changes weekly as new districts come online and others close.

Fill your details correctly in the form and submit with all the necessary documents attached. There is no application fee, so apply early and correctly.

The real trap here is timing, not eligibility. Most district windows stay open for only two to four weeks from the upload date — Hamirpur’s notification, for example, went up on 27 August and closes 16 September, an 18-day window. 

Bookmark the official portal itself, and search for your specific ward or gram panchayat, not just your district name; that’s the actual unit your eligibility is judged against.

Documents Required To Apply

Gather your documents first before your district application portal goes live. The necessary documents are listed in the notification PDF but you can also catch it here:

  • Your education proof – any 10th, 12th, and graduation marksheets, 
  • Domicile certificate for resident confirmation, 
  • Caste certificate (if you belong to reserved category), 
  • Aadhaar/ PAN Card, and 
  • A recent passport size photograph 
  • Signature on the blank page

Get ready with all these documents before your ward’s notification even drops.

Read More 👉 Planning MBBS or Master’s Abroad? Country-Wise Costs, Loan Limits and Lenders

Conclusion

UP Anganwadi Bharti 2026 notification is out but recruitment is active in some districts and closed in few districts. If the recruitment is active in your region then apply now before it gets closed. The vacancy numbers are huge, more than 60,000 posts are vacant and these seats are only open for females. 

But you must be the resident of that village to apply, and the documents must be prepared including your adhaar, high school marksheet, domicile certificate etc. You can apply for free but check the notification before you apply for the Karyakatri and Sahayika position.

Leave a Comment

Your email address will not be published. Required fields are marked *

Scroll to Top