iPhone 18 Pro Launching Next Month: 12 New Features Worth Knowing About

iPhone 18 Pro

If you’ve been putting off a new iPhone purchase this month, that instinct is about to pay off. The iPhone 18 Pro launching next month means in September 2026, and unlike last year’s fairly incremental refresh, this generation brings changes that actually alter how the phone behaves day to day β€” not just how it looks in a colour catalogue. 

The iPhone 18 Pro comes up with twelve new features that keep resurfacing across leaks from potential sources, and enough of them line up with each other that the list is worth taking seriously, even months before Apple confirms anything on stage.

When Is the iPhone 18 Pro Launching in India?

Apple has not confirmed an exact date of launch but people are guessing according to the leaks of iPhone 18 Pro that it will launch on September 8 and other sources have cited a September 9 date, with sales starting around September 18. Either way, expect the announcement in the first half of September and phones on shelves roughly a week or two later β€” India has landed in Apple’s first launch wave for the last several cycles, so there’s no reason to expect a delay this time.

The bigger structural change is that Apple is reportedly splitting its iPhone 18 lineup across two events for the first time. Only the iPhone 18 Pro, iPhone 18 Pro Max, and Apple’s first foldable iPhone are expected this fall. The standard iPhone 18, a budget iPhone 18e, and a second-generation iPhone Air are said to be held back until around March 2027. If that holds, it’s a genuine break from Apple’s usual one-event calendar, not just a rumor footnote.

Read MoreπŸ‘‰ Best Student Laptops for School and University in 2026 

The iPhone 18 Pro Launching Next Month With New Features: 12 Upgrades Leaks 

1. A Smaller Dynamic Island

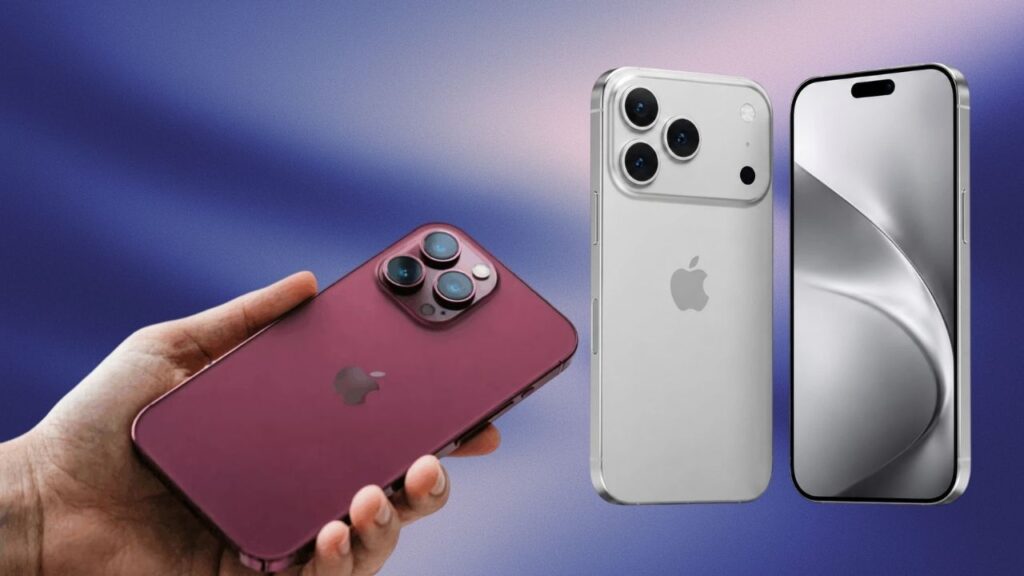
Apple’s Face ID flood illuminator is rumored to move under the display at the same time, allowing Apple to reduce the size of the pill-shaped cutout at the top of the display for the first time since its introduction. 

2. LTPO+ Displays

Screen sizes stay put at 6.3 inches and 6.9 inches, matching the iPhone 17 Pro line. What’s new is LTPO+ panel technology, which is expected to squeeze out extra battery life without changing the physical footprint.

3. Variable Aperture Camera

The 48-megapixel main camera is rumored to gain a variable aperture β€” a first for iPhone β€” giving more control over depth of field. Given how small phone camera sensors are compared to a real DSLR, how much this actually improves photos in practice is still an open question.

4. A20 Pro Chip on 2nm

This would be Apple’s first chip fabricated on TSMC’s 2nm node, up from the 3nm A19 Pro. There’s likely to be a huge jump in both performance and power efficiency, even if Apple hasn’t yet released any figures. 

5. Third-Generation C2 Modem

Apple’s in-house modem line continues past the C1 and C1X with a new C2 chip, expected to keep pushing speed and efficiency ahead of its predecessors.

6. 5G Connectivity via Satellite

Paired with the C2 modem, the iPhone 18 Pro is rumored to support satellite-based web browsing when there’s no Wi-Fi or cellular signal β€” useful well beyond emergency SOS messaging.

7. New N2 Wireless Chip

The chip that currently handles Wi-Fi, Bluetooth, and features like AirDrop and Personal Hotspot is due for an upgrade to N2. What specifically improves hasn’t leaked yet.

8. A New Dark Cherry Colourway

Reports consistently point to Dark Cherry replacing Cosmic Orange and Deep Blue as the standout shade, alongside Light Blue, Dark Gray, and Silver.

9. A Simplified Camera Control Button

Apple is expected to strip out touch sensitivity and haptic feedback from the Camera Control button, leaving a purely pressure-sensitive click β€” a response to complaints that the current button is fussy to use.

10. A Cleaner Rear Finish

The Ceramic Shield area around the MagSafe ring is rumored to move to a single frosted finish, replacing the two-tone look on current Pro models.

11. A Bigger Battery on the Pro Max

Alleged Chinese regulatory filings suggest the iPhone 18 Pro Max’s battery capacity could grow by close to 10% over the iPhone 17 Pro Max β€” a meaningful jump if it holds up.

12. A Thicker Pro Max Body

That extra battery could come with a price: the iPhone 18 Pro Max seems to be a bit thicker than the standard iPhone 18 Pro and last year’s Pro Max, according to leaks. 

iPhone 18 Pro Price in India: What to Expect

Still, no one outside Apple knows the real figure, so consider anything below as a pre-launch estimate and not a quote. Indian retailers trackers like Smartprix, Cashify and LatestLY are now pointing towards a base price of β‚Ή1,39,900 for the 256GB base model of the iPhone 18 Pro β€” which would be β‚Ή5,000 more than the iPhone 17 Pro started from. 

Some tech enthusiasts notes are less optimistic, citing rising costs for the 2nm chip and faster memory, with a few reports floating figures as high as β‚Ή1,43,990 to β‚Ή1,54,900 depending on storage tier and whether you’re looking at the standard Pro or Pro Max. The spread between these numbers is wide enough that none of them should be treated as settled until Apple confirms pricing at the keynote.

Should You Wait for the iPhone 18 Pro?

If you’re still on an iPhone 15 Pro or older, this generation is worth waiting for β€” the variable aperture camera and the A20 Pro’s efficiency gains are the kind of changes you’d actually notice in daily use, not just on a spec sheet. If you already own an iPhone 17 Pro, none of the 12 rumored changes look big enough on their own to justify an upgrade this cycle β€” the two most significant jumps, the larger battery and thicker body, apply mainly to the Pro Max. 

And if price is what’s holding you back either way, keep an eye on the iPhone 17 Pro once the new lineup launches β€” Apple typically keeps the outgoing Pro model on sale at a reduced price, and that discount is usually the better deal in late September than paying full price for year-one rumors that haven’t been battle-tested yet.

Read More πŸ‘‰ Top Lightweight Student Laptops to Buy in 2026

Conclusion 

The iPhone 18 Pro launching next month seems like a worthwhile upgrade in a nutshell, featuring a new A20 Pro chip, variable-aperture camera, smaller Dynamic Island, better connectivity, and bigger Pro Max battery. But keep in mind that all of the 12 features are still leaks until Apple officially unveils the phone. 

If you have an older iPhone, then holding out for the September release is a good idea. If you’re already an iPhone 17 Pro owner, there’s probably no need to hurry unless the camera improvements or Pro Max battery life are plenty of temptation. 

Leave a Comment

Your email address will not be published. Required fields are marked *

Best App To Get Instant Loan Without Salary SlipΒ 

Best App To Get Instant Loan Without Salary Slip

Your landlord isn’t waiting, the hospital isn’t waiting, and your bank’s personal loan officer just told you to come back “once you have three months of payslips.” That forces you to google for the Best App To Get Instant Loan Without Salary Slip because you need β‚Ή20,000 urgently. Because there is no payslip coming from a freelancer, or small start ups owner.

This is the exact gap that a new generation of lending apps was built to close. Instead of a salary slip, they read your bank statements, your PAN and Aadhaar history, your UPI transaction pattern, and sometimes your GST filings, and turn that into a credit decision in minutes. 

However, “no salary slip” doesn’t mean “no scrutiny” and it definitely doesn’t mean every app claiming this is safe to use. Below are the Best App To Get Instant Loan Without Salary Slip, let’s see what they actually cost, and how to tell a legitimate lender from a data-harvesting clone before you hand over your Aadhaar.

Why Salary Slips Stopped Being the Only Option

Banks built their lending rules around one kind of borrower: someone with a fixed monthly salary landing on the same date, from the same employer, verifiable on a letterhead. That description fits a shrinking share of India’s workforce. Freelancers, gig-platform workers, small traders, and contract staff earn real, trackable income β€” it just doesn’t arrive in payslip form.

Digital lenders solved this by switching the input. Instead of a payslip, they pull 3–12 months of bank statements to see how much money moves through your account and how consistently. Self-employed applicants can usually substitute ITR filings, GST returns, or business account statements. 

Some apps go further and factor in your digital footprint β€” how long you’ve held your phone number, your UPI activity, even your app usage patterns to build a risk score. None of this is charity; it’s just a different, faster underwriting model, and it’s why approval on these apps can take minutes instead of the two-week wait typical of a bank.

Skipping The Salary Slip Doesn’t Mean The Requirement of Documents Ends

Skipping the salary slip doesn’t mean skipping documentation β€” it just shifts what counts as proof. Across the apps below, the standard ask is a PAN card, Aadhaar for e-KYC, and 3–6 months of bank statements showing regular inflows

Self-employed applicants typically add one of: ITR filings for the last one or two years, GST returns if registered, or a business current-account statement. A few apps, like Fibe and mPokket, lean more heavily on alternative signals β€” how long you’ve had your phone number, your UPI transaction frequency, even basic device data β€” specifically for applicants who have no ITR or GST paperwork to show at all. 

None of this is optional paperwork replaced by “trust us” β€” every legitimate lender still needs some way to estimate whether you can repay, it’s just reading your cash flow instead of your employer’s letterhead.

Best Instant Loan Apps Without a Salary Slip Are Listed

1. KreditBee β€” Best for Small, Fast Loans With No CIBIL History

KreditBee lends through Krazybee Services, an RBI-registered NBFC, and is built for speed on smaller ticket sizes. Loan amounts run from about β‚Ή5,000 up to β‚Ή10 lakh, with tenures between 3 and 60 months. 

Interest rates officially start at 12% p.a., but that floor is reserved for the strongest profiles β€” most first-time or thin-file borrowers land closer to 24–29.95% p.a., and self-employed applicants specifically are often quoted in the 16–29.95% range. 

Processing fees can run up to roughly 4–5% of the loan amount, deducted upfront from disbursal. The minimum income requirement is just β‚Ή10,000 a month, and a CIBIL score isn’t mandatory. 

Best for: someone who needs β‚Ή10,000–₹50,000 fast and doesn’t have a credit history yet β€” not for large-ticket borrowing, since the cost climbs fast at that end.

2. Navi β€” Best for Lower Rates and Larger Loan Amounts

Navi, backed by Navi Finserv, is an app to check if your credit score is solid and you need more money for longer. Loan amounts stretch from around β‚Ή10,000 to β‚Ή20 lakh (some listings show up to β‚Ή10 lakh depending on the product), with tenures up to 84 months. 

Rates start near 9.9–9.99% p.a. for borrowers with a CIBIL score of 700+, but can rise to 29–45% p.a. for weaker profiles β€” a wider spread than most competitors, so the advertised low rate isn’t guaranteed. 

Processing fees range from 0% to about 4% plus GST. Both salaried and self-employed applicants are eligible with a minimum score of roughly 650. 

Best for: self-employed borrowers with a decent credit file who want a bigger loan without a bank’s paperwork.

3. Fibe (formerly EarlySalary) β€” Best for Speed

Fibe is an RBI-registered NBFC-P2P platform (license N-13.02139) built around a two-minute approval promise, using an AI model that scans over 100 data points instead of a payslip. Loan amounts go up to β‚Ή5 lakh, rates start at 12% p.a., and it’s known for letting borrowers with no CIBIL score qualify by leaning on digital and social-footprint signals instead. It’s particularly active in Tier-2 and Tier-3 cities where bank branches and traditional documentation checks are less accessible. 

Best for: first-time borrowers who need money today and can accept a higher rate in exchange for near-instant disbursal.

4. PaySense β€” Best for Consistent Self-Employed Income

PaySense, run on PayU Finance India’s lending infrastructure, uses risk-based pricing rather than one flat rate, so two applicants for the same amount can get different offers. Published eligibility asks for a minimum monthly income of β‚Ή18,000 for salaried applicants and β‚Ή20,000 for self-employed ones, with interest rates typically quoted between 14% and 36% p.a. depending on profile. It accepts a low or even zero CIBIL score, which makes it accessible, but that flexibility shows up in the rate you’re offered. 

PaySense is the Best App To Get Instant Loan Without Salary Slip for self-employed borrowers with steady, provable cash flow who don’t yet have a strong credit file.

5. MoneyView β€” Best for Tier-2/Tier-3 Self-Employed Borrowers

MoneyView is frequently the first recommendation for salaried applicants outside metro cities and for self-employed or gig workers who want minimal paperwork. It’s positioned between the small-ticket apps and the larger NBFC lenders, with loan amounts up to around β‚Ή10 lakh and rates generally in the low-to-mid double digits for stronger profiles, rising for thinner files β€” broadly comparable to KreditBee’s range, though it’s often described as steadier on collection practices in user reviews. 

Best for: borrowers outside major metros who want a mid-sized loan without a Tier-1-city credit profile.

6. mPokket β€” Best for Students and Thin-File Gig Workers

mPokket is built specifically for people the traditional system ignores entirely β€” students and gig workers with little or no credit history. Loan sizes are smaller than the others on this list, aimed at short-term, small-amount needs like covering a bill or a temporary cash gap rather than a big-ticket expense. It shouldn’t be treated as a recurring source of funds β€” the sizes and terms make it best suited to occasional, short-duration borrowing. 

Best for: students or new-to-credit gig workers who need a small amount and have nowhere else to turn.

Read More πŸ‘‰ How to Start a Mineral Water Business: Complete Guide

How To Get an Instant Personal Loan Through Paytm, PhonePe, GPay, and Bhim

The same apps you use to split a dinner bill or pay your electricity bill can also get you a loan β€” often within minutes. Here’s how each one actually works:

Paytm

Open the Paytm app, head to the “Loans & Credit Cards” section, and tap “Personal Loan.” Paytm lets you apply anytime for an instant loan online in about two minutes, with a fully digital process and loan amounts ranging from β‚Ή5,000 to β‚Ή15 lakh, flexible tenure, and the option to foreclose anytime. 

Paytm doesn’t lend the money itself β€” it partners with RBI-regulated NBFCs and banks who actually underwrite and disburse the loan. You’ll go through PAN and Aadhaar-based KYC either way.

PhonePe

Same idea, different app. PhonePe doesn’t hand out loans directly β€” it has partnered with various banks and NBFCs to offer instant loans, so you can apply without ever leaving the app.  Loan amounts go up to β‚Ή5 lakh, repayable over tenures of up to 60 months, at rates starting around 13% per annum, with the approved amount transferred straight to your bank account.  Most lenders here look for a stable income and a credit score around 650 or higher.

Google Pay

Google Pay follows the same partner-lending model as Paytm and PhonePe β€” it doesn’t lend directly but connects you to its NBFC and bank partners for a pre-approved or application-based personal loan inside the app, with KYC handled digitally via Aadhaar and PAN.

BHIM

This one surprises people, since BHIM is best known as NPCI’s bare-bones UPI app. But it’s expanded: BHIM now lets you explore a personal loan without leaving the app, again through its network of lending partners rather than lending in-house.

How to Check an App Isn’t a Scam Before You Apply

RBI does not license individual apps β€” it regulates the bank or NBFC behind them. That distinction is the entire safety check:

  • Find the named NBFC or bank. A legitimate app discloses its lending partner clearly in the app, on the Play Store listing, or in the loan agreement. If you can’t find a specific company name, stop.
  • Verify that name on rbi.org.in or the RBI’s Digital Lending Apps directory before you submit any documents.
  • Never pay upfront. Processing fees, “insurance,” or “security deposits” requested before disbursal are the single most common fraud pattern. Legitimate lenders deduct fees from the loan amount after approval, not before.
  • Check what permissions it wants. A real KYC process needs your camera for a selfie and basic identity/banking access β€” not your full contact list, photo gallery, SMS logs, or call history. Apps that demand those are usually building leverage for harassment-based recovery later, not assessing creditworthiness.
  • Look for a Key Fact Statement (KFS). RBI’s digital lending rules require one before disbursal, listing the all-in APR, not just a headline interest rate. A “1% per month” rate can look harmless until the APR reveals fees stacked on top.
  • Confirm a named grievance officer with a phone number and email β€” not just a generic contact form.

If two or more of these are missing, treat the app as a red flag regardless of its Play Store rating, which is not proof of regulatory legitimacy. Because the best app to get instant loan doesn’t mean every app is trustworthy.

Advertising Rate Is Always Different From Actual Amount You Receive in Your Account

Headline interest rates on these apps are quoted per annum, but the real cost shows up in the APR, once processing fees and GST on those fees are added in. A concrete example: on a KreditBee loan disbursed at roughly β‚Ή1 lakh, one published breakdown shows a β‚Ή4,000 processing fee (4%), β‚Ή720 GST on that fee, and β‚Ή10 in documentation charges β€” pushing the effective APR to 29.66%, even though the headline rate for that borrower’s tier read lower. 

The amount that actually lands in the bank account was around β‚Ή95,270, not the full β‚Ή1 lakh. This is exactly what the Key Fact Statement is meant to expose, and it’s why comparing apps on their advertised “starting from” rate alone is close to useless β€” always ask for the APR and the net disbursal amount before accepting an offer, not just the interest rate.

Read More πŸ‘‰ How to Apply for an Education Loan Online

Which App Should You Consider For Instant Personal Loan?

  • If you’re a gig worker or freelancer with no credit history and need a small amount fast, start with KreditBee or Fibe. 
  • If you’re self-employed with steady bank statements and want a lower rate on a bigger amount, check Navi or MoneyView first and let your CIBIL score decide between them. 
  • If you’re a student or new to credit entirely, mPokket is built for exactly that gap, but treat it as a short-term bridge, not a repeat solution. 

Conclusion

WhicheverΒ  Best App To Get Instant Loan Without Salary Slip you land on, run it through the RBI-verification checklist above before you type in your PAN β€” that two-minute check is what separates a fair loan from a very expensive mistake.

The absence of a salary slip requirement is a documentation shortcut, not a signal that the loan is free of risk. A β‚Ή20,000 loan at 28% p.a. with a 4% upfront fee still needs to be repaid on schedule, and missed EMIs on these apps report to CIBIL just like a bank loan would. 

Borrow the amount you need for the problem in front of you, not the maximum the app is willing to approve β€” the higher your sanctioned limit looks, the more tempting it is to take more than the situation actually calls for.

Note: Rates, loan limits, and fees above reflect published figures as of mid-2026 and change frequently based on lender policy and individual credit profile β€” confirm current terms in-app before applying.

Leave a Comment

Your email address will not be published. Required fields are marked *

Business Ideas for Students With Zero Investment β€” Easy Startup Guide

Business Ideas

Your semester fees just went out, your parents already transferred money twice this month, and asking again feels wrong. Meanwhile, half your hostel WhatsApp group is talking about someone in third year who’s making pocket money reselling kurtis on Instagram, and another guy is tutoring juniors for β‚Ή500 an hour between classes. You’ve got a laptop, a phone, and more free time than you think β€” what you don’t have is capital. That’s fine, because none of the Business Ideas for students with zero investment below need any.

It’s a practical rundown of what students in India are actually doing right now to earn without touching their savings or taking a loan β€” plus how to do it without your attendance or your grades taking the hit.

Why Students Need These Business Ideas

Your parents are already paying the education cost in lakhs. Tuition, hostel fees, textbooks, and the occasional weekend trip are climbing faster than your father’s income. You thought of eating maggi at dinner to save the money but it won’t help. Customer service jobs or fixed shifts at retail shops pay the working hours so it affects your studies and classes. These Business Ideas for students are flexible, even if you start small, you can keep earning through referrals, repeat orders and content that stays active while you’re busy in exams.Β 

There’s a second reason that matters just as much: what you build now becomes proof of work later. A recruiter reading “ran a 200-follower food page that landed three restaurant collaborations” or “sold β‚Ή40,000 worth of handmade jewellery on Instagram over one semester” is reading initiative, sales sense, and follow-through β€” things a transcript can’t show. 

Freelance platforms like Fiverr and Upwork, and reselling apps like Meesho, have made the entry point for all of this genuinely free; you’re not renting a shop or buying inventory, you’re renting your own time.

How to Manage a Startup With Your Studies?

The honest risk with any student business is letting it eat into exam prep. A few ground rules keep that from happening:

  1. Block fixed hours, not “free time.” “I’ll work on it when I’m free” usually means never. Pick two or three specific slots a week β€” say, 7–9 PM on Tuesdays and Thursdays β€” and treat them like a lab session you can’t skip.
  2. Start with one product or one client, not five. Trying to tutor, resell, and run a YouTube channel in the same month usually means all three stay half-finished. Pick one, get it earning something small and consistent, then add the next.
  3. Use what your campus already gives you for free. Wi-Fi, a decent camera on a hostel-mate’s phone, a common room for shoots, a WhatsApp broadcast list of 60 classmates β€” that’s most of the “startup cost” covered before you spend a rupee.
  4. Protect exam weeks on purpose. Pause client work or batch your content a week in advance before internals and end-sems. A business that costs you a backlog isn’t worth running.
  5. Treat semester breaks as your test lab. Two months without lectures is the best window to try an idea at full speed and see if it’s worth continuing during term time, or if it was only ever a break-time project.

Read MoreπŸ‘‰ Best Laptops for Coding and Programming: Top Picks for Every Budget

Business Ideas for Students With Zero Investment

Each of these can be started with a phone, an internet connection, and whatever skill or spare time you already have. No inventory to buy, no shop to rent.

1. Tutoring & Trainer

If you’re good at a subject, a language, or even a sport, someone younger is struggling with exactly that right now. Offline, this means tutoring school kids in your neighbourhood or juniors in your own course during exam season. 

Online, platforms like Vedantu, Superprof, and Unacademy let you list yourself as a subject tutor without paying a listing fee, and you can also just post in your college’s WhatsApp/Telegram groups. Beyond academics, “trainer” covers fitness coaching, yoga sessions, or teaching a musical instrument over video call β€” anything you already know how to do.

2. Reselling Products

Reselling apps let you sell fashion, home, and lifestyle products through your own WhatsApp and Instagram without holding stock β€” the supplier ships directly to the buyer. Meesho is the platform most Indian resellers currently use for this. You share a product link, add your margin, and the platform handles logistics. It’s genuinely zero-investment because you never buy stock upfront. You can purchase for yourself and make review videos for Youtube β€” a content idea that helps your channel monetize and receive more brand promotions.

3. Handmade & Crafted Items

If you make jewellery, resin art, candles, crochet pieces, or hand-painted items, you already have a product β€” you just need a shopfront. Instagram works as a free storefront on its own; a basic Shopify store is an option once orders pick up, though Shopify does charge a subscription once your free trial ends, so weigh that against your order volume first. 

College fests and flea markets are also underrated distribution: a single fest stall can outsell a month of Instagram posts because people can touch the product before buying.

4. Local Influencer

You don’t need lakhs of followers to start earning as a food, travel, or campus-news page β€” brands doing local marketing often care more about engagement rate than follower count. 

A food page covering canteens and local eateries near campus, a travel page documenting budget weekend trips, or a campus-news account covering fests and placements can all start picking up small paid collaborations once the page has a real, active audience β€” even a few thousand followers.

5. Share Your Skills on YouTube

Teaching what you know on camera works because the content keeps earning views long after you upload it. Coding walkthroughs, recipe videos, DIY room-decor tutorials, study-with-me sessions, or a “learn Spanish in 10 minutes” series are all formats students are already running successfully. 

YouTube’s Partner Programme requires a watch-hour and subscriber threshold before ad revenue kicks in, so early on this is more about building an audience and a portfolio than instant income β€” brand deals usually arrive before AdSense money does.

6. Graphic Design

If you can put together a clean logo, an Instagram carousel, or a poster, small businesses and even fellow students will pay for it β€” most don’t have an in-house designer. Canva’s free tier is enough to start; Canva Pro is worth the (still low) cost only once you have paying clients. 

Fiverr is the easiest place to list design gigs with zero setup cost. Print-on-demand β€” designing T-shirts, mugs, or phone cases that a platform like Redbubble prints and ships only when someone orders, is the same skill applied to a physical product, again with no inventory risk.

7. Social Media Management and Content Writing

Small businesses β€” a local salon, a cafΓ©, a tuition centre β€” often know they need Instagram content but don’t have time to make it. Managing 2–3 such accounts for a monthly fee is realistic freelance work you can do from a hostel room. 

Content writing runs in parallel: blogs, product descriptions, and SEO articles are in constant demand, and platforms like Upwork and Contentmart are common entry points for beginners. If you’d rather build something of your own instead of freelancing for others, a niche newsletter or blog you grow yourself can eventually monetise through ads or sponsorships too.

Read MoreπŸ‘‰ How to Apply for a Student Loan to Get a Higher Education & Make Career

8. Repairing Mobiles and Laptops

Every hostel has someone with a cracked screen, a dead battery, or a laptop that won’t boot, and most students don’t want to make a trip to a service centre for something small. If you’re comfortable with basic hardware fixes and software troubleshooting β€” clearing malware, reinstalling an OS, replacing a battery β€” you can build a reputation purely through word of mouth in your own hostel block. This one scales slowly but has almost no competition on campus.

9. Making/Selling Notes, and Reselling Old Books

Well-organised, exam-focused notes are worth real money to juniors who’d rather buy clarity than make it themselves. Selling PDF notes or a compiled formula sheet through your class WhatsApp group costs you nothing but the time you’d have spent making them for yourself anyway. 

The same logic applies to old textbooks and reference books gathering dust after your exams β€” sell them directly to incoming juniors or through campus resale groups instead of letting them sit unused.

10. Tiffin or Food Delivery on Campus

Hostel food gets old fast, and a home-style tiffin service run out of your own kitchen (or a family member’s) fills a real gap β€” this works especially well if you live near campus and can cook, or partner with someone who does. 

Start with a small WhatsApp order list for your block before expanding, and be upfront about your kitchen’s hygiene standards since that’s the first thing customers will ask about.

11. Dropshipping Business

Dropshipping lets you run an online store β€” usually on Shopify where a supplier ships products directly to your customer, so you never hold stock. It’s worth being honest about one thing here: while there’s no inventory cost, most dropshipping stores don’t get real traffic without some ad spend, so “zero investment” mostly holds if you’re driving traffic organically through social media rather than paid ads, at least until the store proves itself.

12. Photography

If you already have a decent phone camera or access to a friend’s DSLR, campus fests, birthdays, and small local events are a steady source of paid photography work that needs no equipment purchase to start. Portfolio-building is the real first step β€” shoot a few events for free or cheap, post the best shots, and let those bookings lead to paid ones.

13. Audiobooks and Dubbing

If you have a clear speaking voice, platforms built for Indian-language audio content β€” Kuku FM and Pocket FM among them β€” regularly look for narrators and voice talent, and Audible’s ACX opens up English narration and dubbing work globally. This is genuinely zero-cost to start β€” a quiet room and a phone mic are enough for a demo reel.

You can use this skill to upload on Youtube without using copyright content and earn when thousands of people listen to it.

Read MoreπŸ‘‰ Best Student Loans for College Students

14. Creating AI Agents

This is the newest idea on the list and the one moving fastest. No-code automation tools β€” Zapier, Make, and n8n among them β€” let you build simple AI agents and chatbots (a WhatsApp order-taking bot for a local shop, an FAQ agent for a small business website) without writing production code. 

Local businesses that can’t afford a developer are a realistic first client base, and Fiverr/Upwork already have a growing “build me an AI agent” category. Because this space is changing month to month, treat any specific tool or pricing claim here as a starting point to verify, not a fixed fact.

15. Tour Coach

If you know your city well β€” the food streets, the history, the spots tourists never find on Google β€” you can run informal walking tours for other students, exchange-programme visitors, or tourists passing through. 

This starts as pure word-of-mouth and a shared Google Form for bookings; no licence or investment is needed for small informal group walks, though it’s worth checking your city’s local rules if you plan to scale it into a formal, paid business.

How to Choose One Business Option for Yourself

With fifteen options on the table, picking one comes down to three honest questions:

What do you already do without being asked? If you’re the one editing everyone’s assignment for grammar, that’s writing or content work. If you’re the one people ask to fix their laptop, that’s repair. The idea that fits fastest is usually the one closest to a habit you already have.

How many hours can you actually spare each week? Tutoring and freelance writing can run for 3–4 hours weekly. A tiffin service or reselling business needs closer to daily attention. Be honest about your semester’s course load before committing to something time-heavy.

Does your campus or city actually have demand for it? A tiffin service needs hungry hostel students nearby. A tour-coach idea needs a city with something to show. Match the idea to where you actually are, not to what worked for someone in a different city’s Instagram reel.

If two ideas still feel equally right, run both for two weeks each during a low-pressure period and let actual results β€” not your gut β€” make the call.

Read More πŸ‘‰ Best Noise-Cancelling Headphones for Online Classes and Mock Tests 

Conclusion

You don’t need capital to start earning as a student β€” you need one skill, a few free hours a week, and the willingness to start small enough that a bad exam week doesn’t sink the whole thing. Pick the one idea from this list of β€œBusiness Ideas for students” that matches something you’re already good at, give it thirty days of consistent effort before judging it, and treat the first version as a test rather than a final plan.Β 

Most student businesses that actually last didn’t start as a five-year vision β€” they started as someone testing whether people would pay for something they were already doing for free.
Leave a Comment

Your email address will not be published. Required fields are marked *

UP Anganwadi Bharti 2026 β€” District-Wise Vacancies & Recruitment Details

UP Anganwadi Bharti 2026

UP Anganwadi Bharti 2026 recruitment is live and you can apply if the application portal is still live in your district. There’s no one deadline for the recruitment drive because it has a lot of separate district-level drives. It offers various posts such as Karyakatri and Sahayika, so these are open for females only.

First, understand the structure, eligibility, and selection process for UP Anganwadi Bharti then apply with all the required documents.

ParameterDetails
Recruitment NameUP Anganwadi Bharti 2026 (ICDS, Uttar Pradesh) 
Conducting AuthorityDistrict Programme Officer (DPO), Bal Vikas Seva evam Pushtahar Vibhag, UP 
Department / SchemeIntegrated Child Development Services (ICDS), Women & Child Development, UP 
Posts OfferedAnganwadi Worker (Karyakartri), Mini Worker, Anganwadi Helper / Sahayika 
Total Vacancies (Indicative)~60,000–61,600+ posts 
Eligibility Only female candidates, 10th / 12th pass
Residency ConditionCandidate must be resident of the same village/ward of the Anganwadi centre for which she applies
Application FeeNo fee for any category (General/OBC/EWS/SC/ST) 
Notification & Application WindowMain notification from Nov 2025; applications open/close district-wise through early–mid 2026 
Salary (Indicative)Around β‚Ή5,500 – β‚Ή12,000 per month 
Official WebsiteClick Here

Structure of UP Anganwadi Bharti 2026 β€” District by District

The notification is out from each district for the recruitment under the state government which directed the Department of Women and Child Development, to fill vacant Anganwadi Karyakatri (Worker) and Anganwadi Sahayika (Helper) posts across Uttar Pradesh. Instead of one recruitment drive, each District Programme Officer releases and manages notification and recruitment for their district at different times.

DistrictPostsLast date to apply
Jhansi223 (across 9 CDPOs)7 /September /2026
Maharajganj3051 /September /2026
Chitrakoot92 (23 Karyakatri + 69 Sahayika)5 /September /2026
HamirpurActive16/September/ 2026
BalrampurActive23 /September /2026
Amroha (J.P. Nagar)105 (across 7 projects)24 /September /2026

Earlier in the year, Bagpat and Kannauj ran their own window for 760 combined posts, applying from 25 June to 16 July 2026 β€” that cycle is closed, and candidates there are now waiting on the merit list.

Who Can Apply For UP Anganwadi Post

A few conditions hold across nearly every district notification:

  • Only female candidates are eligible β€” there’s no male category in this recruitment. 
  • Female candidates should be between 18 and 45 years, calculated as on 1 July 2025. Relaxation given only reserved category.
  • Anganwadi Karyakatri posts sometimes require an Intermediate marksheet, depending on the district rules. 
  • Helper (Sahayika) posts have historically carried a lower bar in some districts, occasionally as low as 8th pass.

The condition that trips up the most applicants isn’t age or education β€” it’s domicile. You can’t apply to whichever district has the most vacancies. Each post is tied to a specific ward (in urban areas) or gram/nyaya panchayat (in rural areas), and you must be a permanent resident of that exact unit. A vacancy list in Jhansi is not open to a resident of Kanpur, even within the same state.

Read More πŸ‘‰ UP SuperTET Vacancy Notification 2026: Check Out Details, Dates, & Eligibility

Vacancies Numbers Are Huge

The total vacancies are more than 60000 across the state. Open your district’s latest 2026 notification PDF to check the vacancy number.

DistrictPost TypeVacanciesKey Detail
FatehpurWorker + Helper389150 Worker + 239 Helper (Aug–Sept 2026)
BandaWorker122Last date 22 Sept 2026
HamirpurWorker80Last date 16 Sept 2026
UnnaoWorker336Last date 11 Aug 2026
GhaziabadHelper341Last date 07 Aug 2026
JhansiWorker (Karyakatri)223Across 9 projects; last date 07 Sept 2026
Kanpur NagarHelper (Sahayika)307Across 12 projects; last date 05 Sept 2026
KushinagarWorker245Project-wise split available
KushinagarHelper (Sahayika)214Separate Helper notification
MaharajganjWorker + Helper305164 Worker + 141 Helper
SonbhadraWorker201Project-wise vacancy table available
MuzaffarnagarWorker146Anganwadi Worker posts only
GhazipurHelper1,352Among larger Helper batches
BulandshahrWorker + Helper678Combined posts
BagpatHelper374Helper-only batch
AzamgarhHelper265Helper-only batch

Selection Process & Application Fee

There’s no written test and, in the vast majority of district notifications reviewed so far, no interview either. Selection is by merit list, built from your marks in 10th, 12th, and graduation, all being equal. There’s no application fee for any category, including SC, ST, PwBD, and general female candidates β€” this recruitment is free to apply for, full stop.

Salary Of UP Anganwadi Posts

A β‚Ή10,000/month for Anganwadi Worker, β‚Ή7,500 for Mini Worker, and β‚Ή4,500 for Helper as honorarium (not salary β€” these are Anganwadi posts, not salaried government service, and the distinction affects things like PF and pension eligibility). 

Getting Your Application In Before Your Window Closes

Applications go through upanganwadibharti.in 

On the homepage, you’ll find a running list of “active” district notifications with their upload and closing dates; this list changes weekly as new districts come online and others close.

Fill your details correctly in the form and submit with all the necessary documents attached. There is no application fee, so apply early and correctly.

The real trap here is timing, not eligibility. Most district windows stay open for only two to four weeks from the upload date β€” Hamirpur’s notification, for example, went up on 27 August and closes 16 September, an 18-day window. 

Bookmark the official portal itself, and search for your specific ward or gram panchayat, not just your district name; that’s the actual unit your eligibility is judged against.

Documents Required To Apply

Gather your documents first before your district application portal goes live. The necessary documents are listed in the notification PDF but you can also catch it here:

  • Your education proof – any 10th, 12th, and graduation marksheets, 
  • Domicile certificate for resident confirmation, 
  • Caste certificate (if you belong to reserved category), 
  • Aadhaar/ PAN Card, and 
  • A recent passport size photograph 
  • Signature on the blank page

Get ready with all these documents before your ward’s notification even drops.

Read More πŸ‘‰ Planning MBBS or Master’s Abroad? Country-Wise Costs, Loan Limits and Lenders

Conclusion

UP Anganwadi Bharti 2026 notification is out but recruitment is active in some districts and closed in few districts. If the recruitment is active in your region then apply now before it gets closed. The vacancy numbers are huge, more than 60,000 posts are vacant and these seats are only open for females. 

But you must be the resident of that village to apply, and the documents must be prepared including your adhaar, high school marksheet, domicile certificate etc. You can apply for free but check the notification before you apply for the Karyakatri and Sahayika position.

Leave a Comment

Your email address will not be published. Required fields are marked *

How to Apply for an Education Loan Online

Education Loan

Your admission letter has a deadline attached to it, and so does the deposit your college wants. That’s usually the exact moment families realise they need an education loan and have no idea where to start β€” which bank, which portal, how long it takes, or whether the college fee will actually reach the institute on time. Applying for an Education Loan online in India isn’t hard once you know the sequence, but doing it in the wrong order costs weeks you don’t have.

Here’s the sequence that actually works, plus the numbers most guides skip.

Start On The Vidya Lakshmi Portal, Not a Random Bank Branch

The government’s PM-Vidyalakshmi portal (pmvidyalaxmi.co.in) exists precisely to stop students from filling out ten different forms at ten different bank branches. It currently lists 86 education loan schemes from 38 banks, and lets you fill one Common Education Loan Application Form (CELAF) and send it to up to three lenders at once. Each bank evaluates it independently and responds through your dashboard β€” you compare offers side by side instead of chasing branch managers.

You can still apply directly through a bank’s own app (SBI YONO, HDFC’s portal, or an NBFC like Credila or Avanse), and for study-abroad loans that’s often faster. But if you’re not sure which lender fits your profile, the portal is the better starting point because it also flags which subsidy schemes you qualify for β€” more on that below.

The Standard Step-By-Step Process on the Portal

Register on The Portal

with your mobile number, email, and Aadhaar. You’ll set up a student login and can save your progress partway.

Fill The CELAF  

Complete the Common Education Loan Application Form β€” personal and academic bio-data, course and institution details, total cost of education, and collateral info if applicable. One form covers every bank you apply to. 

Search and Shortlist Schemes. 

The portal shows which banks match your course, institute ranking, and loan amount, along with their listed interest rates.

Apply to up to 3 banks

Submit the same CELAF to up to three participating banks simultaneously. Each bank evaluates independently and responds through the portal.

Upload documents 

KYC, admission letter, fee structure/cost estimate, income proof, academic records, and collateral documents (if the loan amount requires security) go up here. Track status in real time β€” sanctioned, under review, or query raised.

Respond to Bank Queries 

Follow-up document requests, or interview calls show up directly on the dashboard if they ask for additional paperwork. Approval typically runs 15–30 working days depending on profile and paperwork. 

Sanction and Disbursement 

Loans are usually released in tranches per academic year β€” the first installment around admission time, the rest against fee receipts and progress certificates. Most banks send the amount as a demand draft or transfer straight to the institute, not to you.

Public sector banks typically take 15–25 days to sanction; NBFCs like Credila can do it in 7–14 days, which matters if your visa or admission deadline is tight.

Important Documents You Must Have For Education Loan

  • Admission letter with fee structure, 
  • 10th/12th mark sheets and entrance scorecard (JEE, NEET, CAT, GRE, whatever applies), 
  • Aadhaar and PAN, 
  • Co-applicant’s income proof (last two years’ ITR and Form 16, or salary slips), 
  • Last six months’ bank statements, 
  • Passport-size photos, 
  • Collateral documents if your loan amount needs security. 

Missing or blurry documents are the single biggest reason applications sit in “query raised” status for weeks.

Read More πŸ‘‰ Business Ideas for Students With Zero Investment β€” Easy Startup Guide

How Much You Have To Repay in Education Loan Online

Headline rates change with every RBI repo revision, so treat these as indicative starting points as of mid-2026, not fixed numbers β€” confirm the current rate directly with the lender before you sign anything.

LenderIndicative rate (p.a.)Notes
SBI Scholar Loan (IIT/IIM/ISB/select institutes)6.90% – 7.65%Lowest rates available, but restricted to a specific institute list
SBI Global Ed-Vantage (study abroad)From ~9.15%Flat β‚Ή10,000 processing fee, needs 15% margin money above β‚Ή4 lakh
PNB8.55% – 11.95%Up to β‚Ή20 lakh without collateral for eligible courses
Canara Bank9.25% – 11.95%Strong presence in South India
HDFC Bank9.50% – 13.50%Faster processing than most PSU banks
Axis Bank9.50% – 13.50%Similar positioning to HDFC
ICICI Bank10.50% – 13.50%Higher end of private-bank rates
HDFC Credila (NBFC)~9.75% secured / ~10.25%+ unsecured100% financing possible, sanction in days, but processing fee is 1–1.25% + GST
Avanse / Propelld (NBFC)~10% – 13.5%Collateral-free options up to β‚Ή60–75 lakh, merit-based pricing

The gap between a PSU bank’s lowest rate and an NBFC’s unsecured rate can run 3–4 percentage points. On a β‚Ή15 lakh loan over 10 years, that difference alone adds up to several lakh rupees in extra interest β€” it’s worth the extra week of paperwork to get a PSU sanction if your timeline allows it.

The Subsidy Most Students Never Check For

Two separate government schemes can cut your effective rate, and they’re easy to confuse:

PM-Vidyalakshmi interest subvention (launched November 2024) gives a 3% interest subvention on loans up to β‚Ή10 lakh, during the study period and moratorium, if your family income is up to β‚Ή8 lakh a year. It only applies if you’re admitted to a Quality Higher Education Institution β€” over 860 of them qualify, including all IITs, NITs, and IIMs, plus state institutions ranked 101–200 in the NIRF list. There’s also a 75% government credit guarantee on loans up to β‚Ή7.5 lakh, which is why some banks will sanction you without asking for collateral or a guarantor.

Central Sector Interest Subsidy (CSIS) is the older scheme β€” it covers the full interest during moratorium, but only for families earning up to β‚Ή4.5 lakh a year and only at a separate, narrower list of premier institutions. You can’t claim both on the same loan, so check which one your institute and income bracket actually qualify for before assuming you get nothing.

Apply for whichever subvention you’re eligible for through the same portal β€” it isn’t automatic.

What Happens Once You Start Your Repayment

Once repayment starts, the interest you pay (not the principal) is fully deductible under Section 80E of the Income Tax Act β€” no upper limit on the amount. The deduction runs for 8 years from when you start repaying, or until the interest is fully paid off, whichever comes first. 

It applies to loans taken for your own, your spouse’s, or your children’s higher education, but only from a bank or a notified financial institution β€” a loan from a relative doesn’t qualify.

Read More πŸ‘‰ How to Start a Mineral Water Business: Complete Guide

How You Can Save Real Money in Education Loan

  • Girl students get an automatic 0.5% rate concession at most public sector banks β€” ask for it explicitly if it isn’t applied.
  • Pay simple interest during the moratorium if you can manage it, even partially. Left unpaid, it often compounds once repayment begins, and on a β‚Ή10 lakh loan that gap can run into a couple of lakh rupees by the time you graduate.
  • Compare processing fees, not just the headline rate. SBI charges a flat β‚Ή10,000; NBFCs typically charge 1–1.75% of the loan plus GST, which is a meaningful amount on a β‚Ή50 lakh loan.
  • Check margin money requirements. PSU banks generally need you to fund 15% of the cost yourself for loans above β‚Ή4 lakh (domestic) or above a certain threshold for study abroad; several NBFCs offer 100% financing instead.
  • Ask about prepayment penalties before signing with an NBFC β€” some charge 1–3% if you close the loan early, which matters if your income grows faster than expected.

What If Your Study Loan Application Gets Stuck?

Most delays trace back to one of four things: 

Documents uploaded in the wrong format or half-legible, applying to a bank whose collateral rules don’t match the loan amount requested, assuming you qualify for a subsidy without checking the institute list first, and accepting the first offer instead of comparing at least two or three sanctioned terms side by side.

Register on the Vidya Lakshmi portal, shortlist one PSU bank and one NBFC so you have both a low-rate option and a fast-sanction backup, check which subsidy scheme your institute and income actually qualify for, and get your documents scanned before you start the form β€” not after a bank asks for them.

Conclusion

Understanding How to Apply for an Education Loan Online lets you avoid mistakes, get your documents ready at time, and not get your application stuck. If you want to pursue your education but can’t afford it, the study loan will help you achieve your dreams. Remember to check the bank’s interest and calculate the cost you have to pay later.

Leave a Comment

Your email address will not be published. Required fields are marked *

Best Student Loans for College Students

Student Loans

Your admission letter came through and you are stressed about its fees? That’s the moment you’ll start looking for the best student loans for college students. Between tuition, hostel, a laptop, and living costs, a B.Tech at a decent private college or a master’s abroad can run anywhere from β‚Ή8 lakh to over β‚Ή1 crore, and very few Indian families are sitting on that kind of cash without dipping into a fixed deposit meant for something else. 

This is exactly where the best Student Loans in the market β€” from SBI’s Scholar Loan to NBFCs like HDFC Credila and Avanse, start doing real work, provided it actually fits your situation instead of just going with whichever bank branch is nearest to your house.

This blog walks through the loan for education options Indian students actually use in 2026 β€” public banks, private banks, NBFCs, and the government’s PM Vidyalaxmi scheme with real numbers, what each one is genuinely good at, and where it falls short.

Who Can Get These Loans for Education

If you’re an Indian student (or a parent reading this on their behalf) heading into an undergraduate program, a postgraduate course, or a study-abroad admission, and you need a study loan rather than paying out of pocket, this comparison is built for you. It splits lenders into three buckets β€” public sector banks, private banks, and specialised NBFCs because each serves a different kind of borrower, and picking the wrong bucket is the single most common reason students overpay by lakhs over a 15-year tenure.

Interest rates on education loans are floating and revised frequently by each lender’s internal benchmark. The figures below reflect indicative ranges reported by lenders and comparison platforms as of mid-2026. Treat every rate here as a starting reference, not a quote so confirm the live number on the lender’s own site before you apply.

Best Student Loans For College Students in India

1. SBI Scholar Loan / Global Ed-Vantage β€” Best for Domestic Students and Government-Bank Trust

  • Rate: roughly 8.15%–10.75%, MCLR-linked (floating)
  • Loan amount: up to β‚Ή7.5 lakh without collateral for listed premier institutes; higher amounts with collateral, up to β‚Ή1.5 crore under Global Ed-Vantage for study abroad
  • Processing fee: flat β‚Ή10,000 β€” no percentage-based fee
  • Tenure: up to 15 years

SBI remains the default first stop for most Indian students, and there’s a simple reason: as the largest public bank, it consistently prices education loans lower than private banks and NBFCs, and its flat processing fee actually saves real money on larger loans compared to a percentage-based charge. 

The trade-off is speed β€” SBI’s sanction process for study-abroad loans can take four to eight weeks, and IBA guidelines require 15% margin money on foreign education loans above β‚Ή4 lakh, meaning you’ll need to arrange that slice yourself. 

Best for: students with time before their visa deadline who want the lowest lifetime interest cost.

2. HDFC Credila β€” Best for Speed and High-Value Unsecured Loans

  • Rate: roughly 9.5%–13%, secured loans starting near 9.95%, unsecured (no collateral) starting near 11.25%
  • Loan amount: up to β‚Ή50–60 lakh for premier institutes, sometimes higher
  • Processing fee: 1%–1.5% plus GST
  • Tenure: up to 15 years

Credila built its business on what it calls a “future employability” assessment rather than collateral value, which is why students without property to pledge still get approved here. Sanctions typically land in 7–14 days, which matters enormously when a visa interview is on the calendar and SBI’s timeline doesn’t fit. 

The catch is that unsecured Credila loans run meaningfully higher than SBI’s rate, and the processing fee, a percentage plus GST are added up fast on a β‚Ή50 lakh loan. 

Best for: students on a tight admission or visa timeline who need fast, collateral-free approval and can absorb a higher rate.

3. Bank of Baroda β€” Best for Large Loans to Global Universities

  • Rate: competitive with SBI, generally in the 8.5%–11% band depending on the institute tier
  • Loan amount: up to β‚Ή1.5 crore for premium global universities
  • Processing fee: typically lower than private banks; concessions available for girl students
  • Tenure: up to 15 years

BoB doesn’t get the same attention as SBI or the big NBFCs, but for students heading to genuinely expensive programs like top-50 global MBAs or engineering master’s β€” its higher loan ceiling and public-bank pricing make it worth a direct comparison. 

Best for: high-ticket study-abroad admissions where you need both a large sanction and a public-bank rate.

4. Avanse Financial Services β€” Best for Broad Course Coverage

  • Rate: roughly 11%–14.5%
  • Loan amount: up to β‚Ή50–75 lakh
  • Processing fee: 1.25%–1.75% plus GST
  • Tenure: up to 15 years

Avanse is one of the few lenders that regularly finances courses public banks are cautious about β€” niche postgraduate programs, some online degrees, and vocational tracks. It’s genuinely useful when your course doesn’t fit a PSU bank’s approved list. The limitation is its rates sit at the higher end of the NBFC range, so it’s rarely the cheapest option on the table. 

Best for Student Loans for college students whose course or university isn’t covered by public-bank lending lists.

Read MoreπŸ‘‰ RRB JE Notification OUT With RRB JE Vacancy Of 3,993 Posts 

5. Axis Bank / ICICI Bank Education Loan β€” Best for Existing Bank Customers Wanting Fast Digital Processing

  • Rate: roughly 9.5%–13.5%
  • Loan amount: up to β‚Ή40 lakh
  • Processing fee: moderate, varies by profile
  • Tenure: typically 10–15 years

If you or your parents already bank with Axis or ICICI, pre-approved education loans can be sanctioned in as little as 72 hours for existing customers, bundled with a forex card and a student account for study abroad. The point here is convenience, not price β€” you’re paying slightly more for an integrated, faster experience with a bank you already have a relationship with. 

Best for: existing customers who value speed and a bundled international banking package over shaving off the last percentage point of interest.

SBI vs HDFC Credila: The Two-Lender Face-Off

These two get compared constantly because they represent opposite philosophies β€” lowest cost versus fastest approval.

SBI Global Ed-VantageHDFC Credila
Starting rate~8.15%–9.65%~9.5%–11.25% (unsecured)
Processing feeFlat β‚Ή10,0001%–1.5% + GST
Sanction time4–8 weeks7–14 days
CollateralRequired above β‚Ή7.5 lakhOptional, employability-based
Best forLowest total interest costTight visa or admission deadlines

On a β‚Ή50 lakh, 15-year loan, roughly every 100 basis points of extra interest costs about β‚Ή7.5 lakh over the loan’s life, so the gap between these two isn’t cosmetic. Take Credila or Avanse first to secure fast disbursal for the visa file, then refinance into SBI once the loan is live and the pressure is off.


This works better than it used to, because the RBI’s Prepayment Charges Directions, effective January 1, 2026, banned foreclosure and prepayment charges on floating-rate loans to individual borrowers β€” a rule that covers nearly every education loan in this list. Before this, NBFCs could charge 2%–5% of the outstanding principal to close a loan early; that lock-in is now gone.

Don’t Skip the Government Route: PM Vidyalaxmi Scheme

Before comparing private lenders at all, check whether you qualify for PM Vidyalaxmi, the Centre’s collateral-free education loan scheme launched in November 2024. It isn’t a separate lender β€” it works through participating banks but it changes the math significantly for eligible students:

  • Collateral-free, guarantor-free loans up to β‚Ή7.5 lakh, backed by a 75% government credit guarantee
  • Covers students admitted purely on merit (not management or NRI quota) to around 1,425 listed Quality Higher Education Institutions
  • A 3% interest subvention during the moratorium period for families with annual income up to β‚Ή8 lakh, on loans up to β‚Ή10 lakh
  • Rates capped at the bank’s benchmark lending rate plus 0.5%, with banks free to offer an extra 1% concession if you service interest during your study period
  • Subsidy is disbursed directly through the PM Vidyalaxmi Digital Rupee (CBDC) app

More than 1.12 lakh loans had been sanctioned under the scheme as of July 2026, so it’s no longer a pilot β€” it’s a live, functioning route worth checking on the PM Vidyalaxmi portal before you approach a bank directly.

Read More πŸ‘‰ Best Student Laptops for School and University in 2026 

Two Rules That Apply Regardless of Which Lender You Choose

Section 80E tax benefit: the entire interest you pay on student loans for college students β€” not principal, and with no upper cap is deductible from your taxable income for up to 8 years from the year you start repaying. This applies to loans from any bank or approved NBFC and is one of the few genuinely uncapped deductions left in Indian tax law.

The girl-student concession: most public banks, including SBI and PNB, shave 0.5% off the standard rate for female applicants. It’s easy to miss because it’s rarely advertised loudly β€” ask for it explicitly when you apply for any of these student loans for college students.

Conclusion

If your priority is the lowest total interest over 15 years and you have a few weeks before your deadline, start with SBI β€” check PM Vidyalaxmi eligibility first if your loan need is under β‚Ή7.5 lakh. 

If your visa interview or admission deposit deadline is within two weeks and you need money to move fast, HDFC Credila or Avanse will get you there, with the option to refinance into a cheaper public-bank loan later at no penalty under the new RBI rule. And if your course or university sits outside what PSU banks typically approve, Avanse’s broader course coverage is worth a direct call before you assume you’re out of options. 

Whichever lender you pick, don’t sign with the first offer you get on Student Loans for college students β€” pull two or three live quotes through the Vidya Lakshmi portal, apply the 80E deduction into your repayment planning from day one, and claim every concession you’re eligible for.

Note: Interest rates, fees, and scheme terms mentioned above are indicative and change frequently. Verify current figures directly with the lender or on official government portals before applying. 

Leave a Comment

Your email address will not be published. Required fields are marked *

Scroll to Top