How to Apply for an Education Loan Online

Education Loan

Your admission letter has a deadline attached to it, and so does the deposit your college wants. That’s usually the exact moment families realise they need an education loan and have no idea where to start β€” which bank, which portal, how long it takes, or whether the college fee will actually reach the institute on time. Applying for an Education Loan online in India isn’t hard once you know the sequence, but doing it in the wrong order costs weeks you don’t have.

Here’s the sequence that actually works, plus the numbers most guides skip.

Start On The Vidya Lakshmi Portal, Not a Random Bank Branch

The government’s PM-Vidyalakshmi portal (pmvidyalaxmi.co.in) exists precisely to stop students from filling out ten different forms at ten different bank branches. It currently lists 86 education loan schemes from 38 banks, and lets you fill one Common Education Loan Application Form (CELAF) and send it to up to three lenders at once. Each bank evaluates it independently and responds through your dashboard β€” you compare offers side by side instead of chasing branch managers.

You can still apply directly through a bank’s own app (SBI YONO, HDFC’s portal, or an NBFC like Credila or Avanse), and for study-abroad loans that’s often faster. But if you’re not sure which lender fits your profile, the portal is the better starting point because it also flags which subsidy schemes you qualify for β€” more on that below.

The Standard Step-By-Step Process on the Portal

Register on The Portal

with your mobile number, email, and Aadhaar. You’ll set up a student login and can save your progress partway.

Fill The CELAF  

Complete the Common Education Loan Application Form β€” personal and academic bio-data, course and institution details, total cost of education, and collateral info if applicable. One form covers every bank you apply to. 

Search and Shortlist Schemes. 

The portal shows which banks match your course, institute ranking, and loan amount, along with their listed interest rates.

Apply to up to 3 banks

Submit the same CELAF to up to three participating banks simultaneously. Each bank evaluates independently and responds through the portal.

Upload documents 

KYC, admission letter, fee structure/cost estimate, income proof, academic records, and collateral documents (if the loan amount requires security) go up here. Track status in real time β€” sanctioned, under review, or query raised.

Respond to Bank Queries 

Follow-up document requests, or interview calls show up directly on the dashboard if they ask for additional paperwork. Approval typically runs 15–30 working days depending on profile and paperwork. 

Sanction and Disbursement 

Loans are usually released in tranches per academic year β€” the first installment around admission time, the rest against fee receipts and progress certificates. Most banks send the amount as a demand draft or transfer straight to the institute, not to you.

Public sector banks typically take 15–25 days to sanction; NBFCs like Credila can do it in 7–14 days, which matters if your visa or admission deadline is tight.

Important Documents You Must Have For Education Loan

  • Admission letter with fee structure, 
  • 10th/12th mark sheets and entrance scorecard (JEE, NEET, CAT, GRE, whatever applies), 
  • Aadhaar and PAN, 
  • Co-applicant’s income proof (last two years’ ITR and Form 16, or salary slips), 
  • Last six months’ bank statements, 
  • Passport-size photos, 
  • Collateral documents if your loan amount needs security. 

Missing or blurry documents are the single biggest reason applications sit in “query raised” status for weeks.

Read More πŸ‘‰ Business Ideas for Students With Zero Investment β€” Easy Startup Guide

How Much You Have To Repay in Education Loan Online

Headline rates change with every RBI repo revision, so treat these as indicative starting points as of mid-2026, not fixed numbers β€” confirm the current rate directly with the lender before you sign anything.

LenderIndicative rate (p.a.)Notes
SBI Scholar Loan (IIT/IIM/ISB/select institutes)6.90% – 7.65%Lowest rates available, but restricted to a specific institute list
SBI Global Ed-Vantage (study abroad)From ~9.15%Flat β‚Ή10,000 processing fee, needs 15% margin money above β‚Ή4 lakh
PNB8.55% – 11.95%Up to β‚Ή20 lakh without collateral for eligible courses
Canara Bank9.25% – 11.95%Strong presence in South India
HDFC Bank9.50% – 13.50%Faster processing than most PSU banks
Axis Bank9.50% – 13.50%Similar positioning to HDFC
ICICI Bank10.50% – 13.50%Higher end of private-bank rates
HDFC Credila (NBFC)~9.75% secured / ~10.25%+ unsecured100% financing possible, sanction in days, but processing fee is 1–1.25% + GST
Avanse / Propelld (NBFC)~10% – 13.5%Collateral-free options up to β‚Ή60–75 lakh, merit-based pricing

The gap between a PSU bank’s lowest rate and an NBFC’s unsecured rate can run 3–4 percentage points. On a β‚Ή15 lakh loan over 10 years, that difference alone adds up to several lakh rupees in extra interest β€” it’s worth the extra week of paperwork to get a PSU sanction if your timeline allows it.

The Subsidy Most Students Never Check For

Two separate government schemes can cut your effective rate, and they’re easy to confuse:

PM-Vidyalakshmi interest subvention (launched November 2024) gives a 3% interest subvention on loans up to β‚Ή10 lakh, during the study period and moratorium, if your family income is up to β‚Ή8 lakh a year. It only applies if you’re admitted to a Quality Higher Education Institution β€” over 860 of them qualify, including all IITs, NITs, and IIMs, plus state institutions ranked 101–200 in the NIRF list. There’s also a 75% government credit guarantee on loans up to β‚Ή7.5 lakh, which is why some banks will sanction you without asking for collateral or a guarantor.

Central Sector Interest Subsidy (CSIS) is the older scheme β€” it covers the full interest during moratorium, but only for families earning up to β‚Ή4.5 lakh a year and only at a separate, narrower list of premier institutions. You can’t claim both on the same loan, so check which one your institute and income bracket actually qualify for before assuming you get nothing.

Apply for whichever subvention you’re eligible for through the same portal β€” it isn’t automatic.

What Happens Once You Start Your Repayment

Once repayment starts, the interest you pay (not the principal) is fully deductible under Section 80E of the Income Tax Act β€” no upper limit on the amount. The deduction runs for 8 years from when you start repaying, or until the interest is fully paid off, whichever comes first. 

It applies to loans taken for your own, your spouse’s, or your children’s higher education, but only from a bank or a notified financial institution β€” a loan from a relative doesn’t qualify.

Read More πŸ‘‰ How to Start a Mineral Water Business: Complete Guide

How You Can Save Real Money in Education Loan

  • Girl students get an automatic 0.5% rate concession at most public sector banks β€” ask for it explicitly if it isn’t applied.
  • Pay simple interest during the moratorium if you can manage it, even partially. Left unpaid, it often compounds once repayment begins, and on a β‚Ή10 lakh loan that gap can run into a couple of lakh rupees by the time you graduate.
  • Compare processing fees, not just the headline rate. SBI charges a flat β‚Ή10,000; NBFCs typically charge 1–1.75% of the loan plus GST, which is a meaningful amount on a β‚Ή50 lakh loan.
  • Check margin money requirements. PSU banks generally need you to fund 15% of the cost yourself for loans above β‚Ή4 lakh (domestic) or above a certain threshold for study abroad; several NBFCs offer 100% financing instead.
  • Ask about prepayment penalties before signing with an NBFC β€” some charge 1–3% if you close the loan early, which matters if your income grows faster than expected.

What If Your Study Loan Application Gets Stuck?

Most delays trace back to one of four things: 

Documents uploaded in the wrong format or half-legible, applying to a bank whose collateral rules don’t match the loan amount requested, assuming you qualify for a subsidy without checking the institute list first, and accepting the first offer instead of comparing at least two or three sanctioned terms side by side.

Register on the Vidya Lakshmi portal, shortlist one PSU bank and one NBFC so you have both a low-rate option and a fast-sanction backup, check which subsidy scheme your institute and income actually qualify for, and get your documents scanned before you start the form β€” not after a bank asks for them.

Conclusion

Understanding How to Apply for an Education Loan Online lets you avoid mistakes, get your documents ready at time, and not get your application stuck. If you want to pursue your education but can’t afford it, the study loan will help you achieve your dreams. Remember to check the bank’s interest and calculate the cost you have to pay later.
Leave a Comment

Your email address will not be published. Required fields are marked *

How to Start a Mineral Water Business: Complete Guide

Mineral Water Business

Students who want to start a business while studying that will grow with time when they get passed out but don’t know how to start a mineral water business, stay consistent and understand everything step-by-step. Why the Mineral Water Business ? Because it’s easy and needs less investment so students can easily work it out.

In every area there’s someone on a bicycle, two or three 20-litre cans strapped to the back seat, making rounds before the 9 a.m. lecture. And you’re wondering about the cost per can, number of houses in the block, weekly demand and deciding to start a mineral water business. It sounds like the side income you’ve been looking for.

It’s not a bad instinct. Even if you don’t have six months of free time, and lakhs of rupees sitting idle. You can still set up your small business amid juggling a timetable, a hostel curfew, and exam weeks. Here’s what actually applies if you’re starting this while you’re still enrolled.

Mineral Water Business Is Different From Packaged Drinking Water

The label gets used loosely, and that’s where a lot of first-time entrepreneurs trip up. Under Indian standards, “natural mineral water” (IS 13428) and “packaged drinking water” (IS 14543) are two different categories. The natural mineral water is sourced from a protected mineral spring, while packaged drinking water is the RO-and-UV purified water in cans and bottles that almost every local plant actually sells. 

If you’ve ever seen a delivery guy with unbranded 20-litre cans, that’s packaged drinking water, not mineral water in the technical sense β€” even though everyone calls it “mineral water” on the street.

It matters because both categories legally require BIS certification if you’re selling them in a sealed, labelled container under a brand name. FSSAI registration is a separate, additional requirement that applies to anyone in the food and water supply chain β€” manufacturer, distributor, or reseller. 

Skipping either one isn’t a grey area; local FDA teams do seal unlicensed plants, and it happens more often than people expect. If you don’t have much money then you can apply for FSSAI certification to start with.

The Reality of Setting Up A Brand of Water

If the plan is to manufacture and bottle your own brand, here’s the honest range, based on current supplier and consultancy listings β€” treat these as ballpark figures and verify locally, since they shift by state, capacity, and vendor:

  • BIS/ISI certification facilitation through a consultant typically runs somewhere in the β‚Ή35,000–₹70,000 range.
  • Entry-level packaged drinking water machinery (RO plant, filling, capping) starts around β‚Ή2.4 lakh for lower-capacity units and climbs past β‚Ή13 lakh for higher-capacity setups.
  • A full project β€” machinery, water-testing lab, premises β€” can land around β‚Ή25 lakh once you include everything, which is roughly the scale seen in real project reports built for government-backed loans like PMEGP, financed mostly through a bank loan plus KVIC margin-money subsidy.

None of that is pocket money, and the setup timeline β€” BIS testing cycles, layout approval, machinery installation β€” usually runs months, not weeks. It’s a business for after you graduate, or for a family that already owns a plant.

Read More πŸ‘‰ Best Noise-Cancelling Headphones for Online Classes and Mock Tests 

How to Start a Mineral Water Business While Studying

The workaround isn’t to skip compliance β€” it’s to skip manufacturing. Instead of building a plant, tie up with a local packaged drinking water plant that already holds FSSAI and BIS certification, and become their reseller or delivery partner in a specific area you can actually cover between classes.

You’ll still need your own FSSAI Basic Registration β€” it’s mandatory for anyone distributing or reselling food and water products, not just manufacturers, but it’s a low-cost, online process aimed at businesses with turnover under β‚Ή12 lakh a year. No lab, no machinery, no factory inspection required at this tier.

However, you can’t put your own brand name on someone else’s water without their manufacturer backing you under their BIS license. Either sell openly under the supplier’s existing brand as their authorized reseller, or have a documented dealership arrangement. Your own labelled brand is the manufacturing route above β€” a later-stage move, not a starting point.

How to Manage Your Business While Attending Classes

A few things make the difference between this staying manageable and it eating your semester:

  • Keep the radius tight. Your own hostel block, one PG cluster, or a few shops near campus β€” something you can cover in under 15 minutes so it fits around lecture slots.
  • Vet suppliers in person. Visit two or three candidate plants, ask to physically see their FSSAI certificate and BIS license number rather than taking their word for it.
  • Apply for FSSAI Basic Registration early β€” it’s inexpensive and doesn’t take long, but it’s not something to leave until customers are already asking for it.
  • Run subscriptions, not daily orders. A weekly or monthly can subscription over WhatsApp is far easier to manage during exam weeks than fielding one-off orders every day.
  • Budget for the deposit cycle. Most local can systems run on a refundable can deposit β€” commonly in the β‚Ή50–100 range per can, though this varies by supplier. That money is tied up as working capital until the empty can comes back, not profit you can spend.
  • GST registration only becomes mandatory once turnover crosses β‚Ή40 lakh a year for goods in most states (lower in a few special-category states). Most student-run operations won’t hit that in year one.

Where Student Water Businesses Usually Fail

Three patterns show up repeatedly, and they’re worth naming before you start rather than after:

Treating it as passive income when it’s really a logistics job β€” someone has to physically move 20-kilogram cans at a fixed time, every week, including exam season. Letting the deposit-cash mismatch creep up β€” if thirty cans are out with customers and only ten deposits have come back, the working capital gap is real and it stalls reorders. 

And trying to compete on price against an established local operator who already owns the plant and the delivery network β€” a student reseller almost never wins that fight, and shouldn’t try. The actual pitch is convenience: reliable timing around class hours, UPI payment, water dropped right at the door. 

Read More πŸ‘‰ Business Ideas for Students With Zero Investment β€” Easy Startup Guide

Where To Begin Your Mineral Water Business?

  • Skip the machinery quote for now. Call two local packaged drinking water plants and ask if they take resellers. 
  • Apply for your FSSAI Basic Registration online. 
  • Then run a 20-can pilot in your own hostel or nearby block before spending a rupee on anything beyond that. 
  • If the pilot survives one full exam cycle without a missed delivery, you’ll know whether this is a real business or just a good week.

Conclusion

Understanding how to Start a Mineral Water Business as a student is different from starting as a manufacturer. So don’t follow large-level business instruction points, begin with less investment and short area to cover. 

While attending your classes, you can set up your side business for passive income and it gets succeeded then you can turn it into a large-scale business. Apply FSSAI registration and track down your reliable provider who already has a water plant industry. Expand the network in the hostel and nearby block to easily deliver the mineral water cans.

Stay consistent and don’t get bored in just one week, keep up with the idea and you’ll get a success. 

Leave a Comment

Your email address will not be published. Required fields are marked *

Best App To Get Instant Loan Without Salary SlipΒ 

Best App To Get Instant Loan Without Salary Slip

Your landlord isn’t waiting, the hospital isn’t waiting, and your bank’s personal loan officer just told you to come back “once you have three months of payslips.” That forces you to google for the Best App To Get Instant Loan Without Salary Slip because you need β‚Ή20,000 urgently. Because there is no payslip coming from a freelancer, or small start ups owner.

This is the exact gap that a new generation of lending apps was built to close. Instead of a salary slip, they read your bank statements, your PAN and Aadhaar history, your UPI transaction pattern, and sometimes your GST filings, and turn that into a credit decision in minutes. 

However, “no salary slip” doesn’t mean “no scrutiny” and it definitely doesn’t mean every app claiming this is safe to use. Below are the Best App To Get Instant Loan Without Salary Slip, let’s see what they actually cost, and how to tell a legitimate lender from a data-harvesting clone before you hand over your Aadhaar.

Why Salary Slips Stopped Being the Only Option

Banks built their lending rules around one kind of borrower: someone with a fixed monthly salary landing on the same date, from the same employer, verifiable on a letterhead. That description fits a shrinking share of India’s workforce. Freelancers, gig-platform workers, small traders, and contract staff earn real, trackable income β€” it just doesn’t arrive in payslip form.

Digital lenders solved this by switching the input. Instead of a payslip, they pull 3–12 months of bank statements to see how much money moves through your account and how consistently. Self-employed applicants can usually substitute ITR filings, GST returns, or business account statements. 

Some apps go further and factor in your digital footprint β€” how long you’ve held your phone number, your UPI activity, even your app usage patterns to build a risk score. None of this is charity; it’s just a different, faster underwriting model, and it’s why approval on these apps can take minutes instead of the two-week wait typical of a bank.

Skipping The Salary Slip Doesn’t Mean The Requirement of Documents Ends

Skipping the salary slip doesn’t mean skipping documentation β€” it just shifts what counts as proof. Across the apps below, the standard ask is a PAN card, Aadhaar for e-KYC, and 3–6 months of bank statements showing regular inflows. 

Self-employed applicants typically add one of: ITR filings for the last one or two years, GST returns if registered, or a business current-account statement. A few apps, like Fibe and mPokket, lean more heavily on alternative signals β€” how long you’ve had your phone number, your UPI transaction frequency, even basic device data β€” specifically for applicants who have no ITR or GST paperwork to show at all. 

None of this is optional paperwork replaced by “trust us” β€” every legitimate lender still needs some way to estimate whether you can repay, it’s just reading your cash flow instead of your employer’s letterhead.

Best Instant Loan Apps Without a Salary Slip Are Listed

1. KreditBee β€” Best for Small, Fast Loans With No CIBIL History

KreditBee lends through Krazybee Services, an RBI-registered NBFC, and is built for speed on smaller ticket sizes. Loan amounts run from about β‚Ή5,000 up to β‚Ή10 lakh, with tenures between 3 and 60 months. 

Interest rates officially start at 12% p.a., but that floor is reserved for the strongest profiles β€” most first-time or thin-file borrowers land closer to 24–29.95% p.a., and self-employed applicants specifically are often quoted in the 16–29.95% range. 

Processing fees can run up to roughly 4–5% of the loan amount, deducted upfront from disbursal. The minimum income requirement is just β‚Ή10,000 a month, and a CIBIL score isn’t mandatory. 

Best for: someone who needs β‚Ή10,000–₹50,000 fast and doesn’t have a credit history yet β€” not for large-ticket borrowing, since the cost climbs fast at that end.

2. Navi β€” Best for Lower Rates and Larger Loan Amounts

Navi, backed by Navi Finserv, is an app to check if your credit score is solid and you need more money for longer. Loan amounts stretch from around β‚Ή10,000 to β‚Ή20 lakh (some listings show up to β‚Ή10 lakh depending on the product), with tenures up to 84 months. 

Rates start near 9.9–9.99% p.a. for borrowers with a CIBIL score of 700+, but can rise to 29–45% p.a. for weaker profiles β€” a wider spread than most competitors, so the advertised low rate isn’t guaranteed. 

Processing fees range from 0% to about 4% plus GST. Both salaried and self-employed applicants are eligible with a minimum score of roughly 650. 

Best for: self-employed borrowers with a decent credit file who want a bigger loan without a bank’s paperwork.

3. Fibe (formerly EarlySalary) β€” Best for Speed

Fibe is an RBI-registered NBFC-P2P platform (license N-13.02139) built around a two-minute approval promise, using an AI model that scans over 100 data points instead of a payslip. Loan amounts go up to β‚Ή5 lakh, rates start at 12% p.a., and it’s known for letting borrowers with no CIBIL score qualify by leaning on digital and social-footprint signals instead. It’s particularly active in Tier-2 and Tier-3 cities where bank branches and traditional documentation checks are less accessible. 

Best for: first-time borrowers who need money today and can accept a higher rate in exchange for near-instant disbursal.

4. PaySense β€” Best for Consistent Self-Employed Income

PaySense, run on PayU Finance India’s lending infrastructure, uses risk-based pricing rather than one flat rate, so two applicants for the same amount can get different offers. Published eligibility asks for a minimum monthly income of β‚Ή18,000 for salaried applicants and β‚Ή20,000 for self-employed ones, with interest rates typically quoted between 14% and 36% p.a. depending on profile. It accepts a low or even zero CIBIL score, which makes it accessible, but that flexibility shows up in the rate you’re offered. 

PaySense is the Best App To Get Instant Loan Without Salary Slip for self-employed borrowers with steady, provable cash flow who don’t yet have a strong credit file.

5. MoneyView β€” Best for Tier-2/Tier-3 Self-Employed Borrowers

MoneyView is frequently the first recommendation for salaried applicants outside metro cities and for self-employed or gig workers who want minimal paperwork. It’s positioned between the small-ticket apps and the larger NBFC lenders, with loan amounts up to around β‚Ή10 lakh and rates generally in the low-to-mid double digits for stronger profiles, rising for thinner files β€” broadly comparable to KreditBee’s range, though it’s often described as steadier on collection practices in user reviews. 

Best for: borrowers outside major metros who want a mid-sized loan without a Tier-1-city credit profile.

6. mPokket β€” Best for Students and Thin-File Gig Workers

mPokket is built specifically for people the traditional system ignores entirely β€” students and gig workers with little or no credit history. Loan sizes are smaller than the others on this list, aimed at short-term, small-amount needs like covering a bill or a temporary cash gap rather than a big-ticket expense. It shouldn’t be treated as a recurring source of funds β€” the sizes and terms make it best suited to occasional, short-duration borrowing. 

Best for: students or new-to-credit gig workers who need a small amount and have nowhere else to turn.

Read More πŸ‘‰ How to Start a Mineral Water Business: Complete Guide

How To Get an Instant Personal Loan Through Paytm, PhonePe, GPay, and Bhim

The same apps you use to split a dinner bill or pay your electricity bill can also get you a loan β€” often within minutes. Here’s how each one actually works:

Paytm

Open the Paytm app, head to the “Loans & Credit Cards” section, and tap “Personal Loan.” Paytm lets you apply anytime for an instant loan online in about two minutes, with a fully digital process and loan amounts ranging from β‚Ή5,000 to β‚Ή15 lakh, flexible tenure, and the option to foreclose anytime. 

Paytm doesn’t lend the money itself β€” it partners with RBI-regulated NBFCs and banks who actually underwrite and disburse the loan. You’ll go through PAN and Aadhaar-based KYC either way.

PhonePe

Same idea, different app. PhonePe doesn’t hand out loans directly β€” it has partnered with various banks and NBFCs to offer instant loans, so you can apply without ever leaving the app.  Loan amounts go up to β‚Ή5 lakh, repayable over tenures of up to 60 months, at rates starting around 13% per annum, with the approved amount transferred straight to your bank account.  Most lenders here look for a stable income and a credit score around 650 or higher.

Google Pay

Google Pay follows the same partner-lending model as Paytm and PhonePe β€” it doesn’t lend directly but connects you to its NBFC and bank partners for a pre-approved or application-based personal loan inside the app, with KYC handled digitally via Aadhaar and PAN.

BHIM

This one surprises people, since BHIM is best known as NPCI’s bare-bones UPI app. But it’s expanded: BHIM now lets you explore a personal loan without leaving the app, again through its network of lending partners rather than lending in-house.

How to Check an App Isn’t a Scam Before You Apply

RBI does not license individual apps β€” it regulates the bank or NBFC behind them. That distinction is the entire safety check:

  • Find the named NBFC or bank. A legitimate app discloses its lending partner clearly in the app, on the Play Store listing, or in the loan agreement. If you can’t find a specific company name, stop.
  • Verify that name on rbi.org.in or the RBI’s Digital Lending Apps directory before you submit any documents.
  • Never pay upfront. Processing fees, “insurance,” or “security deposits” requested before disbursal are the single most common fraud pattern. Legitimate lenders deduct fees from the loan amount after approval, not before.
  • Check what permissions it wants. A real KYC process needs your camera for a selfie and basic identity/banking access β€” not your full contact list, photo gallery, SMS logs, or call history. Apps that demand those are usually building leverage for harassment-based recovery later, not assessing creditworthiness.
  • Look for a Key Fact Statement (KFS). RBI’s digital lending rules require one before disbursal, listing the all-in APR, not just a headline interest rate. A “1% per month” rate can look harmless until the APR reveals fees stacked on top.
  • Confirm a named grievance officer with a phone number and email β€” not just a generic contact form.

If two or more of these are missing, treat the app as a red flag regardless of its Play Store rating, which is not proof of regulatory legitimacy. Because the best app to get instant loan doesn’t mean every app is trustworthy.

Advertising Rate Is Always Different From Actual Amount You Receive in Your Account

Headline interest rates on these apps are quoted per annum, but the real cost shows up in the APR, once processing fees and GST on those fees are added in. A concrete example: on a KreditBee loan disbursed at roughly β‚Ή1 lakh, one published breakdown shows a β‚Ή4,000 processing fee (4%), β‚Ή720 GST on that fee, and β‚Ή10 in documentation charges β€” pushing the effective APR to 29.66%, even though the headline rate for that borrower’s tier read lower. 

The amount that actually lands in the bank account was around β‚Ή95,270, not the full β‚Ή1 lakh. This is exactly what the Key Fact Statement is meant to expose, and it’s why comparing apps on their advertised “starting from” rate alone is close to useless β€” always ask for the APR and the net disbursal amount before accepting an offer, not just the interest rate.

Read More πŸ‘‰ How to Apply for an Education Loan Online

Which App Should You Consider For Instant Personal Loan?

  • If you’re a gig worker or freelancer with no credit history and need a small amount fast, start with KreditBee or Fibe. 
  • If you’re self-employed with steady bank statements and want a lower rate on a bigger amount, check Navi or MoneyView first and let your CIBIL score decide between them. 
  • If you’re a student or new to credit entirely, mPokket is built for exactly that gap, but treat it as a short-term bridge, not a repeat solution. 

Conclusion

WhicheverΒ  Best App To Get Instant Loan Without Salary Slip you land on, run it through the RBI-verification checklist above before you type in your PAN β€” that two-minute check is what separates a fair loan from a very expensive mistake.

The absence of a salary slip requirement is a documentation shortcut, not a signal that the loan is free of risk. A β‚Ή20,000 loan at 28% p.a. with a 4% upfront fee still needs to be repaid on schedule, and missed EMIs on these apps report to CIBIL just like a bank loan would. 

Borrow the amount you need for the problem in front of you, not the maximum the app is willing to approve β€” the higher your sanctioned limit looks, the more tempting it is to take more than the situation actually calls for.

Note: Rates, loan limits, and fees above reflect published figures as of mid-2026 and change frequently based on lender policy and individual credit profile β€” confirm current terms in-app before applying.

Leave a Comment

Your email address will not be published. Required fields are marked *

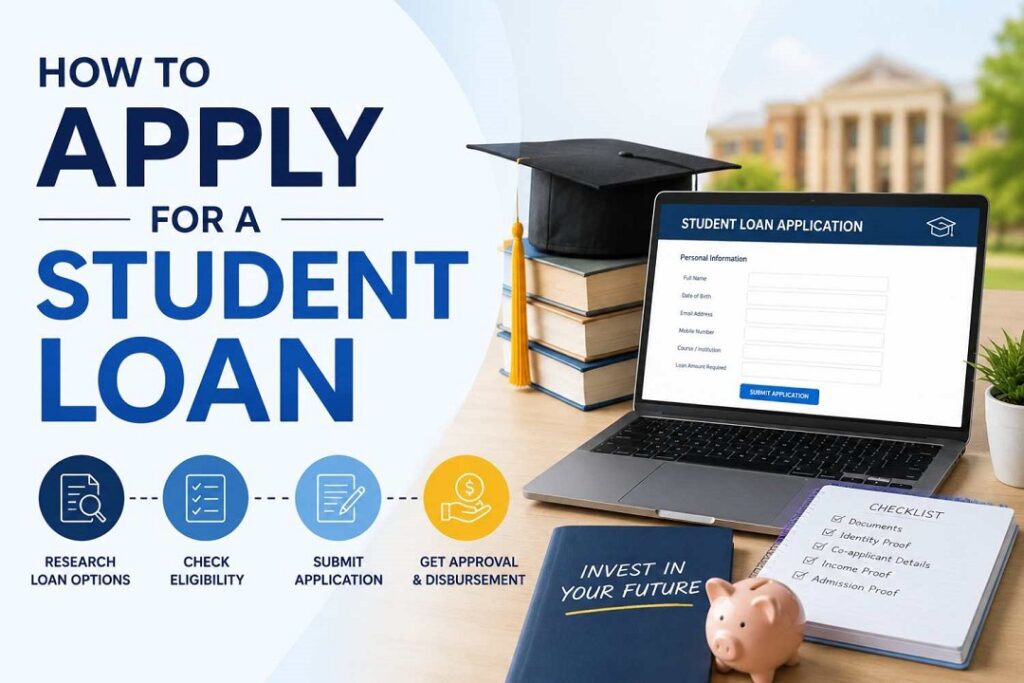
How to Apply for a Student Loan to Get a Higher Education & Make Career

Student Loan

How to apply for a Student Loan doesn’t come randomly in anyone’s mind. Getting into a good college is only half the battle. The other half starts the moment you realize a B.Tech at a decent private university now costs β‚Ή8–15 lakh, an MBA at a tier-2 B-school can run past β‚Ή12 lakh, and a master’s abroad easily crosses β‚Ή40 lakh once you add living costs.Β 

If you don’t have that sort of money lying around, a Student Loan is the only realistic option β€” and how to get one usually determines how much of that money actually gets deposited into your account, and how much you end up overpaying in interest over the next 10 years.Β 

This guide walks through the process as it actually works in India in 2026, not the version that shows up in a bank’s marketing brochure.

How to Apply for a Student Loan Through the Vidya Lakshmi Portal

Almost every organized education loan in India now runs through the Vidya Lakshmi portal, a government-backed single window that connects more than three dozen banks and well over 100 loan schemes to one common form. Instead of visiting five bank branches and filling five different applications, you fill one β€” the Common Education Loan Application Form (CELAF), prescribed by the Indian Banks’ Association and accepted by every participating lender.

The process, in order:

  • Register on the portal with your email ID and a mobile number, ideally the one linked to your Aadhaar, since OTP verification runs through it.
  • Fill the CELAF in sections β€” personal details, course and institution details, cost breakdown, and your co-applicant’s financial information.
  • Upload KYC documents, academic transcripts, and your admission letter in the required digital format.
  • Use the “Search and Apply” tab to filter loan schemes by amount, interest rate, and whether you’re studying in India or abroad.
  • Shortlist and apply to a maximum of three banks in one go β€” a sensible mix is usually one public-sector bank (lower rate, slower processing) and one private bank or NBFC (faster, more flexible).
  • Track status from your dashboard. If a bank marks your application “on hold,” it means they want more documents β€” check the remarks column rather than waiting for an email.

The portal is also linked to the National Scholarship Portal, so if you qualify for a central or state scholarship, you can apply for it in the same sitting.

Where the PM Vidyalaxmi Scheme Fits In

Layered on top of Vidya Lakshmi since 2024–25 is the PM Vidyalaxmi Scheme, a Central Sector Scheme aimed specifically at students who’ve secured admission β€” through merit-based or open competitive selection β€” into a Quality Higher Education Institution (QHEI). The official list currently runs past 800 institutions and keeps expanding as new NIRF-ranked colleges get added, so don’t assume your college qualifies; check the current QHEI list on the portal before you plan around this scheme.

What it actually gets you:

  • No collateral, no guarantor for eligible loans. Some official sources describe this as applying to the entire loan regardless of amount; others cap the collateral-free portion at β‚Ή7.5 lakh, after which the bank may ask for security on the balance. This detail genuinely varies by bank in practice β€” confirm it directly with your chosen lender before you apply, don’t assume either version.
  • A 75% government credit guarantee on loans up to β‚Ή7.5 lakh, which is what makes banks comfortable lending without collateral in the first place.
  • Interest subvention during the moratorium period (course duration plus one year) β€” full interest subsidy if annual family income is up to β‚Ή4.5 lakh, and a 3% subsidy if family income falls between β‚Ή4.5 lakh and β‚Ή8 lakh, both capped at loans up to β‚Ή10 lakh.
  • Above β‚Ή8 lakh family income, you still get the collateral-free structure and credit guarantee β€” you just pay the bank’s normal interest rate with no subsidy.

To claim the subvention, you submit an “intent” declaration on the portal along with income proof from an authorized state government authority β€” it isn’t automatic just because you’re eligible.

Eligibility Criteria You Need to Meet For Student Loan Across Indian Banks

Setting PM Vidyalaxmi aside, general education loan eligibility across Indian banks looks fairly consistent:

  • You need to be an Indian national with confirmed admission to a recognized, full-time regular course β€” part-time and distance programs are excluded by most lenders, though a few NBFCs make exceptions.
  • A co-applicant, almost always a parent or guardian, is required by nearly every bank once the loan crosses a modest threshold (often β‚Ή4 lakh), and their income and credit history factor directly into how much you’re sanctioned.
  • For merit-based schemes like SBI’s Scholar Loan or PM Vidyalaxmi’s QHEI route, your entrance exam rank or admission channel matters as much as your family’s finances β€” these schemes exist precisely to reward the admission, not the collateral.
  • There’s no universal age cap, but banks do informally weigh whether you’re likely to complete the course and start repaying within a reasonable working-age window.

Documents to Keep Ready Before You Apply

Missing paperwork is the single most common reason applications sit in limbo for weeks. Have these ready before you start the CELAF, not after:

  • Admission letter and the institution’s official fee/cost structure
  • Mark sheets for 10th, 12th, and any prior degree
  • Identity proof β€” Aadhaar and PAN at minimum
  • Co-applicant’s income proof: recent salary slips or ITR, and the last six months of bank statements
  • Collateral documents, if your loan amount or scheme requires security
  • Passport and visa copy, if you’re studying abroad

Keep names spelled identically across every document β€” a mismatch between your Aadhaar and your admission letter is a small thing that causes real delays.

How Much Will It Cost You Across Every Sector Banks

Interest rates on Indian education loans in 2026 span a wide range depending on lender type:

  • Public-sector banks (SBI, PNB, Bank of Baroda, Union Bank, Canara Bank) generally price standard education loans between roughly 8% and 10.75% p.a., floating, tied to each bank’s repo-linked or external benchmark rate. As of mid-2026, the RBI repo rate itself sits around 6.25% β€” the actual benchmark moves at each monetary policy review, so treat any quoted rate as a starting point to verify, not a fixed number.
  • SBI’s Scholar Loan, reserved for students admitted to premier institutes like IITs, IIMs, and NITs, runs noticeably lower β€” roughly 6.9% to 7.65% p.a. β€” compared to its regular Student Loan Scheme at around 9.4% to 9.9%.
  • Private banks and NBFCs (HDFC Credila, Avanse, and similar) typically charge 9.5% to 16% p.a. Rates are higher, but sanction and disbursal are usually faster, and many offer larger unsecured amounts.
  • Most public banks give a 0.5% interest concession to girl students β€” worth asking about explicitly, since it isn’t always advertised upfront.
  • Several lenders, including SBI and PNB, offer a 0.5–1% rate discount if you pay simple interest during the moratorium period instead of letting it accumulate. Skipping this is the single most expensive mistake students make: unpaid interest during your study years gets added to the principal, so your EMI ends up calculated on a bigger loan than you actually borrowed.

Claiming the Section 80E Tax Benefit Once You Start Repaying

Once repayment begins, Section 80E of the Income Tax Act lets you deduct the entire interest component of your EMI from taxable income β€” not the principal, just the interest, but with no upper cap, which is unusual among Indian tax deductions.

A few conditions determine whether you actually qualify:

  • The deduction is available for a maximum of eight consecutive years, starting from the year you begin paying interest, or until the interest is fully repaid, whichever comes first.
  • It only applies if you’ve opted for the old tax regime β€” under the new regime, this deduction isn’t available at all, so run the comparison before you file.
  • The loan must come from a recognized bank, financial institution, or an approved charitable institution. A loan from an employer, a relative, or an informal lender does not qualify, no matter how similar the repayment terms look.
  • You can claim it for a loan taken for yourself, your spouse, your children, or a legal ward β€” and it applies whether the course was pursued in India or abroad.
  • You’ll need an interest certificate from your lender each financial year, clearly splitting principal from interest, to actually file the claim.

How To Avoid Application Rejection

A few patterns show up again and again in rejected or delayed applications: 

  • Applying to just one bank instead of shortlisting two or three through Vidya Lakshmi and comparing offers side by side
  • Assuming your college is on the PM Vidyalaxmi QHEI list without checking the current portal listing
  • Letting moratorium interest pile up instead of paying it as simple interest each quarter
  • Submitting documents where your name, date of birth, or address doesn’t match exactly across your Aadhaar, admission letter, and bank KYC.Β 

Each of these is fixable in an afternoon but only if you catch it before submission, not after a bank has already put your file on hold.

Select the Reliable Option for Student Loan

If you’ve been admitted to a QHEI on the current PM Vidyalaxmi list and your family’s annual income is under β‚Ή8 lakh, start there through the Vidya Lakshmi portal β€” the interest subvention alone can save you lakhs over the loan’s life, and it’s the closest thing to free money in this entire process. 

If your institution isn’t on that list, or your loan requirement crosses β‚Ή10 lakh, shortlist two or three public-sector banks, compare their post-moratorium rates head-to-head, and ask each one directly what your EMI looks like once the subsidy or discount period ends. Not the headline interest rate but that one question is where most students get blindsided.

Conclusion 

The paperwork for Student Loan application is simpler once you have your documents in order, have compared lenders and know the government schemes that apply to you. Vidya Lakshmi portal provides students a one-stop shop to apply for education loans and also compare the loans, while PM Vidyalaxmi can help eligible students by lightening their financial load through interest support and collateral-free loans.Β 

Before you accept any offer, look beyond the stated interest rate. Check the terms of the moratorium (temporary period in which you don’t have to start paying the regular EMI), your eligibility for subsidy, the amount you need to repay, the amount of collateral required and the total interest you will pay. A bit of comparison before signing can make a big difference to your finances after you graduate.

Leave a Comment

Your email address will not be published. Required fields are marked *

Apple iPhone Duo Changes the Cost Effectively With These Methods

Apple iPhone

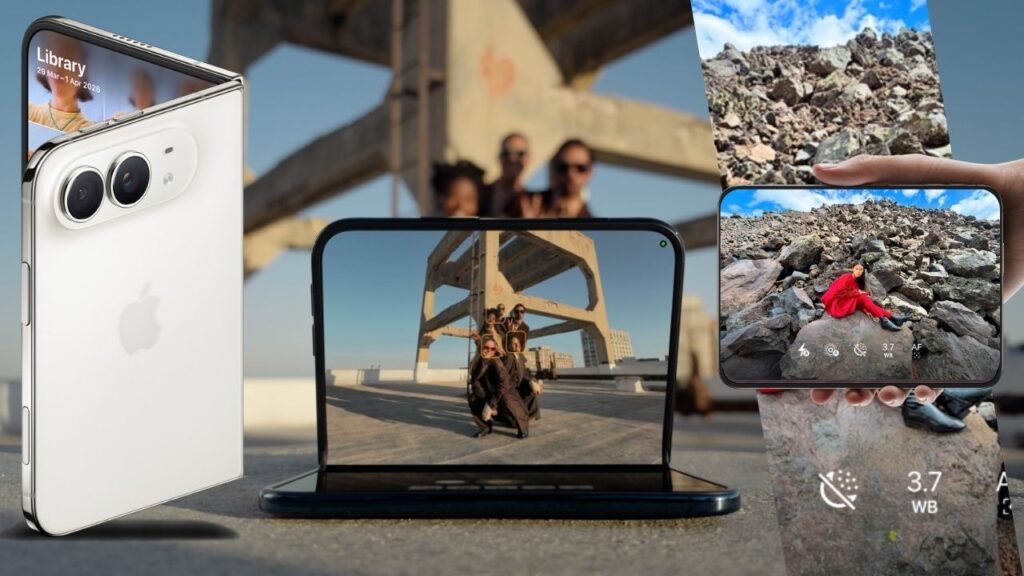
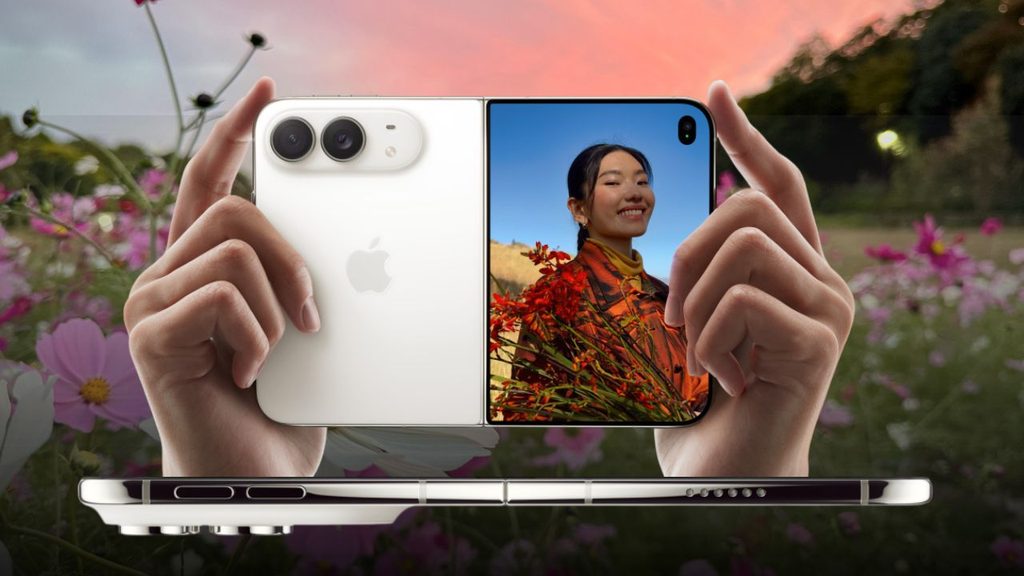
The Apple’s iPhone Duo is unlike any iPhone before with foldable versatility and 50% larger screen than iPhone 18 Pro Max. Apple iPhone Duo price started at β‚Ή2,99,900 for a base 256GB model. The EMI run down to β‚Ή48,817 a month sounds almost manageable until you realise that’s just for the base model if you want more space, the cost is going higher.

The top 2TB configuration crosses β‚Ή4,49,900, either way, Apple’s first foldable is the most expensive iPhone the company has ever sold in India, and pre-orders open at 5:30 PM IST on October 16, with units shipping from October 23. 

Between No Cost EMI, card cashback, and trade-in credit, there are real ways to bring the effective cost down, and just as many ways to misread the fine print and end up paying more than you expected. 

What the Apple iPhone Duo Costs in India

Apple has published pricing for all four storage tiers of the Duo:

  • 256GB β€” β‚Ή2,99,900
  • 512GB β€” β‚Ή3,24,900
  • 1TB β€” β‚Ή3,74,900
  • 2TB β€” β‚Ή4,49,900 

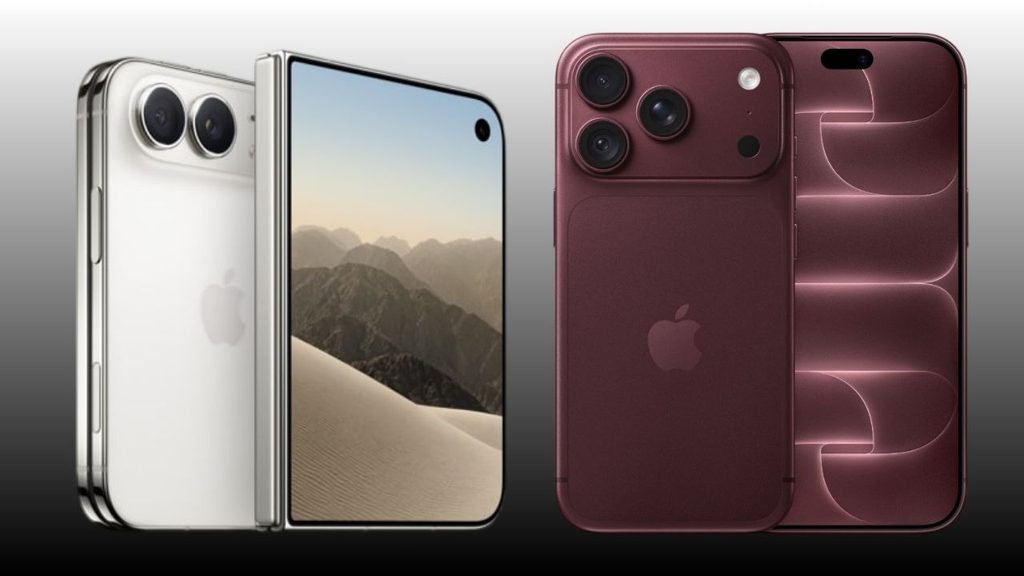
The iPhone 18 Pro starts at β‚Ή1,64,900 and the iPhone 18 Pro Max at β‚Ή1,79,900. The Duo’s entry price is roughly β‚Ή1,35,000 above the Pro β€” not a small step up, and one reason Apple’s foldable debut in India has drawn as much attention for its billing as for its 7.6-inch inner display and A20 Pro chip. 


Unlike the standard iPhone 18 line, the iPhone Duo isn’t manufactured locally, so import duty and GST land on top of a device that already costs more to make. In the US, the same phone starts at $1,999 (roughly β‚Ή1.7 lakh at the going exchange rate) β€” a reminder that Indian pricing on the Duo carries a heavier markup than usual, even by iPhone standards.

Apple iPhone Duo EMI: What Costs You Per Month

Apple’s No Cost EMI on the Duo runs over 3 or 6 months through most major card issuers β€” noticeably shorter than what Apple offers elsewhere. The US gets 24-month Apple Card Monthly Installments at roughly $83/month; the UK gets 30 months at 0% APR, working out to about Β£67/month. India’s 6-month cap is the shortest interest-free tenure Apple offers on the Duo anywhere, which is exactly why the monthly number here looks so heavy.

Published monthly EMI figure against each storage tier, and what six payments actually add up to versus the list price:

StorageMonthly EMI6-Month TotalSavings vs List Price
256GBβ‚Ή48,817β‚Ή2,92,902β‚Ή6,998 under
512GBβ‚Ή52,983β‚Ή3,17,898β‚Ή7,002 under
1TBβ‚Ή61,317β‚Ή3,67,902β‚Ή6,998 under
2TBβ‚Ή73,817β‚Ή4,42,902β‚Ή6,998 under

The Cashback Catch: β‚Ή15,000 Sounds Bigger Than It Is

Apple India advertises “up to β‚Ή15,000 instant cashback” across its entire store for customers using eligible American Express, Axis Bank, or ICICI Bank cards. That β‚Ή15,000 is a store-wide ceiling β€” it’s not a number attached to the Duo, or to any single product. 

Run the EMI math above and the actual deduction baked into Apple’s Duo pricing lines up with β‚Ή7,000, the same figure that’s been reported for the iPhone 18 Pro launch offer. Budget for that, not for β‚Ή15,000.


A few conditions apply regardless of which figure you’re chasing:

  • Minimum transaction value of β‚Ή10,001
  • Maximum two qualifying orders per rolling 90-day period
  • Not available to Business Store customers, and can’t be stacked with Education or Corporate Employee Purchase Plan pricing
  • Apple India explicitly reserves the right to revise or withdraw these terms without notice 

Apple hasn’t published a cashback figure specific to the Duo, a list of exactly which card variants qualify, an AppleCare+ price for the folding display, or what a screen repair would cost outside warranty. If any of those numbers matter to your decision, wait for the October pre-order.

Read More πŸ‘‰ Your Dollar Income Isn’t Fixed: How INR Volatility Changes Freelancers Earning 

Turning Your Old iPhone Into a Down Payment

Apple’s exchange program advertises “save up to β‚Ή62,000” when you trade in an eligible smartphone β€” available both online and in-store. Treat that β‚Ή62,000 as a ceiling for a high-end device in excellent condition, not a number your specific phone will hit. 

A three-year-old iPhone with a cracked back glass is not pulling anywhere near that figure. If trade-in is central to your plan, get an online valuation for your exact device and condition before pre-order day, so you’re not recalculating your budget at checkout.


Third-party platforms like Cashify have historically run parallel exchange bonuses on top of card-linked EMI offers β€” ICICI’s Instant EMI programme has combined a 24-month deferred payment structure with additional exchange bonuses up to β‚Ή6,000 on older iPhone models. 

The ICICI offer terms currently list iPhone 16 and 17-series devices, not the Duo. It’s reasonably expected that Duo-specific versions of these programmes will show up once pre-orders open.

Where You Can Buy Apple iPhone Duo

Apple India’s own store β€” with UPI, net banking, and EMI on eligible cards β€” is the confirmed channel from October 23. Authorized Apple resellers and large retail chains are expected to carry it too, based on how Apple has rolled out every recent flagship. 

Amazon and Flipkart listings are widely expected to go live around the launch window, though neither platform has published Duo-specific financing or exchange terms as of now. 

If a Bajaj Finserv No Cost EMI card or a Flipkart-specific bank offer matters to your plan, that’s one more thing to check on launch day rather than assume.

Apple iPhone Duo vs iPhone 18 Pro Max: Is the Jump Worth Financing?

The comparison that actually matters for your wallet isn’t Duo-to-Duo storage tiers β€” it’s Duo versus the iPhone 18 Pro Max, since that’s the next phone up in Apple’s current India lineup.

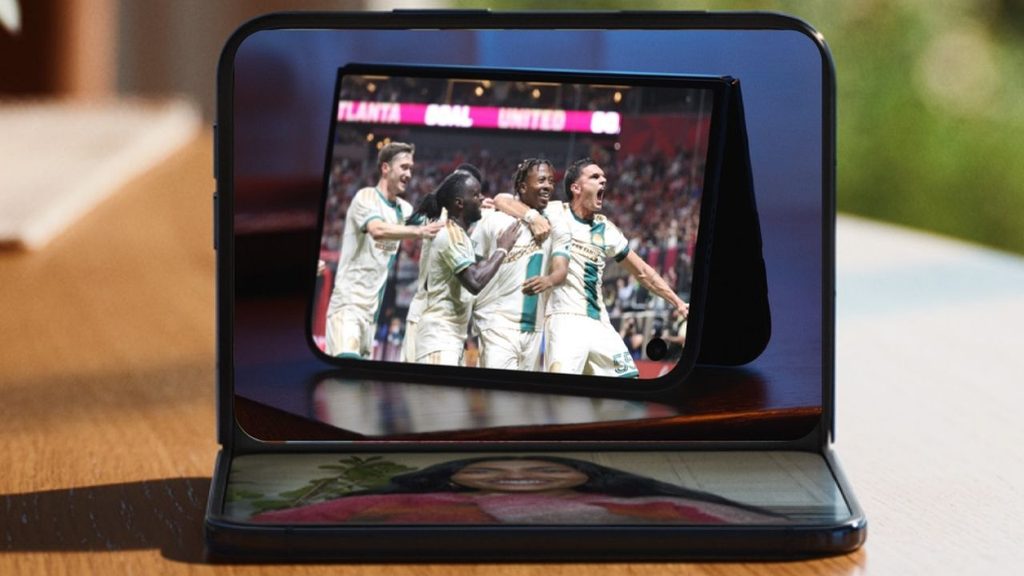
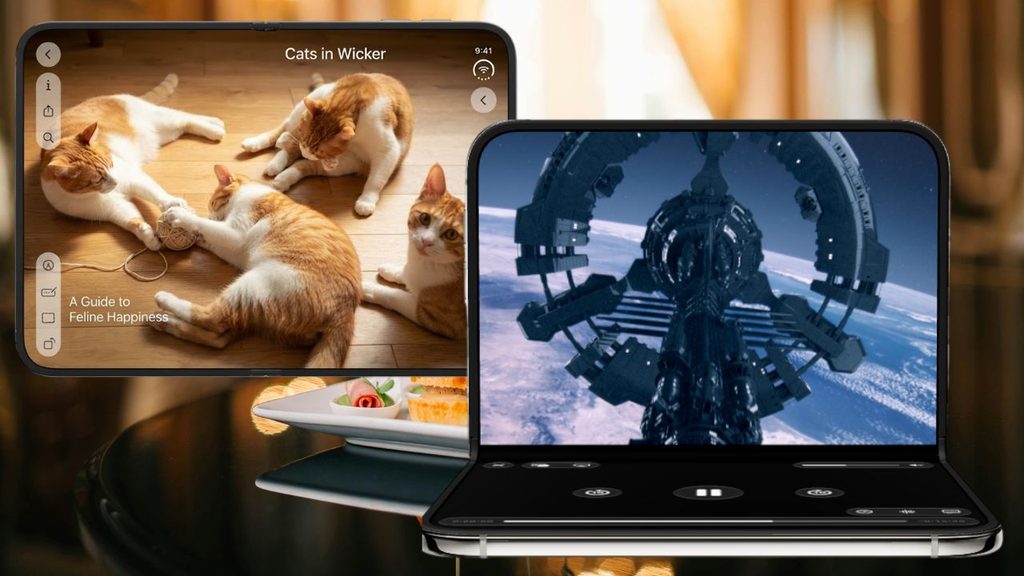
The iPhone 18 Pro Max starts at β‚Ή1,79,900, less than two-thirds of the Duo’s β‚Ή2,99,900 entry price, and runs on the same A20 Pro silicon. What you’re paying the extra β‚Ή1,20,000 for is the fold itself: a 7.6-inch inner display Apple says is 50% larger than the Pro Max screen, a 5.4-inch cover display carrying over 90% of the Pro Max’s screen area when closed, and software in iOS 27 built specifically to adapt across open, half-folded, and closed states β€” split-screen Safari and Siri-driven multitasking that the Pro Max’s single flat screen can’t replicate.


That’s the real difference between these two smartphones. It’s a much harder case to make if your actual use is calls, camera, and social media, where the Pro Max’s flat 6.9-inch OLED does the job for a lot less money and without a hinge to eventually worry about. If the fold itself isn’t pulling you toward the Duo, the EMI math above becomes a much easier decision: skip it.

There’s also a first-generation-hardware question worth asking before you commit six months of EMI to it. The Duo’s hinge uses more than 100 parts and a magnet array to snap shut, sits under a titanium frame, and pairs Ceramic Shield 2 on the outer front with regular Ceramic Shield on the back β€” Apple’s most reinforced build on any iPhone. That’s a serious engineering effort, but it’s also Apple’s first attempt at a folding mechanism, with no multi-year track record the way the flat-screen Pro Max has.Β 

If you’ve never owned a folding phone and are financing this on EMI you can’t easily walk away from, it’s worth being honest about whether you’re the kind of owner who’ll baby a hinge for two years, or the kind who’ll drop it once every four months.

Read More πŸ‘‰ Foreign Education Loan Currency Explained: How INR Depreciation Can Increase Your Loan Cost 

Apple’s eSIM-Only & 31 Hours Battery Power Doesn’t Affect On Duo Costs

The Apple iPhone Duo has no physical SIM tray, anywhere in the world. Every line runs on eSIM, with two eSIMs active at once and room to store eight or more profiles. Apple says this is part of why the phone manages up to 31 hours of video playback on the inner display and up to 44 hours on the outer one β€” the tray took up space that now goes to the dual-battery system instead.

That’s not a deal-breaker in India, where Jio, Airtel, and Vi have supported eSIM on postpaid and select prepaid plans for years. But it does mean two things worth planning around before you finance a β‚Ή3-lakh phone. 


First, if you’re switching from an Android phone with a physical SIM, you can’t just pop the card across β€” you’ll need to get an eSIM profile issued by your carrier, which usually means a store visit or an app-based request, not an instant swap. 

Second, if your trade-in plan involves handing over your current iPhone the same day you activate the Duo, do the eSIM transfer before you box up the old phone, not after β€” Apple’s eSIM Quick Transfer works phone-to-phone, but only while both devices are in hand. Neither issue affects what the Duo costs, but both affect how smoothly your launch-day purchase goes, and a botched activation is a bad way to start a 6-month EMI commitment.

Read More πŸ‘‰ SSC CPO SI CAPF Online Form 2026

Conclusion β€” Which Financing Route Fits You?

If you’ve got a recent flagship iPhone to trade in for Apple iPhone Duo, exchange + EMI is your cheapest real path β€” get the online trade-in estimate first, then layer 6-month No Cost EMI with an eligible Axis, ICICI, or Amex card on whatever balance is left.

If you don’t have a trade-in and want the lowest monthly hit, 6-month EMI beats 3-month by roughly half the monthly outflow for the same total cost β€” there’s no financial reason to choose the shorter tenure unless your card’s credit limit forces it.

If you’re on the fence about needing the fold at all, the iPhone 18 Pro Max buys you the same chip and most of the camera capability for β‚Ή1,20,000 less, with a financing plan that’s easier on the wallet either way.

And if none of the current numbers work for your budget, waiting past October 16 costs you nothing β€” Apple, Amazon, and Flipkart have all historically added deeper festive-season offers on new iPhone within weeks of launch, and the Duo’s card-specific cashback terms are explicitly subject to change before then.

Leave a Comment

Your email address will not be published. Required fields are marked *

Your Credit Score Ignores 90% of Your Financial Life β€” What Your First Credit Card ChangesΒ 

Credit Score

Once your first credit card is approved, you probably think that you are eligible for loan or finance. But you’re wrong because your credit score matters and it is built from repayment history not from your financial status or expenses. There are four active bureaus (CIBIL, Experian, Equifax, CRIF High Mark) in India and they all sit between 300 and 900 score. 

And it doesn’t know your salary, your savings account, your mutual fund SIPs, or the fact that you’ve never once missed a rent payment. It tracks exactly one thing closely: how you’ve handled borrowed money. 

That gap between what the score sees and what your financial life actually looks like is where most first-time cardholders get caught off guard.

What Your Credit Score Measures in Your Financials

A score is built almost entirely from repayment behavior. FICO, the US model most bureaus borrow their logic from, publishes its weighting: payment history (about 35%), credit utilization (about 30%), length of credit history (about 15%), credit mix (about 10%), and new credit inquiries (about 10%). 

It breaks it down, the ingredients look roughly like this:

  • Payment history β€” whether you’ve paid EMIs and card bills on time. This carries the heaviest weight, often estimated at around 30-35%.
  • Credit utilization β€” how much of your available credit limit you’re actually using. Maxing out a card, even if you pay it off in full, can quietly hurt you. 
  • Length of credit history β€” how long your oldest active account has been open. This is exactly why closing your first credit card years later can lower your score instead of helping it. 
  • Credit mix β€” a blend of secured loans (car, home) and unsecured ones (credit cards, personal loans) reads better than having only one type. 
  • New credit inquiries β€” every time you apply for a loan or card, a “hard inquiry” gets logged, and too many in a short window signals risk to lenders. 

CIBIL doesn’t publish its exact formula, but the underlying behavior it rewards and punishes is the same. None of this touches your bank balance. It only starts once you’ve borrowed something β€” a loan, an EMI, a credit card and shows how consistently you paid it back.

Read More πŸ‘‰ Best App To Get Instant Loan Without Salary Slip

The 90% of Credit Score Never Sees Your Financial Life

Your salary doesn’t appear on your first credit card report. Neither does your savings balance, your fixed deposits, your stock or mutual fund portfolio, property you own, freelance or side income, or rent you’ve paid on time for years (unless you’ve specifically enrolled in one of the newer rent-reporting services, which are still rare in India). Utility bills and UPI spending don’t count either, since none of that is borrowed money. 

This cuts both ways. Someone with a strong income and zero loans can be “credit invisible” β€” no score at all, simply because they’ve never borrowed. Someone drowning in personal debt but paying the minimum on time every month can carry a technically decent score while their actual finances are falling apart. The number reflects repayment discipline, not net worth.

Why This Number Still Runs Your Financial Life

Even though it’s a narrow measurement, it’s the one lenders trust most. A home loan applicant with a score above 750 might get an interest rate a full percentage point lower than someone below 650 β€” on a 20-year loan, that gap alone can add up to lakhs of rupees in extra interest. 

Your score also decides which credit cards you qualify for and what limit you’re offered, and in some sectors β€” finance, banking, occasionally government roles β€” employers run a credit check as part of background verification. 

Landlords in a few metro markets have started asking for credit reports too. None of that is about how much you earn. It’s entirely about whether you’ve paid back what you owed, on time, before.

The Mistakes That Wreck a First-Time Cardholder’s Score

Paying Only the Minimum Due

The minimum due usually around 5% of the outstanding bill β€” keeps your account technically current, but the remaining balance starts accruing interest immediately, typically in the range of 3 – 3.5% a month, which works out to somewhere near 36–42% annualized. It’s one of the most expensive ways to borrow money that exists, and the balance compounds faster than most first-time users expect.

Maxing Out the Limit

Spending close to your full limit every month signals risk to lenders, even if you clear the bill in full. Keeping usage under roughly 30% of your available limit protects the score far more than people assume β€” this is often a bigger factor than the actual bill amount.

Applying for Multiple Cards in the First Year

Every new application triggers a hard inquiry, and each one dents the score slightly while sitting on your report for a couple of years. Several applications close together read to lenders as credit hunger, not creditworthiness.

Missing the Due Date, Even Once

A single day late usually just costs a late fee. But once a payment crosses roughly 30 days overdue, it typically gets reported to the bureau and that single entry can move the score sharply and stay visible for years.

Closing the Card Too Early

Shutting down  your first credit card within the first year shortens your average credit age, which is one of the more underrated factors in the score. A longer, active history β€” even on a card you barely use β€” tends to help more than starting fresh with a new one.

Read More πŸ‘‰ How to Apply for an Education Loan Online

The Right Way to Spend From Your First Card

Treat it like a debit card with a receipt trail, not free money. Pick one or two recurring expenses β€” a mobile recharge, one subscription, fuel and route them through the card on autopay. This builds a steady, low-risk repayment pattern without tempting you into overspending. 

Pay the full statement balance every cycle, not the minimum. Check your statement monthly for errors or unfamiliar charges. Avoid withdrawing cash on the card entirely β€” interest usually starts from the day of withdrawal with no grace period, on top of a flat fee near 2.5–3%. 

And think twice before converting purchases to EMI, even “no-cost” ones; the discount you’d have gotten on the outright price is often quietly folded back into the total.

How Fast Can a Credit Score Really Move?

Scores don’t jump in percentages β€” there’s no such thing as a score rising “by 90%.” They move in points, and how fast depends on which factor you’re fixing. 

Utilization moves quickest: pay down a high balance before your statement date, and the next reporting cycle, usually 30 to 45 days later, can reflect a meaningful jump, sometimes 50 or more points on the 900-point scale, because utilization updates almost as fast as your balance does. 

Payment history moves slower and compounds instead: one on-time payment barely registers, but six to twelve months of consistent on-time payments builds a track record lenders actually trust. Bureau errors β€” a closed loan still showing as open, a paid card marked as defaulted, can also produce a fast correction once flagged, sometimes within a single reporting cycle. 

For someone starting with a thin or nonexistent credit file, a workable, lender-friendly score in six to twelve months of disciplined use is a realistic target. Overnight is not.

Before Cardholder Swipe That First Time

Pull your free annual report from the bureau and note your starting number before you spend a single rupee. Set autopay for the full statement amount, not the minimum, and add a separate calendar reminder a few days before the due date as backup. 

Pick one recurring bill to run through  your first credit card and leave the rest alone for now. Then check the number again in three months, not three weeks β€” that’s roughly how long it takes the system to actually reflect what you did.

Read More πŸ‘‰ Business Ideas for Students With Zero Investment β€” Easy Startup Guide

Conclusion

Your financial health doesn’t increase your Credit Score and it is important to maintain that score. It’s a way for lenders to understand how responsibly you’ve handled borrowed money, not how much you earn, save, invest, or own.Β 

For a first-time cardholder, utilization should be lower, pay the statement balance on time, do not fill unnecessary applications, be patient and give time for your credit history to grow. Treat your first credit card as a tool for building trust with lenders, so when you actually need a bigger loan or good credit, you can get it easily. 

Leave a Comment

Your email address will not be published. Required fields are marked *

Scroll to Top