IIT BHU Non-Teaching Recruitment 2026 โ€” Vacancy and How to Apply

IIT BHU Non-Teaching Recruitment

IIT BHU Non-Teaching Recruitment 2026 is currently live, visit official website to fill the form. The online application time will end on 01/October/2026. It is conducted by the Indian Institute of Technology (Banaras Hindu University), Varanasi to fill 55 regular vacancies across various administrative, technical, engineering, library, and Rajbhasha cadres.

Candidates who are eligible for this recruitment can apply but make sure that you must have official educational documents in hand before applying. Other necessary documents are also required during filling the application.

ItemDetail
OrganizationIndian Institute of Technology (Banaras Hindu University), Varanasi
Total vacancies55 posts (Group B & C)
Application modeOnline via SAMARTH portal only
Online application window25 Aug 2026 โ€“ 01 Oct 2026, 5:00 PM (last date extended)
Physical copyMandatory: printout + documents by Speed Post within 7 days of last date
SelectionShortlisting + possible Screening/Written Test, GD, Presentation, Interview (as per post)
Nature of appointmentRegular with probation; institute may offer on contract basis in some cases

Application Fee

Post GroupGeneral / EWS / OBC (Male)SC / ST / PwBD / All Female
Group B (e.g., Junior Superintendent, Assistant/Junior Engineer, JTO)โ‚น500Nil
Group C (e.g., Junior Technician, Junior Library Assistant)โ‚น250Nil

Essential Qualifications Required For IIT BHU Non-Teaching Recruitment 

The eligibility criteria depends on the posts you are applying for because it requires knowledge in that particular area. 

  • Bachelor’s degree in any discipline with at least 55% marks for a Junior Superintendent and supervisory experience also required (3 years at Level 5 or equivalent). 
  • Bachelor’s degree in B.Sc. or B.E./B.Tech or a Diploma in engineering with at least 55% marks for Junior Technician is required. But Diploma holders must also have 1 year of experience in the same field. 
  • Civil Engineering post sets a rule that candidate must qualify B.E./B.Tech or 3-year Diploma in engineering and an experience certificate.
  • To apply for Assistant Engineer, you must have a B.E./B.Tech or Diploma in Civil/Electrical Engineering with extensive experience (5โ€“8 years). 
  • You are required for Bachelor’s/Diploma in Library & Information Science with 55% marks to Junior Library Assistant post. 

Read Also ๐Ÿ‘‰ RRB NTPC 2026 Online Form: Graduate and UG Level Dates, Vacancies, and How to Apply

IIT BHU Non-Teaching Recruitment 2026 Vacancy Breakdown (post-wise)

Post NameCadreGroupPay Level (7th CPC)VacanciesUpper Age Limit
Junior SuperintendentAdministrativeBLevel 621 35 yrs
Junior Technician (Group-I: Chemistry/Physics)TechnicalCLevel-34 27 yrs
Junior Technician (Group-II: Mech/Met/Ceramic/Mat Sci)TechnicalCLevel-311 27 yrs
Junior Technician (Group-III: Electrical/Electronics)TechnicalCLevel-33 27 yrs
Junior Technician (Group-IV: Civil/Arch/Mining)TechnicalCLevel-34 27 yrs
Junior Technician (Group-V: CSE/IT/CCIS)TechnicalCLevel-34 27 yrs
Junior Library AssistantLibraryCLevel-3230 yrs
Assistant EngineerEngineeringBLevel 82 40 yrs
Junior EngineerEngineeringBLevel 63 35 yrs
Junior Translation OfficerRajbhashaBLevel 61 35 yrs

Selection Process IIT BHU Non-Teaching Recruitment

The selection process typically includes an initial screening of applications, based on online data. Shortlisted candidates may be called for Written Test / Skill Test / Presentation or Interview (depending on the post requirements) and document verification. 

Schedules will be sent only by email to registered IDs; no hard copies. Visit the official website of the IIT BHU to check the lists of shortlisted/non-shortlisted candidates. The reason is also mentioned there for your status. 

How to Apply (step-by-step)

  1. Go to SAMARTH portal: https://iitbhunt.samarth.edu.in if you wanna apply for IIT BHU Non-Teaching Recruitment 2026.
  2. Register โ†’ fill personal, educational, and experience details carefully (no edits after submission).
  3. Upload photo/signature and required documents.
  4. Pay application fee (if applicable).
  5. Submit online by 01 Oct 2026, 5:00 PM.
  6. Take a printout of the submitted form.
  7. Now you have to send that printout along with copies of your required qualification documents and experience certificate by courier to the Registrar, IIT (BHU), Varanasi โ€“ 221005. Application No., Advertisement No., and Post Name & Code must be written on the envelope.
  8. If youโ€™re a serving Govt/Autonomous/Educational employee, ensure your application is forwarded through Proper Channel within 7 days of the last date; upload NOC & Vigilance Clearance (or produce at interview).

Read Also ๐Ÿ‘‰ Festive Season Sale In October Is About to Reshape Smartphone Prices in Indiaย 

Conclusion 

IIT BHU Non-Teaching Recruitment 2026 drive is on-going on an official portal. Apply now or youโ€™ll miss the deadline, but check your eligibility before applying and download the official notification for more deeper details. The vacancy breakdown is given so you can guess the competition level for your exam.
Leave a Comment

Your email address will not be published. Required fields are marked *

Best Lightweight Sunglasses for Student Lifeย 

Sunglasses

A pair of sunglasses in a college backpack is a choice of your comfort. When the college campus is large and you need to walk in direct sunheat or you go out randomly somewhere with your friends and your eyes start to burn in the heat. Thatโ€™s where you start hunting for Best Lightweight Sunglasses for students, the best is the one which gives you comfort, weightless, and perfect for your face.

What Actually Matters for Campus-Ready Sunglasses

Frame weight comes down to material, not brand name. TR-90 and polycarbonate frames flex instead of snapping when they get crushed in a bag, and they sit lighter on the nose during a three-hour library stretch than metal or thick acetate does. UV protection โ€” specifically UV400 โ€” isn’t optional no matter how cheap the pair is; it’s the one spec that protects your eyes rather than your outfit. 

Polarization is worth paying a little more for if you’re on a bike or scooter daily, since it cuts glare off wet roads and car windshields far better than plain tinted lenses. And because these things get lost, borrowed by roommates, or sat on at least once a year, price-to-replacement-cost matters more here than it would for a pair you’d baby at home.

The 5 Best Lightweight Sunglasses for Students 

1. Fastrack Polarized Wayfarers and Aviators

Price: โ‚น950โ€“โ‚น5,000 | Frame: TR-90 polycarbonate | Lens: UV400, polarized options | Best for: tightest-budget daily wear


Fastrack’s entry-level polarized range starts under โ‚น1,000 and still comes with a 1-year warranty on lenses and frames, which is unusual at that price point. The TR-90 build is genuinely flexible โ€” it survives the kind of backpack abuse a rigid acetate frame won’t. The trade-off is build quality at the very bottom of that price range: some buyers report the cheapest models feeling plasticky compared to what โ‚น2,000+ gets you in the same lineup. Good for someone who wants a backup pair as much as a main one.

2. Vincent Chase by Lenskart

Price: From โ‚น999, polarized from โ‚น1,299 | Frame: TR90 | Lens: 100% UV protected, polarized | Best for: best value-for-money on a first “real” pair


Vincent Chase is Lenskart’s in-house line, and it’s built around the same TR90 material for the same reason โ€” daily wear without weight. The advantage over Fastrack is availability: Lenskart runs frequent Buy 1 Get 1 offers on this line, which effectively gets you a backup pair for the price of one. The catch is that heavy discounting means style availability shifts often, so a specific frame you like online today may not be there in three months if you need a replacement in the exact same shape.

3. OPIUM Eyewear

Price: โ‚น1,500โ€“โ‚น5,000 | Frame: lightweight polycarbonate | Lens: UV400, polarized, AVS coating | Best for: students who scratch or drop glasses often


OPIUM’s AVS lens coating adds hydrophobic, oleophobic, and anti-static properties on top of standard UV/polarized protection โ€” practically, that means fewer smudges from fingerprints and better scratch resistance when the lenses rub against keys or coins loose in a bag. It sits a notch above Fastrack and Vincent Chase in price, which is the real trade-off: you’re paying for lens durability, not a jump in style tier.

4. IDEE

Price: โ‚น899โ€“โ‚น1,499 | Frame: lightweight, sporty builds | Lens: UV protected | Best for: gym, sports, or an active daily commute


IDEE leans into bold, sporty designs โ€” wraparounds and neon accents rather than classic wayfarer shapes โ€” and stays cheap while doing it. If your daily routine includes a run, a cycle to campus, or intramural sports, the closer-wrap fit holds better than a flat wayfarer frame. The limitation is versatility: the sportier shapes don’t double as well for a formal event or an internship interview the way a classic frame does.

5. Ray-Ban (Aviator / Wayfarer)

Price: roughly โ‚น7,000โ€“โ‚น15,000 depending on style and retailer | Frame: acetate/metal | Lens: UV400, optional polarized | Best for: one pair meant to last through all four years

Ray-Ban is the outlier on this list by price, and it’s here for a specific reason: it’s the one pair that isn’t disposable. The Original Wayfarer and Aviator have been in continuous production since 1952 and 1937 respectively, which means replacement parts, nose pads, and repairs are easy to find at any optician years later โ€” something none of the budget brands above can promise. It only makes sense if you can absorb the upfront cost and genuinely won’t be swapping styles every semester.

The Real Face-Off of Fastrack & Vincent Chase 

These two get compared constantly because they’re the two brands most students actually cross-shop, so here’s the direct read:

FastrackVincent Chase
Entry priceโ‚น950โ‚น999
Polarized entry priceIncluded in mid-rangeFrom โ‚น1,299
Warranty1 year (lens + frame)Standard return window, no stated 1-yr warranty
Where to buyFastrack’s own site, Titan Eye+, Flipkart, Tata CLiQLenskart, Amazon.in
Recurring offersOccasional salesFrequent Buy 1 Get 1

If warranty coverage matters more to you than getting two pairs, Fastrack wins. If you’d rather have a spare pair sitting in a drawer for when the first one inevitably gets sat on, Vincent Chase’s BOGO structure is hard to beat on pure economics.

Which One Should You Actually Buy?

If your budget is genuinely under โ‚น1,200 and you just need something functional for the sun on your walk to class, get the Fastrack or Vincent Chase entry model โ€” there’s no meaningful difference in daily performance between them at that price. If you’re riding a two-wheeler daily, prioritize a polarized lens over anything else on this list; glare off a windshield or wet road is a real safety issue, not just comfort. 

If you’re the person who’s cracked three pairs of earphones and lost two water bottles this year, don’t buy OPIUM or Ray-Ban โ€” buy the cheapest polarized Fastrack you can find and expect to replace it. And if you’ve got one splurge in your accessory budget for the year and want something that’ll still be wearable at your graduation photos, the Ray-Ban is the only pair on this list built to actually last that long.

One habit that extends your sunglasses lifespan โ€“  a hard case, not the soft pouch that comes in the box. Most lens scratches on student sunglasses don’t happen while wearing them, they happen loose in a bag next to keys and a laptop charger.

Read More๐Ÿ‘‰ iPhone 18 Pro on EMI: A Complete Buying Guide

Conclusion

The Best Lightweight Sunglasses for Everyday Student Life arenโ€™t always expensive. Whatever you opt for, be sure toโ€‚focus on UV400 protection, a lightweight frame, a comfortable fit, and polarization for when glare is an issue. Toss a hard case In Addition your backpack, andโ€‚even a modest pair can make it through life on the daily grind of college. Pocket your case for your backpack and even a thrifty pair can easily keep up with daily college life.ย 

Leave a Comment

Your email address will not be published. Required fields are marked *

Collateral vs No Collateral Loan Amount Where Collateral Starts Making Financial Sense

Collateral vs No Collateral Loan

Ask most people whether a secured loan beats an unsecured one, and they’ll say yes without blinking โ€” lower interest rate, obviously better. That’s the assumption. It’s also where the math quietly falls apart, because a lower rate on paper doesn’t always mean a lower cost in your pocket. Donโ€™t get confused about Collateral vs No Collateral Loan, understand where it matters.

Whether collateral actually saves you money depends on how much you’re borrowing, and more specifically, on what kind of asset you’re pledging to get that lower rate.

This isn’t a “secured is always cheaper” point. It’s about the exact moment moves depending on the collateral where the interest-rate discount stops being eaten alive by fees, valuation costs, and paperwork.

What Changes When You Add Collateral to a Loan

A collateral loan amount decision comes down to three things shifting at once, not just the rate.

The interest rate drops, because the lender’s risk drops. If you default, they recover the loan by selling or auctioning the pledged asset. As of late 2026, unsecured personal loans in India typically run 11โ€“18% per year for a reasonably qualified borrower, and unsecured business loans usually start closer to 16%. Gold loans from banks price between roughly 8.5% and 12%, and loans against property (LAP) generally fall between 8.5% and 14%, though NBFC gold loans for weaker profiles can climb well past 20%.

Fixed costs show up that don’t exist on an unsecured loan. Asset valuation, legal verification, mortgage registration, sometimes insurance on the pledged asset. These are flat charges โ€” they don’t scale down for a small loan the way percentage-based interest does.

Your money moves slower, and your asset stops being liquid. A personal loan can land in your account same-day. A property-backed loan needs valuation, title checks, and registration, which can take one to three weeks. During that time, and for the life of the loan, that asset is off the table if you need to sell it, gift it, or use it as collateral again elsewhere.

That third point is the one people underweight, and it matters more as the loan amount grows, not less which is part of why there’s no single “collateral is worth it above this number” answer.

The Real Threshold Depends on Which Asset You’re Pledging

The breakeven point isn’t one number in Collateral vs No Collateral Loan. It’s a different number for every type of collateral, because the fixed costs attached to each one are wildly different.

Gold or fixed-deposit collateral has almost no fixed-cost floor. A gold loan can be sanctioned in under an hour, valuation is done on the spot, and processing fees run 0.25โ€“1% of the loan amount โ€” often just a few hundred rupees on a small ticket. Because there’s barely any fixed cost to clear, a gold loan can make financial sense on amounts as small as โ‚น50,000โ€“โ‚น1 lakh. The rate gap versus an unsecured loan (often 4โ€“8 percentage points) starts saving you money almost immediately.

Property as collateral (LAP) is the opposite case. Valuation fees, legal verification, and mortgage registration or stamp duty typically add up to somewhere between โ‚น15,000 and โ‚น30,000, depending on the state and lender โ€” and that’s before you factor in the two-to-three-week processing time. On a small loan, that fixed cost can wipe out most or all of the interest savings. LAP generally only starts making financial sense somewhere in the โ‚น5โ€“8 lakh range, and it becomes clearly worthwhile above โ‚น10 lakh, where the fixed costs shrink to a rounding error against the total interest saved.

Vehicle or equipment-backed business loans sit in between โ€” moderate valuation costs, faster processing than property, and a breakeven point that usually lands somewhere in the โ‚น2โ€“4 lakh range.

A Quick Numbers Comparison 

Here’s a simplified comparison over a 3-year tenure, using a representative unsecured rate of 15โ€“16% against a representative secured rate of 10% (gold loan) or 10% (LAP), before fixed costs:

Loan AmountInterest Paid Unsecured (~16%)Interest Paid Secured (~10%)Raw Interest SavedTypical LAP Fixed CostsNet Saving After Fixed Costs
โ‚น1,00,000~โ‚น25,000~โ‚น16,000~โ‚น9,000N/A (use gold loan, not LAP)Gold loan: still net positive
โ‚น2,00,000~โ‚น53,000~โ‚น32,000~โ‚น21,000~โ‚น20,000Roughly breakeven
โ‚น5,00,000~โ‚น1,33,000~โ‚น81,000~โ‚น52,000~โ‚น20,000~โ‚น32,000 saved
โ‚น15,00,000~โ‚น3,98,000~โ‚น2,42,000~โ‚น1,56,000~โ‚น25,000~โ‚น1,31,000 saved

Note: these are illustrative figures based on representative rate bands, reducing-balance EMI math, and typical fee ranges reported by Indian lenders as of August 2026. 

The pattern holds regardless of the exact numbers: 

On a โ‚น1 lakh loan, a gold loan wins easily because there’s almost no fixed cost standing between you and the rate discount. On a โ‚น2 lakh loan taken as a property-backed loan specifically, the fixed costs and the interest savings roughly cancel out โ€” which is exactly why lenders rarely push LAP that small in the first place. By โ‚น5 lakh and above, the fixed cost stops mattering and the rate gap does all the work.

When Collateral Still Doesn’t Make Sense, Even Above the Threshold

Crossing the breakeven number doesn’t automatically make collateral the right call. A few situations flip the decision back toward unsecured, even at a large loan amount and you started searching forย  Collateral vs No Collateral Loan.

  • You need the money in days, not weeks. An unsecured personal loan can disburse within 24โ€“48 hours. A property loan’s valuation and registration process can eat two to three weeks โ€” a real cost if the need is urgent (medical, a time-bound business opportunity, an admission deadline).
  • The asset has a use you’d lose access to. Gold jewelry you might need to sell or gift, or a property you’re planning to sell within the loan tenure, becomes harder to move once it’s pledged. Foreclosure and part-release processes add time and fees of their own.
  • Your income is genuinely unstable. Secured loans still get called in on default โ€” the lender auctions the asset. If repayment is uncertain, adding “losing the collateral” on top of “damaged credit score” is a worse outcome than an unsecured default alone, all else equal.
  • The rate gap has shrunk. RBI rate cuts through 2025 and 2026 have compressed the spread between top-tier unsecured personal loans (some starting near 10%) and secured options in certain cases. Always compare Collateral vs No Collateral Loan live quotes โ€” a hypothetical rate gap on a post isn’t the rate you’ll actually be offered.

Which One Should You Pick Between Collateral vs No Collateral Loan?

Match the collateral type to the loan size, not the other way round:

  • Borrowing under โ‚น2 lakh and you own gold or have a fixed deposit sitting idle? Pledge it โ€” the fixed-cost floor is low enough that it almost always wins over an unsecured loan.
  • Borrowing โ‚น2โ€“5 lakh? Run the actual numbers from at least two lenders before deciding. This is the genuine grey zone where fees can cancel out the rate advantage.
  • Borrowing โ‚น5 lakh or more and you have a property or a high-value asset to pledge? Collateral almost always wins on cost, provided you can tolerate the slower disbursal and the asset being locked up for the tenure.
  • Need the money within a week, regardless of amount? Unsecured is usually the only realistic option, and the speed premium is worth paying for.

The rate on the sanction letter is only half the decision. The other half is whether your loan amount is big enough to make the fixed costs of pledging that asset disappear into the background โ€” and that number changes depending on what you’re pledging, not just how much you’re borrowing.

Read More ๐Ÿ‘‰ Your Credit Score Ignores 90% of Your Financial Life โ€” What Your First Credit Card Changes 

Conclusion

Collateral doesnโ€™t automatically make a loan cheaper if you understand at what point it financially makes sense then you wonโ€™t get confused ever. The loan amount, the asset you pledge, and the rate difference all have to work in your favour. 

Which kind of loan you are seeking is also a matter, Gold or FD-backed loans can make sense even at smaller amounts because their upfront costs are low, while other higher loans such as property-backed loans usually need a much larger ticket before the interest savings outweigh valuation, legal, and registration costs.

Collateral vs No Collateral Loan is not a big confusion, there is no universal โ‚น5 lakh or โ‚น10 lakh cutoff where collateral suddenly becomes worth it. So you must understand where your interest savings finally outweigh the real cost and inconvenience of pledging the asset.ย 

Leave a Comment

Your email address will not be published. Required fields are marked *

Best Noise-Cancelling Headphones for Online Classes and Mock Testsย 

Headphones

You’re 40 minutes into a 3-hour mock test, deep into the reasoning section, and someone two floors down starts drilling a wall. Or it’s your neighbor’s TV bleeding through during a live online class, right when the teacher explains the one concept you actually needed. With best Noise-Cancelling Headphones, it is possible to block the noise out the room, stays comfortable for hours, and doesn’t die halfway through a session. 

As that kind of interruption doesn’t just annoy you โ€” it costs you marks and attention you can’t get back. The right pair of Noise-Cancelling Headphones for online classes and mock tests is meant for this. Not just any Headphones โ€” most people don’t need studio-grade audio for a lecture or a test window. Here are best picks that actually do that, across different budgets.

Why ANC Matters More for Exams Than for Music

Active noise cancellation in short ANC, helps prevent outside noise with an inverse sound wave by using a microphone and it is so effective on low-frequency and steady sound like traffic, fans, washing machine, TV, and construction site but less effective random sharp noises like barking or door slamming.

For a 2-3 hour mock test, that steady cancellation is what keeps your focus from draining. For live classes, you also need a decent mic, since ANC alone won’t help your teacher hear you over a ceiling fan.

Best Noise-Cancelling Headphones for Online Classes and Mock Tests

1. boAt Airdopes 413 ANC โ€” โ‚น1,999

  • 25dB Active Noise Cancellation
  • ENx dual-mic technology for calls
  • ~20 hours total battery (earbuds + case)
  • In-ear TWS design


This is about as cheap as real ANC gets in India, and it holds up for what it is โ€” steady background noise gets noticeably duller, which is the whole point during a test. The case battery isn’t huge, so charge it the night before a long mock test rather than assuming it’ll carry you through a full day.

Best for: the tightest possible budget where any real ANC beats none.

2. Boult Audio Omega โ€” โ‚น2,499

  • Active Noise Cancellation + separate ENC chip for calls
  • 4 mics per stem, touch controls
  • ~32 hours total battery (8hr earbuds + 24hr case)
  • Dedicated Game Mode for low latency

The separate ENC chip is the standout here โ€” it’s built for call clarity, which matters if your online classes involve a lot of back-and-forth with the teacher rather than passive listening. If you are also looking for gaming purposes, not just for mock test sessions then low-latency mode is an additional benefit in Boult Audio Omega.

Best for: students who have live classes and online courses to attend rather than recorded lectures.

3. Noise Buds Solo โ€” โ‚น2,999

  • Active Noise Cancellation with switchable Transparency mode
  • 10mm driver, touch controls for calls/music/voice assistant
  • ~36 hours total battery (7hr earbuds + case)
  • Interchangeable eartips for fit
Noise Buds Solo


The 36-hour total battery is the best in this budget tier, and the switchable Transparency mode is genuinely handy โ€” flip it on for five minutes if someone’s calling you from another room, without pulling an earbud out mid-test. Interchangeable eartips also make a bigger difference than you might realize; a bad seal will ruin passive noise isolation even before ANC activates. 

Best for: the best all-round earbud pick under โ‚น3,000 if battery life is your priority.

Read More๐Ÿ‘‰ Best Laptops for Coding and Programming: Top Picks for Every Budget

4. boAt Rockerz 450 ANC โ€” โ‚น2,499โ€“2,999

  • Hybrid ANC (up to 25dB reduction)
  • 20-hour battery life with ANC on
  • 40mm dynamic drivers, BEAST mode for low-latency audio
  • On-ear, foldable design
boAt Rockerz 450 ANC


This is the one to get if you just need to shut out a noisy house without spending a month’s pocket money. The ANC won’t touch a jackhammer, but it flattens fan noise, traffic hum, and a TV in the next room reasonably well. The ear cushions get a little warm after 2+ hours, and call clarity is average โ€” fine for a mock test, less ideal if you’re live-unmuting often in class.

Best for: students on a tight budget who mainly need ANC for silent, focused test-taking.

5. Soundcore Q20i โ€” โ‚น4,298

  • Hybrid ANC with Indoor/Outdoor/Transport modes
  • 40-hour battery life with ANC on
  • Soft protein-leather earcups
  • Wired mode available (3.5mm) when the battery does die
Soundcore Q20i


The battery life here is the real selling point โ€” 40 hours means you could go through an entire mock-test series for a week without touching the charger. The Indoor mode specifically tunes the ANC for steady household noise rather than street sound, which is exactly the scenario most Indian students are dealing with. The bass is a bit boosted for critical listening, but for lectures and tests that’s irrelevant.

Best for: anyone who forgets to charge things โ€” this Noise-Cancelling Headphones forgives you.

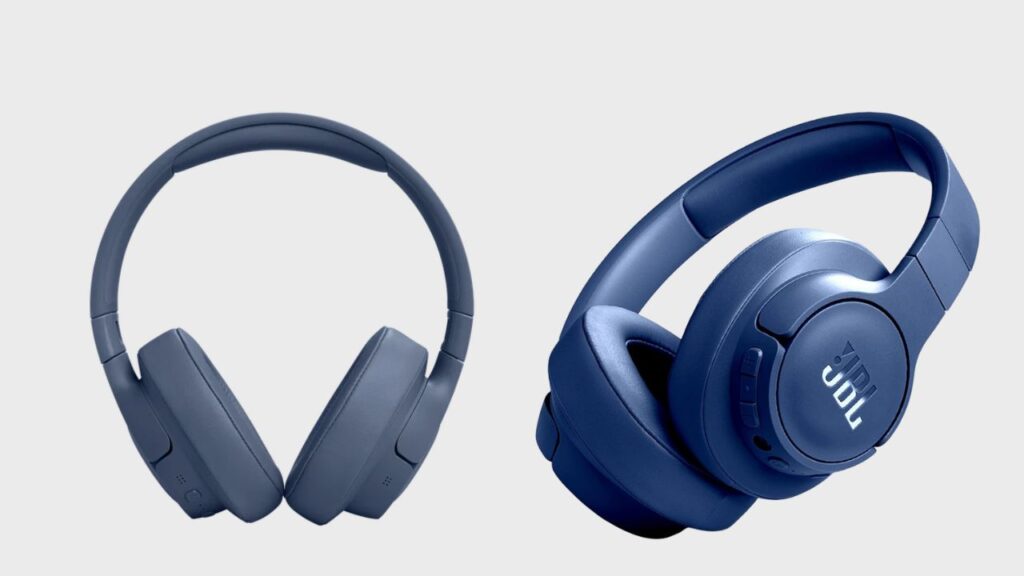
6. JBL Tune 770NC โ€” โ‚น8,999โ€“10,999

  • Adaptive ANC that responds very quickly to the surrounding noise automatically
  • 50-hour battery life (ANC off), around 44 hours with ANC on
  • Multipoint Bluetooth (connect to phone and laptop simultaneously)
  • 40mm drivers with JBL Signature Sound
JBL Tune 770NC

The multipoint pairing is genuinely useful if you attend classes on a laptop but take calls or check notifications on your phone โ€” no fumbling with Bluetooth settings mid-lecture. Adaptive ANC means it automatically dials up cancellation when your maid starts sweeping and dials back down when it’s quiet, instead of a fixed on/off toggle. Bass is JBL’s usual signature โ€” punchy, a little forward โ€” which some people love and others find a bit much for spoken-word content.

Best for: students juggling both a laptop for classes and a phone for everything else.

7. Soundcore Space Q45 โ€” โ‚น9,999 (often available around โ‚น8,500โ€“9,000 on sale)

  • Adaptive ANC rated up to 98% noise reduction
  • 50-hour battery life with ANC on
  • LDAC support for Hi-Res audio over Bluetooth
  • Memory foam earcups, app-based custom EQ

This is the closest thing to flagship-level ANC without paying flagship prices. The 98% noise reduction figure holds up well against consistent background noise โ€” the kind you get from a busy street or a joint family household during the day. Good memory foam cushions really do make a difference during a 3-hour test because your ears are not sore at the end. The app is actually useful, allowing you to choose a โ€œstudyโ€ EQ preset that cuts mid-bass boom, making spoken word clearer while youโ€™re studying or attending lectures.

Best for: the best all-round pick if you want near-premium ANC without the premium price tag.

Read More๐Ÿ‘‰ Best Student Loans for College Students

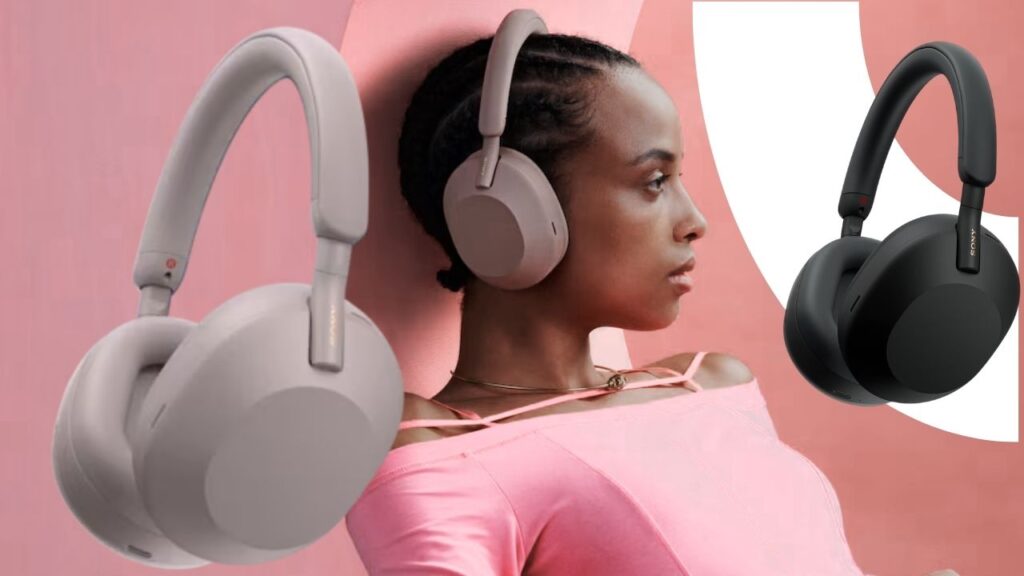
8. Sony WH-1000XM5 โ€” โ‚น29,990

  • Industry-leading ANC with 8-microphone array and dual processors
  • 30-hour battery life with ANC on
  • Speak-to-Chat: automatically pauses audio when you start talking
  • Precise Voice Pickup Technology for clearer calls
Sony WH-1000XM5

If your budget stretches this far, the XM5 is close to overkill for a student use case โ€” but that’s not a bad thing. A duo which makes you feel like you are sitting in an exam hall rather than your house. When youโ€™re nervous your voice gets lower that people sitting behind the system couldnโ€™t understand but Sony WH-1000XM5 gives an automatic Speak-to-Chat feature that pauses automatically if you say something out loud and passes your lower voice very smoothly. But this is too expensive for students but college students who strictly need can buy it on EMI

Best for: students who treat this as a long-term investment across school, coaching, and eventually work-from-home use.

Sony WH-1000XM5 vs Soundcore Space Q45

Sony WH-1000XM5Soundcore Space Q45
Priceโ‚น29,990โ‚น9,999
ANC strengthBest-in-class, handles sudden noise tooExcellent against steady noise, weaker on sudden sharp sounds
Battery (ANC on)30 hours50 hours
Mic quality for classesBest on this listGood, not exceptional
Value for a student budgetLow โ€” premium pricingHigh โ€” near-flagship ANC at a third of the price

If money weren’t a factor, the XM5 wins outright. For a student budget, though, the Space Q45 gets you 80-90% of the noise-cancelling experience for roughly a third of the price, plus a longer battery โ€” which matters more than most people expect once exam season gets long.

Which Noise-Cancelling Headphones Should You Buy?

If you’re prepping for a single exam cycle and want the smallest possible spend, go with the boAt Rockerz 450 ANC or the Soundcore Q20i โ€” either will hold up fine for mock tests where mic quality doesn’t matter. If you’re attending daily online classes on top of tests and need reliable multipoint connectivity, the JBL Tune 770NC earns its price. 

And if youโ€™re looking for one pair that will cover you throughout years of coaching, college, and then working remotely, the Soundcore Space Q45 is the best value for money on this list, with the Sony WH-1000XM5 as the upgrade option if budget genuinely isnโ€™t an issue. 

All of Noise-Cancelling Headphones are available on Amazon.in and Flipkart, boAt and Sony also sell directly from their own India stores if you want manufacturer warranty support without a third party seller in the mix. Prices above reflect typical listings as of August 2026 and do fluctuate with sale events โ€” worth a quick price-check before you check out.

boAt Rockerz 450 ANC vs Noise Buds Solo

boAt Rockerz 450 ANC (Over-ear)Noise Buds Solo (Earbuds)
Priceโ‚น2,499โ€“2,999โ‚น2,999
Noise blockingANC + passive seal from ear cupsANC only, weaker passive isolation
Comfort for 2-3 hr sessionsBetter for most โ€” no in-ear fatigueSome users get ear fatigue past 90 min
Battery20 hours~36 hours total (earbuds + case)
PortabilityFoldable but bulkierFits in a pocket

If you’re choosing between a headphone and earbuds at roughly the same price, format matters more than spec sheets here. Over-ear wins on raw silence for a long test window; earbuds win on battery life and portability if you’re carrying them between home, coaching class, and a library.

Read More ๐Ÿ‘‰ How to Apply for a Student Loan to Get a Higher Education & Make Career

Conclusion

Best Noise-Cancelling Headphones for online class and mock tests are not always the expensive ones. For most students, the Soundcore Space Q45 provides the best combination of ANC, comfort, battery life, and price, while the boAt Rockerz 450 ANC and Soundcore Q20i are better choices for those on a tighter budget. 

If money is not an issue, the Sony WH-1000XM5 offers the best overall experience. In the end, decide based on the length of your studies, the noise level of your environment and whether you need better microphones or portability in addition to noise cancellation. 

Leave a Comment

Your email address will not be published. Required fields are marked *

Your Credit Score Ignores 90% of Your Financial Life โ€” What Your First Credit Card Changesย 

Credit Score

Once your first credit card is approved, you probably think that you are eligible for loan or finance. But youโ€™re wrong because your credit score matters and it is built from repayment history not from your financial status or expenses. There are four active bureaus (CIBIL, Experian, Equifax, CRIF High Mark) in India and they all sit between 300 and 900 score. 

And it doesn’t know your salary, your savings account, your mutual fund SIPs, or the fact that you’ve never once missed a rent payment. It tracks exactly one thing closely: how you’ve handled borrowed money. 

That gap between what the score sees and what your financial life actually looks like is where most first-time cardholders get caught off guard.

What Your Credit Score Measures in Your Financials

A score is built almost entirely from repayment behavior. FICO, the US model most bureaus borrow their logic from, publishes its weighting: payment history (about 35%), credit utilization (about 30%), length of credit history (about 15%), credit mix (about 10%), and new credit inquiries (about 10%). 

It breaks it down, the ingredients look roughly like this:

  • Payment history โ€” whether you’ve paid EMIs and card bills on time. This carries the heaviest weight, often estimated at around 30-35%.
  • Credit utilization โ€” how much of your available credit limit you’re actually using. Maxing out a card, even if you pay it off in full, can quietly hurt you. 
  • Length of credit history โ€” how long your oldest active account has been open. This is exactly why closing your first credit card years later can lower your score instead of helping it. 
  • Credit mix โ€” a blend of secured loans (car, home) and unsecured ones (credit cards, personal loans) reads better than having only one type. 
  • New credit inquiries โ€” every time you apply for a loan or card, a “hard inquiry” gets logged, and too many in a short window signals risk to lenders. 

CIBIL doesn’t publish its exact formula, but the underlying behavior it rewards and punishes is the same. None of this touches your bank balance. It only starts once you’ve borrowed something โ€” a loan, an EMI, a credit card and shows how consistently you paid it back.

Read More ๐Ÿ‘‰ Best App To Get Instant Loan Without Salary Slip

The 90% of Credit Score Never Sees Your Financial Life

Your salary doesn’t appear on your first credit card report. Neither does your savings balance, your fixed deposits, your stock or mutual fund portfolio, property you own, freelance or side income, or rent you’ve paid on time for years (unless you’ve specifically enrolled in one of the newer rent-reporting services, which are still rare in India). Utility bills and UPI spending don’t count either, since none of that is borrowed money. 

This cuts both ways. Someone with a strong income and zero loans can be “credit invisible” โ€” no score at all, simply because they’ve never borrowed. Someone drowning in personal debt but paying the minimum on time every month can carry a technically decent score while their actual finances are falling apart. The number reflects repayment discipline, not net worth.

Why This Number Still Runs Your Financial Life

Even though it’s a narrow measurement, it’s the one lenders trust most. A home loan applicant with a score above 750 might get an interest rate a full percentage point lower than someone below 650 โ€” on a 20-year loan, that gap alone can add up to lakhs of rupees in extra interest. 

Your score also decides which credit cards you qualify for and what limit you’re offered, and in some sectors โ€” finance, banking, occasionally government roles โ€” employers run a credit check as part of background verification. 

Landlords in a few metro markets have started asking for credit reports too. None of that is about how much you earn. It’s entirely about whether you’ve paid back what you owed, on time, before.

The Mistakes That Wreck a First-Time Cardholder’s Score

Paying Only the Minimum Due

The minimum due usually around 5% of the outstanding bill โ€” keeps your account technically current, but the remaining balance starts accruing interest immediately, typically in the range of 3 โ€“ 3.5% a month, which works out to somewhere near 36โ€“42% annualized. It’s one of the most expensive ways to borrow money that exists, and the balance compounds faster than most first-time users expect.

Maxing Out the Limit

Spending close to your full limit every month signals risk to lenders, even if you clear the bill in full. Keeping usage under roughly 30% of your available limit protects the score far more than people assume โ€” this is often a bigger factor than the actual bill amount.

Applying for Multiple Cards in the First Year

Every new application triggers a hard inquiry, and each one dents the score slightly while sitting on your report for a couple of years. Several applications close together read to lenders as credit hunger, not creditworthiness.

Missing the Due Date, Even Once

A single day late usually just costs a late fee. But once a payment crosses roughly 30 days overdue, it typically gets reported to the bureau and that single entry can move the score sharply and stay visible for years.

Closing the Card Too Early

Shutting down  your first credit card within the first year shortens your average credit age, which is one of the more underrated factors in the score. A longer, active history โ€” even on a card you barely use โ€” tends to help more than starting fresh with a new one.

Read More ๐Ÿ‘‰ How to Apply for an Education Loan Online

The Right Way to Spend From Your First Card

Treat it like a debit card with a receipt trail, not free money. Pick one or two recurring expenses โ€” a mobile recharge, one subscription, fuel and route them through the card on autopay. This builds a steady, low-risk repayment pattern without tempting you into overspending. 

Pay the full statement balance every cycle, not the minimum. Check your statement monthly for errors or unfamiliar charges. Avoid withdrawing cash on the card entirely โ€” interest usually starts from the day of withdrawal with no grace period, on top of a flat fee near 2.5โ€“3%. 

And think twice before converting purchases to EMI, even “no-cost” ones; the discount you’d have gotten on the outright price is often quietly folded back into the total.

How Fast Can a Credit Score Really Move?

Scores don’t jump in percentages โ€” there’s no such thing as a score rising “by 90%.” They move in points, and how fast depends on which factor you’re fixing. 

Utilization moves quickest: pay down a high balance before your statement date, and the next reporting cycle, usually 30 to 45 days later, can reflect a meaningful jump, sometimes 50 or more points on the 900-point scale, because utilization updates almost as fast as your balance does. 

Payment history moves slower and compounds instead: one on-time payment barely registers, but six to twelve months of consistent on-time payments builds a track record lenders actually trust. Bureau errors โ€” a closed loan still showing as open, a paid card marked as defaulted, can also produce a fast correction once flagged, sometimes within a single reporting cycle. 

For someone starting with a thin or nonexistent credit file, a workable, lender-friendly score in six to twelve months of disciplined use is a realistic target. Overnight is not.

Before Cardholder Swipe That First Time

Pull your free annual report from the bureau and note your starting number before you spend a single rupee. Set autopay for the full statement amount, not the minimum, and add a separate calendar reminder a few days before the due date as backup. 

Pick one recurring bill to run through  your first credit card and leave the rest alone for now. Then check the number again in three months, not three weeks โ€” that’s roughly how long it takes the system to actually reflect what you did.

Read More ๐Ÿ‘‰ Business Ideas for Students With Zero Investment โ€” Easy Startup Guide

Conclusion

Your financial health doesnโ€™t increase your Credit Score and it is important to maintain that score. It’s a way for lenders to understand how responsibly you’ve handled borrowed money, not how much you earn, save, invest, or own.ย 

For a first-time cardholder, utilization should be lower, pay the statement balance on time, do not fill unnecessary applications, be patient and give time for your credit history to grow. Treat your first credit card as a tool for building trust with lenders, so when you actually need a bigger loan or good credit, you can get it easily. 

Leave a Comment

Your email address will not be published. Required fields are marked *

Best Student Loans for College Students

Student Loans

Your admission letter came through and you are stressed about its fees? Thatโ€™s the moment youโ€™ll start looking for the best student loans for college students. Between tuition, hostel, a laptop, and living costs, a B.Tech at a decent private college or a master’s abroad can run anywhere from โ‚น8 lakh to over โ‚น1 crore, and very few Indian families are sitting on that kind of cash without dipping into a fixed deposit meant for something else. 

This is exactly where the best Student Loans in the market โ€” from SBI’s Scholar Loan to NBFCs like HDFC Credila and Avanse, start doing real work, provided it actually fits your situation instead of just going with whichever bank branch is nearest to your house.

This blog walks through the loan for education options Indian students actually use in 2026 โ€” public banks, private banks, NBFCs, and the government’s PM Vidyalaxmi scheme with real numbers, what each one is genuinely good at, and where it falls short.

Who Can Get These Loans for Education

If you’re an Indian student (or a parent reading this on their behalf) heading into an undergraduate program, a postgraduate course, or a study-abroad admission, and you need a study loan rather than paying out of pocket, this comparison is built for you. It splits lenders into three buckets โ€” public sector banks, private banks, and specialised NBFCs because each serves a different kind of borrower, and picking the wrong bucket is the single most common reason students overpay by lakhs over a 15-year tenure.

Interest rates on education loans are floating and revised frequently by each lender’s internal benchmark. The figures below reflect indicative ranges reported by lenders and comparison platforms as of mid-2026. Treat every rate here as a starting reference, not a quote so confirm the live number on the lender’s own site before you apply.

Best Student Loans For College Students in India

1. SBI Scholar Loan / Global Ed-Vantage โ€” Best for Domestic Students and Government-Bank Trust

  • Rate: roughly 8.15%โ€“10.75%, MCLR-linked (floating)
  • Loan amount: up to โ‚น7.5 lakh without collateral for listed premier institutes; higher amounts with collateral, up to โ‚น1.5 crore under Global Ed-Vantage for study abroad
  • Processing fee: flat โ‚น10,000 โ€” no percentage-based fee
  • Tenure: up to 15 years

SBI remains the default first stop for most Indian students, and there’s a simple reason: as the largest public bank, it consistently prices education loans lower than private banks and NBFCs, and its flat processing fee actually saves real money on larger loans compared to a percentage-based charge. 

The trade-off is speed โ€” SBI’s sanction process for study-abroad loans can take four to eight weeks, and IBA guidelines require 15% margin money on foreign education loans above โ‚น4 lakh, meaning you’ll need to arrange that slice yourself. 

Best for: students with time before their visa deadline who want the lowest lifetime interest cost.

2. HDFC Credila โ€” Best for Speed and High-Value Unsecured Loans

  • Rate: roughly 9.5%โ€“13%, secured loans starting near 9.95%, unsecured (no collateral) starting near 11.25%
  • Loan amount: up to โ‚น50โ€“60 lakh for premier institutes, sometimes higher
  • Processing fee: 1%โ€“1.5% plus GST
  • Tenure: up to 15 years

Credila built its business on what it calls a “future employability” assessment rather than collateral value, which is why students without property to pledge still get approved here. Sanctions typically land in 7โ€“14 days, which matters enormously when a visa interview is on the calendar and SBI’s timeline doesn’t fit. 

The catch is that unsecured Credila loans run meaningfully higher than SBI’s rate, and the processing fee, a percentage plus GST are added up fast on a โ‚น50 lakh loan. 

Best for: students on a tight admission or visa timeline who need fast, collateral-free approval and can absorb a higher rate.

3. Bank of Baroda โ€” Best for Large Loans to Global Universities

  • Rate: competitive with SBI, generally in the 8.5%โ€“11% band depending on the institute tier
  • Loan amount: up to โ‚น1.5 crore for premium global universities
  • Processing fee: typically lower than private banks; concessions available for girl students
  • Tenure: up to 15 years

BoB doesn’t get the same attention as SBI or the big NBFCs, but for students heading to genuinely expensive programs like top-50 global MBAs or engineering master’s โ€” its higher loan ceiling and public-bank pricing make it worth a direct comparison. 

Best for: high-ticket study-abroad admissions where you need both a large sanction and a public-bank rate.

4. Avanse Financial Services โ€” Best for Broad Course Coverage

  • Rate: roughly 11%โ€“14.5%
  • Loan amount: up to โ‚น50โ€“75 lakh
  • Processing fee: 1.25%โ€“1.75% plus GST
  • Tenure: up to 15 years

Avanse is one of the few lenders that regularly finances courses public banks are cautious about โ€” niche postgraduate programs, some online degrees, and vocational tracks. It’s genuinely useful when your course doesn’t fit a PSU bank’s approved list. The limitation is its rates sit at the higher end of the NBFC range, so it’s rarely the cheapest option on the table. 

Best for Student Loans for college students whose course or university isn’t covered by public-bank lending lists.

Read More๐Ÿ‘‰ RRB JE Notification OUT With RRB JE Vacancy Of 3,993 Posts 

5. Axis Bank / ICICI Bank Education Loan โ€” Best for Existing Bank Customers Wanting Fast Digital Processing

  • Rate: roughly 9.5%โ€“13.5%
  • Loan amount: up to โ‚น40 lakh
  • Processing fee: moderate, varies by profile
  • Tenure: typically 10โ€“15 years

If you or your parents already bank with Axis or ICICI, pre-approved education loans can be sanctioned in as little as 72 hours for existing customers, bundled with a forex card and a student account for study abroad. The point here is convenience, not price โ€” you’re paying slightly more for an integrated, faster experience with a bank you already have a relationship with. 

Best for: existing customers who value speed and a bundled international banking package over shaving off the last percentage point of interest.

SBI vs HDFC Credila: The Two-Lender Face-Off

These two get compared constantly because they represent opposite philosophies โ€” lowest cost versus fastest approval.

SBI Global Ed-VantageHDFC Credila
Starting rate~8.15%โ€“9.65%~9.5%โ€“11.25% (unsecured)
Processing feeFlat โ‚น10,0001%โ€“1.5% + GST
Sanction time4โ€“8 weeks7โ€“14 days
CollateralRequired above โ‚น7.5 lakhOptional, employability-based
Best forLowest total interest costTight visa or admission deadlines

On a โ‚น50 lakh, 15-year loan, roughly every 100 basis points of extra interest costs about โ‚น7.5 lakh over the loan’s life, so the gap between these two isn’t cosmetic. Take Credila or Avanse first to secure fast disbursal for the visa file, then refinance into SBI once the loan is live and the pressure is off.


This works better than it used to, because the RBI’s Prepayment Charges Directions, effective January 1, 2026, banned foreclosure and prepayment charges on floating-rate loans to individual borrowers โ€” a rule that covers nearly every education loan in this list. Before this, NBFCs could charge 2%โ€“5% of the outstanding principal to close a loan early; that lock-in is now gone.

Don’t Skip the Government Route: PM Vidyalaxmi Scheme

Before comparing private lenders at all, check whether you qualify for PM Vidyalaxmi, the Centre’s collateral-free education loan scheme launched in November 2024. It isn’t a separate lender โ€” it works through participating banks but it changes the math significantly for eligible students:

  • Collateral-free, guarantor-free loans up to โ‚น7.5 lakh, backed by a 75% government credit guarantee
  • Covers students admitted purely on merit (not management or NRI quota) to around 1,425 listed Quality Higher Education Institutions
  • A 3% interest subvention during the moratorium period for families with annual income up to โ‚น8 lakh, on loans up to โ‚น10 lakh
  • Rates capped at the bank’s benchmark lending rate plus 0.5%, with banks free to offer an extra 1% concession if you service interest during your study period
  • Subsidy is disbursed directly through the PM Vidyalaxmi Digital Rupee (CBDC) app

More than 1.12 lakh loans had been sanctioned under the scheme as of July 2026, so it’s no longer a pilot โ€” it’s a live, functioning route worth checking on the PM Vidyalaxmi portal before you approach a bank directly.

Read More ๐Ÿ‘‰ Best Student Laptops for School and University in 2026 

Two Rules That Apply Regardless of Which Lender You Choose

Section 80E tax benefit: the entire interest you pay on student loans for college students โ€” not principal, and with no upper cap is deductible from your taxable income for up to 8 years from the year you start repaying. This applies to loans from any bank or approved NBFC and is one of the few genuinely uncapped deductions left in Indian tax law.

The girl-student concession: most public banks, including SBI and PNB, shave 0.5% off the standard rate for female applicants. It’s easy to miss because it’s rarely advertised loudly โ€” ask for it explicitly when you apply for any of these student loans for college students.

Conclusion

If your priority is the lowest total interest over 15 years and you have a few weeks before your deadline, start with SBI โ€” check PM Vidyalaxmi eligibility first if your loan need is under โ‚น7.5 lakh. 

If your visa interview or admission deposit deadline is within two weeks and you need money to move fast, HDFC Credila or Avanse will get you there, with the option to refinance into a cheaper public-bank loan later at no penalty under the new RBI rule. And if your course or university sits outside what PSU banks typically approve, Avanse’s broader course coverage is worth a direct call before you assume you’re out of options. 

Whichever lender you pick, don’t sign with the first offer you get on Student Loans for college students โ€” pull two or three live quotes through the Vidya Lakshmi portal, apply the 80E deduction into your repayment planning from day one, and claim every concession you’re eligible for.

Note: Interest rates, fees, and scheme terms mentioned above are indicative and change frequently. Verify current figures directly with the lender or on official government portals before applying. 

Leave a Comment

Your email address will not be published. Required fields are marked *

Scroll to Top