Switching Jobs? Don’t Ignore Your EPF, NPS, and Mutual Fund Investments 

Jobs

Your resignation letter is signed, the new offer is accepted, and you’re ready for switching Jobs but what happens to the EPF account and should the new company’s NPS enrollment change anything about how you’re already investing through mutual funds? Don’t Ignore your EPF, NPS and Mutual Fund which most people already are doing.

The EPF vs NPS vs mutual funds decision isn’t really one choice — it’s three separate accounts with three different rules, and a job switch is exactly the moment most people either transfer things correctly or lose track of money they’ve already earned.

What Is EPF, NPS, and Mutual Funds

EPF — 8.25% for FY 2025-26, third year running at that rate, govt-backed, EEE (contribution, interest, withdrawal all tax-free if you cross 5 years’ continuous service). Mandatory for salaried staff at covered establishments; you don’t really “choose” this one, you’re already in it.

NPS — Market-linked, mix of equity/debt/govt bonds you can allocate; extra ₹50,000 deduction under 80CCD(1B) on top of the 80C limit. At exit, minimum 40% of the corpus must go into an annuity — you don’t get the whole pot in cash, and annuity payout rates in India have historically been mediocre (5–6% range).

Mutual funds — No lock-in except ELSS (3 years); LTCG/STCG taxed, no EEE treatment. Best long-run equity return potential of the three, but zero forced discipline — nothing stops you from redeeming during a panic.

Don’t Ignore Your EPF, NPS, and Mutual Funds After Switching Job

Your EPF doesn’t “carry over” automatically. A lot of people assume EPF just follows them to the new job. It doesn’t — not unless you actually transfer it.

When you leave a company, your EPF account under that employer becomes inactive. Your new employer opens a fresh account. If you don’t link the two using your UAN (Universal Account Number), you end up with multiple EPF accounts scattered across your career. Each one earns interest for a while, but an account that stays inactive for 36 months stops earning interest altogether.

How To Set Up Your EPF Account After Job Switch

  • Use the “One Employee One EPF Account” (OEEOA) transfer request on the EPFO portal, or let your new employer initiate it.
  • Don’t withdraw your EPF just because it feels like “extra cash” during the job switch. Withdrawing before 5 years of continuous service makes it taxable, and you lose out on decades of compounding.
  • Check your UAN is correctly linked to Aadhaar and your new employer’s establishment ID — half of all transfer delays come from mismatched KYC details.

The instinct to cash out is understandable when you’re between Jobs and expenses are piling up. But EPF is one of the few instruments giving you a stable, tax-free return over the long run. Treat withdrawal as a last resort, not a bonus.

Read More 👉 Your Credit Score Ignores 90% of Your Financial Life — What Your First Credit Card Changes 

Check Your NPS Before Leaving the Company

Your NPS account isn’t tied to your employer at all. It’s tied to you, through your PRAN (Permanent Retirement Account Number). So technically, nothing needs to be “transferred.”

But there’s a catch. If your NPS contribution was happening through your employer under the corporate NPS model, that contribution stops the day you resign. Your new employer may or may not offer an NPS benefit. If they don’t, your account doesn’t close but it goes silent unless you start contributing on your own through the eNPS platform or a POP (Point of Presence).

What to check:

  • Confirm your new employer’s NPS deduction is active and linked to your existing PRAN — don’t let them create a second one by mistake.
  • If your new company doesn’t offer NPS, decide if you want to keep contributing voluntarily. Many people simply let it sit, which defeats the purpose of consistent, long-term retirement investing.
  • Update your bank and nominee details after the switch — this is the most commonly skipped step.

NPS rewards discipline more than any other retirement product because of how compounding and low fund management costs stack up over 20-30 years. A gap of even a couple of years in contributions has a real, measurable impact on your final corpus.

Mutual funds: the SIPs nobody remembers to check

Job switches usually come with a change in salary account, and that’s where mutual fund SIPs quietly break. If your SIP auto-debit was linked to your old salary account and you close that account (or stop maintaining the minimum balance), your SIP simply fails. Most people don’t notice for months — until they check their portfolio and realize three or four SIP cycles never went through.

What to do immediately after switching:

Re-link your SIP mandates to your new primary bank account, or keep enough balance in the old one until the transition is smooth.

Review your asset allocation. A new job often means a new salary, new expenses, maybe new financial goals (relocation, higher rent, a shorter or longer commute cost). Your SIP amounts should reflect your current life, not your old one.

If you got a signing bonus or relocation allowance, resist the urge to let it sit in a savings account. Even a lump sum top-up into an existing fund puts that money to work instead of losing value to inflation.

What Happens If You Neglect These Procedures

None of this is complicated. It’s just easy to postpone because nothing about it feels urgent in the middle of a job change. But delayed EPF transfers lose interest. Paused NPS contributions lose compounding years you can’t get back. Broken SIPs mean missed market cycles.

A Jobs switch is one of the few moments where you’re forced to look at your entire financial setup at once — new salary, new perks, new expenses. Use that moment. Spend one weekend afternoon logging into EPFO, checking your PRAN, and confirming your SIPs are active. It’s boring, unglamorous work. It’s also the difference between a retirement corpus that actually reflects your career and one that has quiet, unexplained gaps in it.

Your new job deserves your excitement. Your old investments deserve five minutes of your attention before you move on.

Read More 👉 Collateral vs No Collateral Loan Amount Where Collateral Starts Making Financial Sense

Conclusion

Switching Jobs is exciting but don’t ignore your EPF, NPS, and mutual funds investment as it is a chance to reset your financial checklist. Your EPF needs to be transferred, your NPS needs to stay linked to your PRAN, and your mutual fund SIPs need to keep running without interruption.

You don’t have to choose between EPF vs NPS vs mutual funds, understanding the role each plays in your long-term financial plan is important. EPF provides retirement stability, NPS adds a dedicated retirement investment option, while mutual funds offer greater flexibility and growth potential.
Leave a Comment

Your email address will not be published. Required fields are marked *

UP SuperTET Vacancy Notification 2026: Check Out Details, Dates, & Eligibility

SuperTET

If you’ve been searching continuously on Google for “UP SuperTET 2026 Notification Out, you are not alone because many future teachers are googling it but don’t panic. You are not late, because the official notification has not been released yet. The vacancy numbers are a guess if you see anywhere.  

When Will The UP SuperTET Notification Get Released?

UPBEB is going to publish the SuperTET 2026 notification soon and it carries the exam date, required documents, eligibility, and exam pattern information for the candidates. The best way of starting the process is to read that notification carefully once it is released before going to fill the form for UP SuperTET 2026. 

It’ll land after the UPTET result is out, so most of the candidates get eligible for the SuperTET so there should be a larger number of vacancies. But that’s an educated guess about timing, not a commitment from the The Uttar Pradesh Basic Education Board. 

Where You Can Find The SuperTET Updates? 

Skip the YouTube shorts and forward-heavy WhatsApp groups. The two sources worth bookmarking are:

Vacancy For UP SuperTET Exam 2026

From the past cycle and current teacher-shortage data, it is precisely reasonable that UP SuperTET 2026 Vacancy lies around 69,000, 85,000. But these numbers aren’t shared by the officials so treat them as a closer guess. 

The 2019 SuperTET drive filled around 69,000 posts so it became the usual provisional around number. Until UPBEB publishes district-wise and category-wise vacancy breakdowns in the actual notification.

SuperTET Salary and Eligibility 

Vacancy and dates can change year by year but 80% of the stuff is the same each year. SuperTET eligibility, salary, exam pattern are not going to change, even if it does, only slight change can happen. 

ParameterDetails
PostAssistant Teacher – Primary (Classes 1–5) and Upper Primary (Classes 6–8)
Pay Scale₹35,400 – ₹1,12,400 (Level 6, 7th Pay Commission)
EligibilityValid CTET or UPTET:- Paper I for Primary (Classes 1–5)- Paper II for Upper Primary (Classes 6–8)Plus relevant qualifying degree and/or B.Ed as per recruitment rules
Exam PatternObjective-type test, 150 marks, covering:- Language proficiency- Pedagogy (teaching methodology)- General Knowledge- Subject-specific content knowledge

Qualifying Numbers are easily let you pass by acquiring 40% (60/150) if you are General category candidate and 33% (49.5/150) for the candidates who belong to SC/ST/OBC-NCL/PwD but they are not a scoring score to win this battle among thousands candidates. 

Actual merit cutoff: if you actually want to get selected then score from 90 to 130+ out of 150 to hold out your position. These are the actual merit numbers, it also depends up on your category and how many seats are open. 

That gap between “qualifying score” and “actual selection score” trips people up every cycle. SuperTET isn’t a pass/fail eligibility test — it’s a straight competitive recruitment exam. Scoring the minimum gets you nowhere near a job.

UPSSSC PET Exam Date 2026 Out

How To Prepare Yourself For The Exam

  1. Don’t wait to start preparing. The syllabus and pattern are already finalized by UP authorities, which is usually a sign the recruitment machinery is moving even if the notification isn’t out yet.
  2. Keep your CTET/UPTET certificate and documents ready. Once the form opens, the window is typically short — 20 to 30 days and document scrambling under deadline pressure is a self-inflicted wound.
  3. Ignore vacancy-number debates on social media. They change nothing about your prep and mostly exist to farm engagement.
  4. Set a check-in habit, not a refresh habit. Checking the official website once a day is enough. Constant refreshing just adds stress without adding information.

Conclusion 

Start focusing on the syllabus, pattern, expected post structure before UP SuperTET 2026 Notification Out because it’s released, you won’t get enough time to prepare after that. There’s no confirmed vacancy count but there’s a guessing number, the competition will be higher. 

Prepare like the exam is close, because structurally it looks like it is, but don’t let unverified numbers shape your expectations or your plans.

Always cross-check every information on the official website of UP Super TET 2026 Notification Out before acting on any detail published by educational sites.

Leave a Comment

Your email address will not be published. Required fields are marked *

How to Apply for a Student Loan to Get a Higher Education & Make Career

Student Loan

How to apply for a Student Loan doesn’t come randomly in anyone’s mind. Getting into a good college is only half the battle. The other half starts the moment you realize a B.Tech at a decent private university now costs ₹8–15 lakh, an MBA at a tier-2 B-school can run past ₹12 lakh, and a master’s abroad easily crosses ₹40 lakh once you add living costs. 

If you don’t have that sort of money lying around, a Student Loan is the only realistic option — and how to get one usually determines how much of that money actually gets deposited into your account, and how much you end up overpaying in interest over the next 10 years. 

This guide walks through the process as it actually works in India in 2026, not the version that shows up in a bank’s marketing brochure.

How to Apply for a Student Loan Through the Vidya Lakshmi Portal

Almost every organized education loan in India now runs through the Vidya Lakshmi portal, a government-backed single window that connects more than three dozen banks and well over 100 loan schemes to one common form. Instead of visiting five bank branches and filling five different applications, you fill one — the Common Education Loan Application Form (CELAF), prescribed by the Indian Banks’ Association and accepted by every participating lender.

The process, in order:

  • Register on the portal with your email ID and a mobile number, ideally the one linked to your Aadhaar, since OTP verification runs through it.
  • Fill the CELAF in sections — personal details, course and institution details, cost breakdown, and your co-applicant’s financial information.
  • Upload KYC documents, academic transcripts, and your admission letter in the required digital format.
  • Use the “Search and Apply” tab to filter loan schemes by amount, interest rate, and whether you’re studying in India or abroad.
  • Shortlist and apply to a maximum of three banks in one go — a sensible mix is usually one public-sector bank (lower rate, slower processing) and one private bank or NBFC (faster, more flexible).
  • Track status from your dashboard. If a bank marks your application “on hold,” it means they want more documents — check the remarks column rather than waiting for an email.

The portal is also linked to the National Scholarship Portal, so if you qualify for a central or state scholarship, you can apply for it in the same sitting.

Where the PM Vidyalaxmi Scheme Fits In

Layered on top of Vidya Lakshmi since 2024–25 is the PM Vidyalaxmi Scheme, a Central Sector Scheme aimed specifically at students who’ve secured admission — through merit-based or open competitive selection — into a Quality Higher Education Institution (QHEI). The official list currently runs past 800 institutions and keeps expanding as new NIRF-ranked colleges get added, so don’t assume your college qualifies; check the current QHEI list on the portal before you plan around this scheme.

What it actually gets you:

  • No collateral, no guarantor for eligible loans. Some official sources describe this as applying to the entire loan regardless of amount; others cap the collateral-free portion at ₹7.5 lakh, after which the bank may ask for security on the balance. This detail genuinely varies by bank in practice — confirm it directly with your chosen lender before you apply, don’t assume either version.
  • A 75% government credit guarantee on loans up to ₹7.5 lakh, which is what makes banks comfortable lending without collateral in the first place.
  • Interest subvention during the moratorium period (course duration plus one year) — full interest subsidy if annual family income is up to ₹4.5 lakh, and a 3% subsidy if family income falls between ₹4.5 lakh and ₹8 lakh, both capped at loans up to ₹10 lakh.
  • Above ₹8 lakh family income, you still get the collateral-free structure and credit guarantee — you just pay the bank’s normal interest rate with no subsidy.

To claim the subvention, you submit an “intent” declaration on the portal along with income proof from an authorized state government authority — it isn’t automatic just because you’re eligible.

Eligibility Criteria You Need to Meet For Student Loan Across Indian Banks

Setting PM Vidyalaxmi aside, general education loan eligibility across Indian banks looks fairly consistent:

  • You need to be an Indian national with confirmed admission to a recognized, full-time regular course — part-time and distance programs are excluded by most lenders, though a few NBFCs make exceptions.
  • A co-applicant, almost always a parent or guardian, is required by nearly every bank once the loan crosses a modest threshold (often ₹4 lakh), and their income and credit history factor directly into how much you’re sanctioned.
  • For merit-based schemes like SBI’s Scholar Loan or PM Vidyalaxmi’s QHEI route, your entrance exam rank or admission channel matters as much as your family’s finances — these schemes exist precisely to reward the admission, not the collateral.
  • There’s no universal age cap, but banks do informally weigh whether you’re likely to complete the course and start repaying within a reasonable working-age window.

Documents to Keep Ready Before You Apply

Missing paperwork is the single most common reason applications sit in limbo for weeks. Have these ready before you start the CELAF, not after:

  • Admission letter and the institution’s official fee/cost structure
  • Mark sheets for 10th, 12th, and any prior degree
  • Identity proof — Aadhaar and PAN at minimum
  • Co-applicant’s income proof: recent salary slips or ITR, and the last six months of bank statements
  • Collateral documents, if your loan amount or scheme requires security
  • Passport and visa copy, if you’re studying abroad

Keep names spelled identically across every document — a mismatch between your Aadhaar and your admission letter is a small thing that causes real delays.

How Much Will It Cost You Across Every Sector Banks

Interest rates on Indian education loans in 2026 span a wide range depending on lender type:

  • Public-sector banks (SBI, PNB, Bank of Baroda, Union Bank, Canara Bank) generally price standard education loans between roughly 8% and 10.75% p.a., floating, tied to each bank’s repo-linked or external benchmark rate. As of mid-2026, the RBI repo rate itself sits around 6.25% — the actual benchmark moves at each monetary policy review, so treat any quoted rate as a starting point to verify, not a fixed number.
  • SBI’s Scholar Loan, reserved for students admitted to premier institutes like IITs, IIMs, and NITs, runs noticeably lower — roughly 6.9% to 7.65% p.a. — compared to its regular Student Loan Scheme at around 9.4% to 9.9%.
  • Private banks and NBFCs (HDFC Credila, Avanse, and similar) typically charge 9.5% to 16% p.a. Rates are higher, but sanction and disbursal are usually faster, and many offer larger unsecured amounts.
  • Most public banks give a 0.5% interest concession to girl students — worth asking about explicitly, since it isn’t always advertised upfront.
  • Several lenders, including SBI and PNB, offer a 0.5–1% rate discount if you pay simple interest during the moratorium period instead of letting it accumulate. Skipping this is the single most expensive mistake students make: unpaid interest during your study years gets added to the principal, so your EMI ends up calculated on a bigger loan than you actually borrowed.

Claiming the Section 80E Tax Benefit Once You Start Repaying

Once repayment begins, Section 80E of the Income Tax Act lets you deduct the entire interest component of your EMI from taxable income — not the principal, just the interest, but with no upper cap, which is unusual among Indian tax deductions.

A few conditions determine whether you actually qualify:

  • The deduction is available for a maximum of eight consecutive years, starting from the year you begin paying interest, or until the interest is fully repaid, whichever comes first.
  • It only applies if you’ve opted for the old tax regime — under the new regime, this deduction isn’t available at all, so run the comparison before you file.
  • The loan must come from a recognized bank, financial institution, or an approved charitable institution. A loan from an employer, a relative, or an informal lender does not qualify, no matter how similar the repayment terms look.
  • You can claim it for a loan taken for yourself, your spouse, your children, or a legal ward — and it applies whether the course was pursued in India or abroad.
  • You’ll need an interest certificate from your lender each financial year, clearly splitting principal from interest, to actually file the claim.

How To Avoid Application Rejection

A few patterns show up again and again in rejected or delayed applications: 

  • Applying to just one bank instead of shortlisting two or three through Vidya Lakshmi and comparing offers side by side
  • Assuming your college is on the PM Vidyalaxmi QHEI list without checking the current portal listing
  • Letting moratorium interest pile up instead of paying it as simple interest each quarter
  • Submitting documents where your name, date of birth, or address doesn’t match exactly across your Aadhaar, admission letter, and bank KYC. 

Each of these is fixable in an afternoon but only if you catch it before submission, not after a bank has already put your file on hold.

Select the Reliable Option for Student Loan

If you’ve been admitted to a QHEI on the current PM Vidyalaxmi list and your family’s annual income is under ₹8 lakh, start there through the Vidya Lakshmi portal — the interest subvention alone can save you lakhs over the loan’s life, and it’s the closest thing to free money in this entire process. 

If your institution isn’t on that list, or your loan requirement crosses ₹10 lakh, shortlist two or three public-sector banks, compare their post-moratorium rates head-to-head, and ask each one directly what your EMI looks like once the subsidy or discount period ends. Not the headline interest rate but that one question is where most students get blindsided.

Conclusion 

The paperwork for Student Loan application is simpler once you have your documents in order, have compared lenders and know the government schemes that apply to you. Vidya Lakshmi portal provides students a one-stop shop to apply for education loans and also compare the loans, while PM Vidyalaxmi can help eligible students by lightening their financial load through interest support and collateral-free loans. 

Before you accept any offer, look beyond the stated interest rate. Check the terms of the moratorium (temporary period in which you don’t have to start paying the regular EMI), your eligibility for subsidy, the amount you need to repay, the amount of collateral required and the total interest you will pay. A bit of comparison before signing can make a big difference to your finances after you graduate.

Leave a Comment

Your email address will not be published. Required fields are marked *

Why ChatGPT Ads Deserve a Place In Your 2027 Media Plan 

ChatGPT Ads

ChatGPT is becoming another advertising platform for brands and businesses. In 2026, OpenAI opened self-serve access to its Ads Manager in India. But ChatGPT Ads doesn’t work like Google Search, PPC managers should understand before shifting a Google Ads/Paid Search budget to ChatGPT Ads. 

Before asking — why ChatGPT Ads deserve a place in your 2027 media plan? Decide whether you want visibility or conversion from the ads. The answer is not that simple because considering the fact that every business has different approaches and methods to connect with their customers.

But advertisers don’t receive a conversation history or chats, ChatGPT only discloses target, context hints, and intent. Context Hints also don’t work like traditional exact-match keywords. So let’s look into how it’s gonna work and why it’s better than Google search in most cases.

The Channel Is No Longer Experimental

OpenAI began testing ads for logged-in adult users on the Free and ChatGPT Go tiers in the US on February 9, 2026. Three months later, on May 5, it opened a self-serve Ads Manager to any US business, with no minimum spend requirement. By July, the platform had added a formal “Advertise in ChatGPT” hub with case studies from Best Buy, Lowe’s, and VistaPrint. 

By August, OpenAI said the ad business had crossed a $1 billion annualized revenue run rate in under 200 days, and international expansion was already underway — the UK, Mexico, Brazil, Japan, and South Korea by mid-August, with India, Europe, and parts of the Middle East and North Africa following in September.

ChatGPT is becoming a channel with a self-serve buying platform, agency integrations from Dentsu, Omnicom, Publicis, and WPP, and ad-tech partners like Adobe, Criteo, Kargo, and StackAdapt already plugged in. 

What ChatGPT Ads Look Like Inside a Conversation

When a user asks a question, and OpenAI’s system judges a sponsored result relevant, a small card appears below the AI’s answer — never inside it. The card carries a business name, a site icon, a headline, a short description, one square image, and a link out. It’s labelled “Sponsored” and visually separated from the response.

OpenAI has been consistent that the ad doesn’t touch what ChatGPT actually tells the user. Responses and ChatGPT ads from two separate systems.


Targeting doesn’t work the way Google Search advertisers are used to. There’s no exact-match keyword bidding. Instead, advertisers submit “context hints” — short descriptions of the topics, situations, or product categories where their ad might be relevant.

Then OpenAI matches those against the general subject of the conversation, not the user’s chat history or personal data. Advertisers never receive individual conversations, memories, or personally identifiable details. 

What they get back is aggregate performance data: impressions, clicks, spend, cost-per-click.

ChatGPT Ads Charges For a Campaign

ChatGPT ads launched in February at a fixed $60 CPM with a $200,000 minimum commitment — enterprise-only pricing designed to test with brands that could absorb the risk. By April, the minimum had dropped to $50,000 and a CPC pilot was alive. By May 5, both the minimum spend and the fixed pricing were gone entirely, replaced by a relevance-weighted, second-price auction with a $25 minimum daily budget.

As of mid-to-late 2026, CPM campaigns (bought under a Reach objective) run roughly $25 to $60, with real clearing prices often landing in the $25–$45 range as inventory has scaled. CPC campaigns (bought under a Clicks objective) start around $3 to $5 for most ecommerce and consumer categories, climbing to $8–$18 for competitive verticals like software and finance. 

For context, that CPC range sits close to Google Search’s reported Q1 2026 average of $2.96 across industries, but ChatGPT’s conversion rates have been reported in a wider and generally lower band — roughly 0.2% to 5.8%, compared to Google’s cross-industry figure near 8.18%. 

This is priced as premium, high-intent inventory, not as a cheap alternative to your existing channels. You’re not buying volume at a discount. You’re buying attention at a moment when someone is actively working through a decision.

Read More 👉 How AI Could Change India’s Digital Public Infrastructure

Why ChatGPT Ads Deserve a Place In Your 2027 Media Plan

Every performance channel has a window where being early is genuinely worth something, before the auction gets crowded and costs catch up to the value. Google Search had it in the early 2000s. Facebook had it around 2012. TikTok had it a few years ago. ChatGPT Ads is having that moment right now, and a handful of forces are converging to make 2027 the year it stops being optional for competitive categories.

First, the volume is already enormous. ChatGPT is processing billions of prompts a day, and a meaningful share of those are research and decision-making conversations — the exact moment advertisers spend fortunes trying to reach through search and comparison sites. Early advertisers are already seeing it translate into real traffic; Target, for instance, reported 40% month-over-month traffic growth from ChatGPT to its site during the early rollout.


Second, the competitive set is still thin. Ads are only reaching roughly half of eligible responses in the US as of mid-2026, and most advertisers in any given category simply haven’t shown up yet. That’s exactly the kind of gap that closes as more media buyers catch on — and once it closes, the “relevance discount” early movers are currently enjoying narrows. If you’re waiting for the safety of a crowded, well-benchmarked auction before you test, you’re also waiting until the cheap inventory is gone.

Third, the platform’s own roadmap points toward this becoming a full-fledged performance channel rather than a novelty placement. Conversion tracking (a Conversions API and pixel launched May 5), automated bidding, and conversion-based optimization have all landed within a matter of months. That’s the same maturity curve Google Ads and Meta Ads went through, just compressed into a fraction of the time.

Fourth, international expansion changes the calculus for any brand running global campaigns. What started as a US-only test in February had reached the UK, Mexico, Brazil, Japan, and South Korea by August, with India, parts of Europe, and the Middle East and North Africa opening up in September. A 2027 media plan built only around US inventory would already be behind where the platform is heading.

Do You Really Need to Run Campaign on OpenAI

None of this means ChatGPT Ads should replace anything in your current mix. It’s a complement, and a fairly specific one. 

ChatGPT ads strongest for categories where people genuinely research before buying — consumer electronics, home improvement, travel, financial products, higher education, software — because those are exactly the kinds of extended, multi-turn conversations the ad matching is built around. 

It’s a poor fit for anything in the excluded categories (health, politics, mental health), and it’s not yet the place to chase raw reach or awareness at the lowest possible cost, given the CPM sits above social platforms like Meta and closer to LinkedIn’s premium tier.

It’s also not a channel to fund with your test budget’s leftovers. Given the measurement is still aggregated rather than granular, and given automated bidding tools only perform well once there’s a real conversion history to learn from, this works best as a deliberate, funded pilot — enough spend to get past the “five conversions” threshold the platform’s own bidding tools need to function well, run for long enough to see a real trend rather than a single lucky week.

Question Worth Asking Before Shifting Your Marketing Budget

Before you set a number next to “ChatGPT Ads” in the 2027 budget, ask yourself – 

Does your brand already show up when someone asks ChatGPT an open-ended question in your category — with no ad involved? 

Because the sponsored card sits underneath the organic answer, and premium subscribers never see ads at all, meaning the only version of your brand a large and growing share of ChatGPT users will ever encounter is whatever the model says about you unprompted. 

If that organic answer already favors you, every paid dollar on top of it works harder. If it doesn’t, the ad budget is arguably the second problem to solve, not the first.


Your Business Needs a Brand Awareness Or Conversions? 

Brand awareness means getting in front of someone while they’re still researching, before they’ve decided what they want. 

Conversions means catching someone who already knows what they want and getting them to buy or fill out a form. 

Decide which one you’re paying for first, because the budget, the creative, and the way you judge success all flow from that one decision. 

How Ads Target a ChatGPT User?

When someone searches on Google “Best AI Agents for E-Commerce” will get the exact result. ChatGPT works in a different way. Due to the user’s chat privacy, Advertisers don’t get the exact keyword of the search, they are working on a context hint.

ChatGPT itself may understand what a user wants with far more nuance than a Google search does, but as the advertiser, you don’t get that same visibility. You’re targeting in the dark relative to what you’re used to on Search Engine. 

That gap should shape how much you’re willing to spend before you’ve proven the targeting actually reaches the right people.

Shifting From One Running Campaign Budget to Another Platform Is a Risk Marketer Shouldn’t Consider

Shifting a budget from a running campaign on Google Ads to ChapGPT is riskier if you get leads from the first platform already. So why consider ChatGPT ads? Platforms where you didn’t accomplish from the ads, replace that budget into ChatGPT ads. Pull smaller amounts from a few underperforming campaigns or channels instead, so a disappointing ChatGPT Ads result doesn’t cost you revenue you were already counting on.

Conclusion

ChatGPT Ads went from a $200,000-minimum enterprise pilot to an open, self-serve, globally expanding ad platform with automated bidding and conversion tracking in under seven months. That kind of speed doesn’t happen unless there’s real advertiser demand behind it, and real demand tends to mean real results. 

Google is often about: “I searched for something → show me relevant results/ads.”

ChatGPT can involve: “I’m researching something → I’m having a conversation → I’m comparing options → I’m trying to make a decision.”

Because ChatGPT Ads are still relatively new, marketers don’t have the same amount of historical data they have with Google Ads.

The auction is still relatively uncrowded, the CPCs are competitive with established search and social benchmarks, and the platform is adding exactly the tools — conversion optimization, expanded geography, agency integrations that turn a novelty placement into a durable channel.

Leave a Comment

Your email address will not be published. Required fields are marked *

iPhone 18 Pro on EMI: A Complete Buying Guide

iPhone 18 Pro

Apple hasn’t confirmed a single detail about the iPhone 18 Pro yet, but that hasn’t stopped Indian buyers from searching iPhone 18 Pro EMI options months before launch — and for good reason. With expected pricing starting north of ₹1,34,000, paying the full amount upfront isn’t realistic for most people. 

The real question isn’t whether you should use EMI. It’s which EMI actually saves you money, and which one just makes an expensive phone feel cheaper than it is for a few months.

When Is the iPhone 18 Pro Launching in India?

Every recent report points to September 2026, alongside the iPhone 18 Pro Max and for the first time — Apple’s foldable iPhone. What’s changed this year is the rest of the lineup. Bloomberg’s Mark Gurman reported that Apple is splitting its release schedule for the 18 series: only the Pro, Pro Max, and the foldable arrive this September, while the standard iPhone 18 and a new iPhone 18e get pushed to spring 2027. If that holds, this is the first year in a while where the “regular” iPhone won’t launch alongside the Pro models.

Going by Apple’s usual pattern (the iPhone 17 event was held on September 9, 2025, with sales opening ten days later), a keynote in the first two weeks of September 2026 is the safest bet, with stock hitting stores roughly a week to ten days after that. Some trackers are floating September 8–9 specifically; others leave more room, up to September 10. Take the exact date as a placeholder until Apple sends out invites, which usually happens about three weeks ahead of the event.

Expected iPhone 18 Pro Price in India

Price leaks are all over the place right now, which is normal this far out. Here’s the range being reported across sources as of this writing:

VariantExpected India price
iPhone 18 Pro, 256GB₹1,34,900 – ₹1,44,900
iPhone 18 Pro, 512GB₹1,52,500 – ₹1,69,990
iPhone 18 Pro Max, 256GB (starting)₹1,49,900 – ₹1,60,000

A few sources argue Apple will hold pricing close to the iPhone 17 Pro’s ₹1,34,900 launch price, citing “aggressive supplier negotiations” to protect India pricing. Others expect a hike tied to the RAM bump (12GB is the rumored figure) and camera hardware upgrades — the iPhone 18 Pro is rumored to carry a triple 48MP setup with a periscope telephoto lens and a variable-aperture main camera, on a 2nm A20 Pro chip. Rumors are also split on whether Face ID moves under the display this generation or stays as-is; one supply chain report specifically says it won’t happen this year due to production delays.

Budget for the ₹1,34,900–1,44,900 band on the base 256GB Pro, and don’t be surprised if the number lands closer to the top of that range once Apple accounts for import duty and GST on the final config.

What’s the Actual Difference In No-Cost EMI vs Standard EMI? 

This is where most buyers get it wrong. “No-cost EMI” doesn’t mean the bank is doing you a favour — it means the retailer or Apple absorbs the interest that would normally apply, so you pay roughly the sticker price split into installments instead of sticker price plus interest. Depending on the bank, this shows up in one of two ways: the interest is stripped out at checkout, or you’re charged interest upfront and it comes back to you as cashback within about 90 days (this is how ICICI’s scheme works on longer tenures). Either way, you’ll still pay a processing fee, GST on that fee, and — if you close the loan early — a foreclosure charge, typically around 3% of the outstanding principal plus the next month’s interest.

Standard EMI is the version without the safety net: real interest, usually in the 12–16% per annum range on credit card conversions, on top of the base price.

The gap adds up fast. On a ₹1,34,900 iPhone 18 Pro, a 24-month standard EMI at 14% p.a. works out to roughly ₹6,477 a month — about ₹20,500 more than the phone’s actual price by the time you’re done paying. The same tenure under a genuine no-cost scheme costs ₹5,621 a month, with no premium at all. That ₹20,500 difference is the entire reason to check which scheme you’re actually being offered before you tap “confirm” at checkout.

Read More👉 Best Laptops for Coding and Programming: Top Picks for Every Budget

Where You’ll Be Able to Buy iPhone 18 Pro on EMI

You’ll have more than one route in, and it’s worth comparing before you commit to any single one. Apple’s own online store runs its no-cost EMI tie-ups directly with Bajaj Finance, HDB Financial Services, ICICI Bank, IDFC First Bank, and TVS Credit — the current scheme window on Apple’s authorised platforms runs through late September 2026, which should carry into the 18 Pro’s launch. Apple Authorised Resellers such as iStore, Unicorn, Croma, Reliance Digital, and Vijay Sales layer their own instant cashback offers on top for Axis Bank, ICICI Bank, and SBI Card users, usually on 6-month no-cost tenures with low-cost EMI kicking in beyond that.

Amazon and Flipkart are the other major channels, particularly around sale events — Amazon’s Great Freedom Sale and Flipkart’s Freedom Sale both ran in early August 2026, and both platforms typically repeat similar EMI-plus-bank-discount stacking for major flagship launches. Flipkart also supports the Bajaj Finserv Instant EMI Card for buyers without a traditional credit card. Debit card EMI is more limited — HDFC, Axis, and ICICI extend it to pre-approved debit cardholders, but the pool of eligible customers is smaller and interest rates run similar to credit card EMI.

Whichever channel you pick, check the fine print on tenure caps — 6-month no-cost EMI is nearly universal, but 12- and 24-month no-cost schemes are usually restricted to specific banks and specific card tiers.

How Much Will Your Monthly EMI Be?

Based on the expected price bands above, here’s what a genuine no-cost EMI would look like at common tenures:

Tenure256GB Pro (~₹1,34,900)512GB Pro (~₹1,52,500)Pro Max 256GB (~₹1,54,900)
3 months₹44,967₹50,833₹51,633
6 months₹22,483₹25,417₹25,817
9 months₹14,989₹16,944₹17,211
12 months₹11,242₹12,708₹12,908
24 months₹5,621₹6,354₹6,454

These are straight divisions of the expected MRP with no interest added — that’s what “no-cost” is supposed to mean. If a bank quotes you anything higher than these figures for the same price and tenure, ask specifically whether interest is being charged, because it likely is.

Exchange Offer + EMI Combo — Lowering Your Effective EMI

Trading in your current phone reduces the amount you actually finance, which lowers every EMI figure above. As an example: on a ₹1,44,900 iPhone 18 Pro, a mid-range trade-in like a working iPhone 13 128GB might fetch around ₹15,000 in exchange value plus a ₹6,000 exchange bonus — a combined ₹21,000 off, bringing the amount you’d actually put on EMI down to ₹1,23,900. Financed over 12 months no-cost, that’s roughly ₹10,325 a month instead of ₹12,075.

The catch is that the trade-in values swing enormously based on the model, storage, and physical condition of your old device, and different assessors don’t agree with each other. Apple’s own trade-in estimate, a reseller’s in-store quote, and a third-party service like Cashify can differ by several thousand rupees for the same phone. 

Get quotes from at least two sources before you finalise, and remember that exchange bonuses on top of the base trade-in value are usually time-limited promotions, not permanent policy — they’re the kind of thing that disappears the week after a big sale ends.

Step-by-Step Guide To Buying iPhone 18 Pro on EMI

  1. Shortlist your retailer first, not the phone colour. Compare what Apple’s own store, your nearest authorised reseller, Amazon, and Flipkart are each offering on EMI tenure and bank tie-ups — the same phone can carry different effective costs depending on where you buy it.
  2. Check your card’s pre-approved EMI limit. Most banks let you check this via SMS or net banking before you shop, so you’re not caught out at checkout with a card that can’t support the tenure you want.
  3. Get an exchange quote in advance if you’re trading in. Apple’s trade-in tool and your reseller’s in-store estimate both take a few minutes and give you a real number to plan around.
  4. Select the EMI option at checkout that matches your card and target tenure. No-cost options are usually listed separately from standard EMI — don’t assume the first EMI option shown is the no-cost one.
  5. Confirm the breakdown before you pay. Look for a line item showing interest and processing fee separately. If the total EMI amount adds up to more than the phone’s price divided by the number of months, you’re paying interest somewhere.
  6. Read the foreclosure terms. If there’s a chance you’ll want to pay off the balance early, know the foreclosure charge upfront rather than finding out later.
  7. Save your EMI schedule and transaction confirmation. You’ll need these if a cashback-style no-cost EMI scheme (like ICICI’s) hasn’t been credited on schedule.

Read More👉 iPhone 18 Pro Launching Next Month: 12 New Features Worth Knowing About

Conclusion 

The iPhone 18 Pro’s price and launch date will stay rumors until Apple actually sends out event invites, and it’s worth waiting for that confirmation before you lock in a purchase decision — leaked pricing has moved by thousands of rupees between reports even in the past few weeks. 

But the EMI math you plan around today will hold regardless of the exact final price: the difference between a genuine no-cost scheme and a standard one is real money, often ₹15,000–20,000 over a two-year tenure, and it has nothing to do with which bank has the nicest app. 

Compare the tenure and the bank before you compare the storage variant, get your exchange quote sorted early if you’re trading in, and read the checkout screen closely enough to know exactly what you’re signing up for, not just what the monthly number says.

Leave a Comment

Your email address will not be published. Required fields are marked *

Upgrade Laptop Like New Model In Low Budget

Laptop

Upgrade Laptop in low budget is more beneficial than buying a new one. It doesn’t mean that new laptops aren’t worth buying but upgrading from i3 to i7 can be quick and affordable for students. Working on a laptop which takes minutes to open and making noises while turning on kills the vibes for coding, gaming, or video editing.

However, it is worth knowing before making a decision to buy a brand new laptop this festive season, the machine slowing you down probably isn’t dying — it’s just outdated in one or two specific ways, and fixing those is often a fraction of the cost of a new one.

Laptop upgrades on a budget aren’t about replacing everything. Find the vulnerability of the system caused by one or two old elements and change it. Most 3–5 year old laptops are held back by Hard Drive and RAM most of the time. Fixing both can allow users to experience faster and smooth performance.

But how you can upgrade laptop like a brand new is something to understand first before buying anything you find on flipkart or amazon.

Diagnose Your Laptop Internally

This step is crucial because without knowing the cause of your system, how can you fix it? If you skip the diagnosis, and buy $60 RAM but end up waiting for your computer to respond faster and do the work, you wasted your money. 

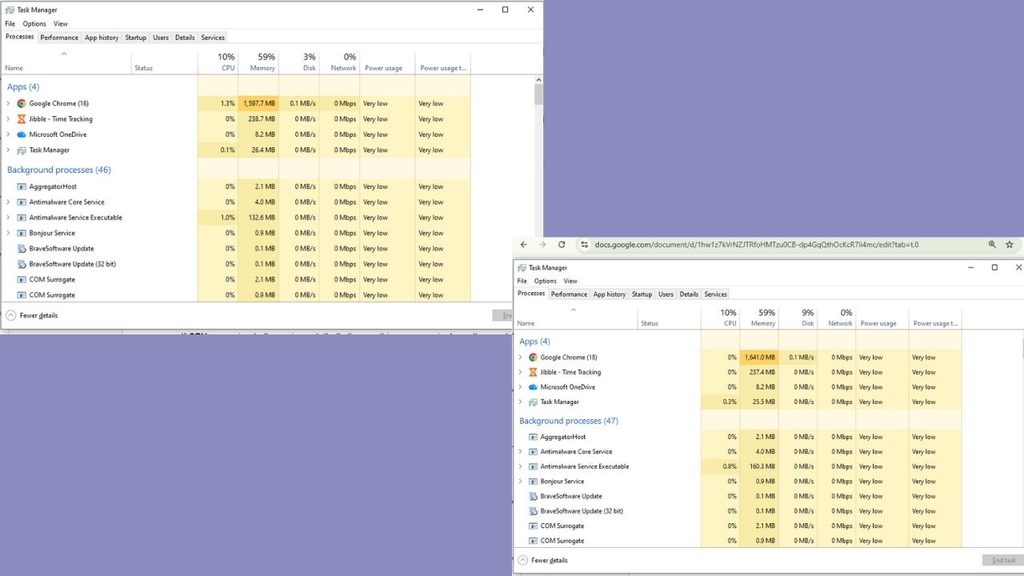
So Open Task Manager on Windows — shortcut keys are Ctrl+Shift+Esc or in MAC — go to Activity Monitor and watch it for a minute while working usually.

Check These Three Things in Your System:

The task manager shows you how much usage has been used to run your apps, if it’s near 100% then your storage drive is the bottleneck — almost certainly a traditional hard disk drive (HDD). Most of the older laptops suffer from this issue that’s why they’re too slow and fixing it (with SSD) is the cheapest and highest impact upgrade for your laptop.


Memory usage above 85% continuously means more RAM is needed. Heavier apps like Zoom, Team and Word running altogether with 15 browser tabs should be run smoothly at 8 GB. But if building applications and gaming is your main course then you need more than 8 GB. Since this amount is default on a lot of budget and mid-range laptops sold in the last five years.

If CPU usage is the thing hitting its limit, that’s one part you generally can’t upgrade on a laptop. CPU bottleneck won’t be solved by swapping components because it is soldered to the motherboard usually so knowing it before you start spending your money on an upgrade that won’t help is important.

Most people diagnosing a “slow laptop” for the first time are surprised to learn its disk, not processor. That distinction is the whole game.

SSD Swap: The Single Best Upgrade You Can Make

By replacing a mechanical hard drive with a Solid State Drive is the single most efficient upgrade that makes a laptop feel like new hardware. It improves the speed and multi-tasking process, boot times can drop from 90+ seconds to under 15 and regular tasks like switching between apps or opening them won’t lag.

A basic 480GB–500GB SATA SSD, such as the Crucial MX500, Kingston A400, or WD Blue, usually costs around ₹2,500–₹3,500 in India, depending on ongoing pricing and sales. The price is far less than buying a whole new laptop, this upgrade can make your older laptop fresh.

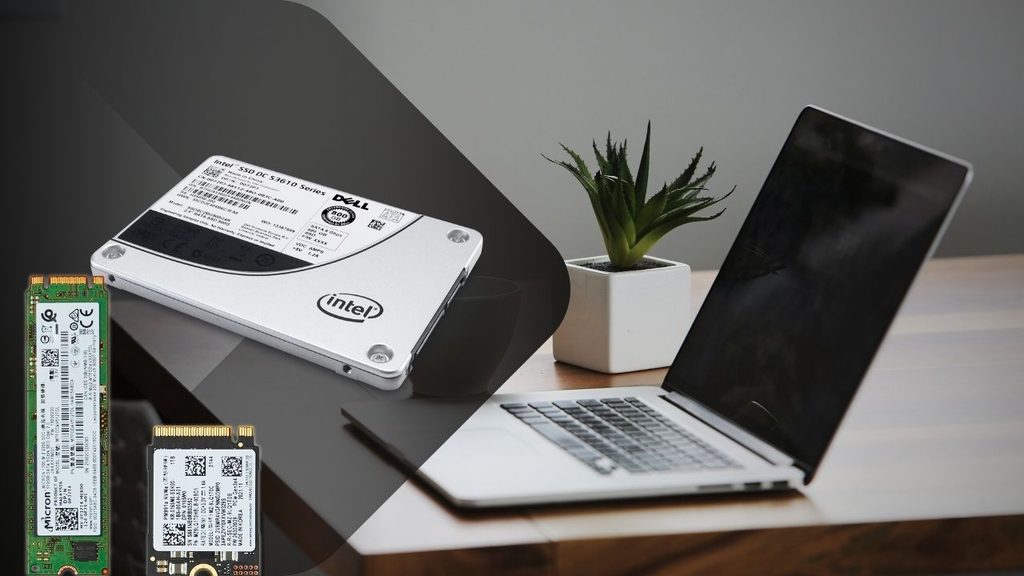
Before buying an SSD, confirm two things: whether your laptop has a 2.5-inch SATA bay, an M.2 slot, or both (this determines which SSD form factor you need), and whether it has a spare slot or you’ll be replacing your existing drive entirely. Most laptops from 2016 onward that shipped with an HDD have a 2.5-inch bay that’s a direct, tool-light swap — usually just a few screws on the base panel.

There’s two options always given to you while rebooting, keeping your existing Windows installation and files onto the new drive or clean installation. If you choose to keep, Cloning software like Macrium Reflect (free tier) or EaseUS Todo Backup will help transfer your programs and settings from old HDD onto the new SSD so you don’t need to reinstall and set things up.

If the laptop is too old then fresh Windows installation onto the new SSD is a better option, it removes old or hidden leftover junk which consumed your memory.

See Details:- iPhone Duo Changes the Cost Effectively With These Methods

Add RAM: The Second-Cheapest Speed Fix

If your diagnostic check flagged high memory usage, this is your next move, and it’s usually inexpensive. Most laptops from the last decade that have 4GB or 8GB of RAM have room to go to 8GB or 16GB, either by adding a stick into a free slot or replacing existing sticks with higher-capacity ones.


It’s not a costly upgrade, an 8GB DDR4 SODIMM stick price is somewhere around
₹1,500-₹2,200 depending on the current market.

Before Buying, Check Which Type Of Ram is Compatible

Your laptop’s supported RAM type (DDR3 vs DDR4 vs DDR5 — check your model’s spec sheet, since installing the wrong type simply won’t work) and its maximum supported capacity, because some budget laptops cap out at 8GB even if there’s a second slot.

The install itself is usually the easiest upgrade on this list — a single panel on the bottom of most laptops, a couple of screws, and the RAM stick clicks into a slot at an angle before you press it flat. 

No cloning, no software, no reinstalling anything. If your laptop’s diagnostic showed disk usage as the real bottleneck rather than memory, though, don’t bother with this one first — RAM won’t fix a slow HDD, and you’d be spending money on the wrong problem.

Clean Out the Software Bloat You’ve Been Carrying for Years

Hardware isn’t the whole story. A laptop that’s had the same Windows installation for three or four years accumulates a genuinely surprising amount of drag: startup programs that launch silently every boot, background services from software you uninstalled ages ago, and browser extensions you forgot you added.

Open Task Manager’s Startup tab and disable anything you don’t need running the moment you log in — most people find five to ten programs quietly launching that have no business doing so (Spotify, printer software, half a dozen “helper” apps from programs installed years ago). This alone can shave real time off boot-up without touching a single piece of hardware.


Beyond that, uninstall software you genuinely don’t use anymore, clear out temp files (Windows’ built-in Disk Cleanup or Storage Sense handles this automatically), and check your browser extensions — each one adds a small but real memory and CPU tax that compounds when you’re already running an older machine.

If your laptop has never had a clean OS reinstall after SSD swap, this is the moment to consider it. A fresh Windows install onto new hardware, with only the software you actually use, often produces the single most dramatic “this feels like a new laptop” moment of the entire process — more than any single component swap.

Read More:- How AI Could Change India’s Digital Public Infrastructure

Don’t Skip the Physical Cleaning

This one costs close to nothing and gets ignored constantly. Laptops that have run for years without ever being opened up accumulate dust inside the fan and heatsink assembly, which traps heat, which causes the CPU to throttle its own performance to avoid overheating — meaning your laptop is deliberately slowing itself down to protect itself.

To reduce fan noise and prevent thermal throttling, cleaning fan blades and heatsink fins can be helpful. Replace dried-out thermal paste so it brings down temperature between the CPU and heatsink. It can cost around ₹300, and helps the laptop’s processor maintain its performance for longer under heavy workloads. 

This is the cheapest and under-appreciated fix but helps cool the processor because dust buildup and dried thermal paste don’t trigger warning as hard drive does, they just slow your laptop and get a little hotter all the time.

Small External Upgrades That Change How the Laptop Works

Not every upgrade needs to happen inside the case. Coders and Gamers need big screen resolution, a budget external monitor changes the entire experience without spending a new laptop’s cost.


Additionally, better-quality external keyboard and mouse will maximize that experience by making typing and navigating more easy and responsive, even if the internals haven’t changed at all.

A basic cooling pad (₹800-₹1,500) can also help laptops that run hot during longer sessions, buying you more sustained performance during demanding tasks like video calls or heavier multitasking, without opening the machine at all.

Know When Upgrading Laptop Stops Making Sense

If the laptop’s bottleneck isn’t the RAM and disk but CPU then do not spend a single rupee on the laptop upgrade because it’s useless. The process is the one component you almost never can replace on a laptop.

Old laptop battery-life usually degraded to holding half its original charge. Changing that will help if your laptop is just 2-3 years old because a five-plus years old laptop doesn’t come with a user-replaceable battery so that’s where you should start saving for a new laptop. It’s worth actually comparing the two costs side by side rather than assuming the upgrade is always cheaper. 

Read More :- Why ChatGPT Ads Deserve a Place In Your 2027 Media Plan 

Conclusion

If you’re staring at a slow laptop right now, check Task Manager first. If disk usage is maxed out, an SSD swap is your highest-impact move and should come before anything else. If memory is the constraint, add RAM — it’s cheap and takes ten minutes. 

Do both of those, clean out years of startup bloat, blow the dust out of the fans, and you’ve addressed the four things that account for the vast majority of “this laptop feels old” complaints — usually for less than a tenth of what a new laptop would cost.

Overall, if your bottleneck turns out to be the processor itself, no combination of these fixes will get you there, and that’s the one scenario where saving up for new hardware is genuinely the right call instead of the expensive-sounding one.

Leave a Comment

Your email address will not be published. Required fields are marked *

Scroll to Top