Your Dollar Income Isn’t Fixed: How INR Volatility Changes Freelancers Earning 

INR Volatility

If you are a student or IT engineer and have a side freelancing business then exchange rate updates is the second in your search list. Once you understand Impact of Exchange Rates On Freelancers In India and how it moves forward then you can earn a little more. Let’s take a look at some important points to understand INR Volatility isn’t about what you’re actually thinking.

You raised the invoice in August. $1,000, net 30, client in Austin. By the time the payment actually lands in your account in September, the number in rupees isn’t what you calculated when you sent it. Maybe it’s more. Maybe it’s less. Either way, you didn’t do anything different — the client paid exactly what they owed — and your income still moved. 

That gap is what most freelancers mean when they say the rupee is “volatile,” and most of them are only half right about what that word actually costs or earns them. 

Current Changes In INR Volatility 

As of September 9, the dollar was trading around ₹95.13, after touching two-month highs near ₹94.4 the week before on the back of sustained Reserve Bank of India intervention. Zoom out to the 12-month view, the rupee has weakened roughly 8% against the dollar over the past year. For a freelancer billing in USD, that’s not a warning sign — it’s a raise you didn’t ask for.

Run the math on a flat $1,000 invoice. At a rate near ₹88 (roughly where the pair sat a year ago, working backward from the reported annual move — treat this as an approximation, not a verified historical quote), that invoice cleared around ₹88,000. 

At today’s rate, the same $1,000 clears closer to ₹95,000. Same client, same scope, same invoice — ₹7,000 more in your account, before any platform fees. If your Gigs, your budgeting, or your client pricing only accounts for the dollar amount, you’re missing the part of your income that moved on its own.

Why “Volatile” Doesn’t Mean “Falling” 

If you thought “the rupee is volatile” means “the rupee is always losing value, brace yourself.” But that’s not what volatility means, and it’s not what the data shows. The rupee gained about 0.9% in the week leading into September 9, with the RBI actively defending the band using its foreign exchange reserves. A currency that can move up or down 1% in a week, depending on which government or central bank decides to act, is unpredictable — not one-directional.

The near-term pressure right now is coming from oil. Brent crude jumped roughly 8% to around $97 a barrel after US-Iran tensions escalated, and India imports the overwhelming majority of the crude it uses, so a sustained spike pushes the rupee the other way — weaker, which again works in a dollar earner’s favor, but also raises input costs across the economy, indirectly squeezing the Indian clients some freelancers also serve. 

Layer on the US Federal Reserve’s meeting scheduled for September 15–16, where a rate move could swing global dollar demand overnight, and you’ve got a currency pair reacting to three or four separate levers in the same month. Betting on “the rupee only goes one way” is how freelancers get caught flat when it doesn’t.

Read More 👉 UP Anganwadi Bharti 2026 — District-Wise Vacancies & Recruitment Details

Impact of Exchange Rates On Freelancers In India

Here’s the part that costs freelancers real money and rarely makes it into the currency conversation: the spread between the rate you see on Google and the rate you actually receive. This gap is usually bigger than the market’s actual weekly movement. And it fills only when you understand Impact of Exchange Rates On Freelancers In India.

PayPal is the most expensive route by a wide margin — a cross-border transaction surcharge that can run up to 4.4%, stacked with a currency markup of roughly 3.5–4.5%, pushes total cost toward 6% on some routes. 

Payoneer, common for Upwork and Fiverr payouts, charges around 1% to move funds to your bank plus an FX markup that can reach 2% on withdrawal into a different currency — so a $2,000 month can quietly lose $50–60 to fees that never show up as a single visible number. 

Wise is the outlier: it settles at the mid-market rate — the actual number you’d see on Google — with a transparent fee that’s usually under 1% for most USD-to-INR transfers, which is why it’s become the default for freelancers paid directly by clients rather than through a marketplace.

None of that shows up when you’re only watching the headline USD/INR number. A freelancer who tracks the exchange rate obsessively but invoices through PayPal is optimizing the wrong variable.

Read More 👉 Foreign Education Loan Currency Explained: How INR Depreciation Can Increase Your Loan Cost 

How To Check Your USD Income is Moving Forward

Stop checking “what’s the rupee doing today” in isolation. Three things move it, and all three are trackable without a finance degree: RBI intervention behavior (visible in how tightly the rate is held to a band, like the ₹94.5–95.3 range this week), Fed rate decisions (scheduled, public, and usually priced in days ahead), and oil price swings (Brent crude, since India’s import bill is the direct transmission line into rupee weakness or strength).

Practically, that means two things for how you run your freelance income. First, match your payout method to your income source — Payoneer if most of your work comes through marketplaces, Wise if you invoice direct clients — because the fee gap between them is often larger than a month’s currency movement. 

Second, if you’re pricing recurring retainers in USD, revisit them quarterly rather than annually; an 8% currency shift plus a fee structure you haven’t audited in a year is easily a 10–12% swing in what a “fixed” retainer actually pays you in rupees.

Your dollar invoice was never the number that mattered. The rupee number that hits your account is — and that number has three separate forces acting on it before you even get to the part your payment platform quietly takes.

Read More 👉 Planning MBBS or Master’s Abroad? Country-Wise Costs, Loan Limits and Lenders

Conclusion 

For Indian freelancers, earning in dollars doesn’t mean earning a fixed amount. The USD/INR rate, RBI and Fed decisions, oil prices, and payment-platform fees can all change what finally reaches your bank account. A $1,000 invoice can be worth noticeably more or less in rupees without the client changing a thing.

The smart move isn’t to predict the impact of Exchange Rates On Freelancers In India. It’s to understand how currency movements affect your real income, compare payout fees, and review your USD pricing regularly. For IT students planning to freelance or work with overseas clients, learning this early can help turn Dollar Income into something you can actually budget around.
Leave a Comment

Your email address will not be published. Required fields are marked *

UP SuperTET Vacancy Notification 2026: Check Out Details, Dates, & Eligibility

SuperTET

If you’ve been searching continuously on Google for “UP SuperTET 2026 Notification Out, you are not alone because many future teachers are googling it but don’t panic. You are not late, because the official notification has not been released yet. The vacancy numbers are a guess if you see anywhere.  

When Will The UP SuperTET Notification Get Released?

UPBEB is going to publish the SuperTET 2026 notification soon and it carries the exam date, required documents, eligibility, and exam pattern information for the candidates. The best way of starting the process is to read that notification carefully once it is released before going to fill the form for UP SuperTET 2026. 

It’ll land after the UPTET result is out, so most of the candidates get eligible for the SuperTET so there should be a larger number of vacancies. But that’s an educated guess about timing, not a commitment from the The Uttar Pradesh Basic Education Board. 

Where You Can Find The SuperTET Updates? 

Skip the YouTube shorts and forward-heavy WhatsApp groups. The two sources worth bookmarking are:

Vacancy For UP SuperTET Exam 2026

From the past cycle and current teacher-shortage data, it is precisely reasonable that UP SuperTET 2026 Vacancy lies around 69,000, 85,000. But these numbers aren’t shared by the officials so treat them as a closer guess. 

The 2019 SuperTET drive filled around 69,000 posts so it became the usual provisional around number. Until UPBEB publishes district-wise and category-wise vacancy breakdowns in the actual notification.

SuperTET Salary and Eligibility 

Vacancy and dates can change year by year but 80% of the stuff is the same each year. SuperTET eligibility, salary, exam pattern are not going to change, even if it does, only slight change can happen. 

ParameterDetails
PostAssistant Teacher – Primary (Classes 1–5) and Upper Primary (Classes 6–8)
Pay Scale₹35,400 – ₹1,12,400 (Level 6, 7th Pay Commission)
EligibilityValid CTET or UPTET:- Paper I for Primary (Classes 1–5)- Paper II for Upper Primary (Classes 6–8)Plus relevant qualifying degree and/or B.Ed as per recruitment rules
Exam PatternObjective-type test, 150 marks, covering:- Language proficiency- Pedagogy (teaching methodology)- General Knowledge- Subject-specific content knowledge

Qualifying Numbers are easily let you pass by acquiring 40% (60/150) if you are General category candidate and 33% (49.5/150) for the candidates who belong to SC/ST/OBC-NCL/PwD but they are not a scoring score to win this battle among thousands candidates. 

Actual merit cutoff: if you actually want to get selected then score from 90 to 130+ out of 150 to hold out your position. These are the actual merit numbers, it also depends up on your category and how many seats are open. 

That gap between “qualifying score” and “actual selection score” trips people up every cycle. SuperTET isn’t a pass/fail eligibility test — it’s a straight competitive recruitment exam. Scoring the minimum gets you nowhere near a job.

UPSSSC PET Exam Date 2026 Out

How To Prepare Yourself For The Exam

  1. Don’t wait to start preparing. The syllabus and pattern are already finalized by UP authorities, which is usually a sign the recruitment machinery is moving even if the notification isn’t out yet.
  2. Keep your CTET/UPTET certificate and documents ready. Once the form opens, the window is typically short — 20 to 30 days and document scrambling under deadline pressure is a self-inflicted wound.
  3. Ignore vacancy-number debates on social media. They change nothing about your prep and mostly exist to farm engagement.
  4. Set a check-in habit, not a refresh habit. Checking the official website once a day is enough. Constant refreshing just adds stress without adding information.

Conclusion 

Start focusing on the syllabus, pattern, expected post structure before UP SuperTET 2026 Notification Out because it’s released, you won’t get enough time to prepare after that. There’s no confirmed vacancy count but there’s a guessing number, the competition will be higher. 

Prepare like the exam is close, because structurally it looks like it is, but don’t let unverified numbers shape your expectations or your plans.

Always cross-check every information on the official website of UP Super TET 2026 Notification Out before acting on any detail published by educational sites.

Leave a Comment

Your email address will not be published. Required fields are marked *

Festive Season Sale In October Is About to Reshape Smartphone Prices in India 

Festive Season Sale

This year’s Festive Season Sale In October will bring many new offers and discounts on electronic products — massive offers hit on smartphones. If you’ve been sitting on an upgrade — whether that’s finally moving off a three-year-old Galaxy or jumping into the iPhone ecosystem for the first time — this is the window the entire Indian smartphone retail calendar builds toward. 

When the sale is live, which smartphone will actually get a discount and what’s coming to this season, know everything before planning around.

When Does the Festive Season Sale Start?

The Amazon Great Indian Festival 2026 is going live on October 8 with no closing date, so treat this as a multi-week sale. Prime members get early access from October 7. This Festive Season Sale has flagged on many categories, including mobile phones, electronics, home appliances, and fashion. With 160,000 seasonal jobs secured by Amazon to handle the load, this shows how big this year’s event is expected to be.

Flipkart’s Big Billion Days 2026 goes live for everyone on October 9, a day after Amazon, with early access on October 8 for Flipkart Plus, Flipkart Black and select co-branded credit card holders. Flipkart has also been running a slower build-up than usual: Early Bird Deals started September 24, and official price reveals on flagship phones have been trickling out since September 26.

October 7–9 for early access across both platforms, then the main event running through most of October. If you’re the type who wants to plan a purchase around the calendar rather than react to a flash notification, mark October 7 as your first checkpoint.

What Discounts and Bank Offers to Expect

Neither platform has published final smartphone pricing yet — genuinely, this is one area where numbers are still moving daily, and anyone claiming exact final prices two weeks out is guessing. What’s confirmed on the banking side is more solid:

On Amazon, SBI credit and debit card users get a flat 10% instant discount on eligible transactions, including EMI purchases, and Amazon has said overall discounts across electronics could run up to 80%, with an additional 10% on top for SBI cardholders. There’s already a Prime Coupon Bonanza running ahead of the main event, offering up to ₹6,000 off select Samsung and Sony televisions — a hint at how aggressive the electronics category is shaping up to be.

On Flipkart, Axis Bank and ICICI Bank cardholders get a 10% instant discount on eligible debit and credit card transactions, Flipkart Plus and Black members get up to 12% additional card discount, and Bajaj Finance EMI options are being pushed hard for higher-ticket purchases like flagship phones. Flipkart is projecting discounts climbing as high as 90% across electronics, appliances, fashion and home decor — though that ceiling figure almost always applies to accessories and older inventory rather than current-generation flagships.

Best Smartphone Deals Expected This Festive Season

1. iPhone 17 (256GB) — Best for iOS Upgraders on a Budget

The launch price of iPhone 17 is ₹82,900 for 256GB storage but if you purchase 512GB, the price rises up to ₹1,02,900. Flipkart’s dropping iPhone 17 price under ₹80,000 during Big Billion Days. From above Rs 1 lakh to Rs 80 thousand, the difference is quite big.


At a sub-₹80,000 price point, this is the cheapest true current-generation iPhone has ever launched into a festive sale with outstanding features including 6.3-inch Super Retina XDR display, A19 chip, dual rear camera system. It is available in 5 colours — Black, White, Mist Blue, Sage and Lavender.

Limitation: You still don’t get the telephoto lens or ProMotion display that the Pro models carry, so heavy zoom-shooters and gamers chasing 120Hz will feel the gap. But a perfect model for anyone upgrading from an older iPhone who needs a clear camera and high-end features.

👉 Why ChatGPT Ads Deserve a Place In Your 2027 Media Plan 

2. Samsung Galaxy S25 Ultra — Best Flagship Value Pick

Samsung put the launching price ₹1,29,999 on Galaxy S25 Ultra which was around ₹84,999 after a discount during Amazon’s July Prime Day and as low as ₹94,999 during the May Great Summer Sale and both offers flagged by the same retailer. Now it’s preparing for the festive push. Expect festive pricing to land in a similar ₹85,000–₹95,000 band.


You’re getting a phone that was a ₹1.3 lakh flagship a year ago for roughly two-thirds the
price. Buyers who are searching for best cameras and display smartphones can afford the Snapdragon 8 Elite for Galaxy chipset, which still holds up against 2026 competition. The flagship specifications 6.9-inch Dynamic AMOLED 2X display at up to 2,600 nits brightness, 12GB RAM, titanium frame with Corning Gorilla Armor 2 glass. 

Limitation: It’s now the previous generation — no Galaxy S26’s Snapdragon 8 Elite Gen 5 or the newer Privacy Display feature, and Samsung’s software support clock started a year earlier than on the S26.

3. Samsung Galaxy S26 Ultra — Best for the Latest Hardware

Another Samsung’s flagship model launched in 2026 at ₹1,39,999 for 12GB+256GB and for higher storage, price rises up to ₹1,59,999 for 512GB and ₹1,89,999 for 16GB+1TB. This smartphone is delivering a high-end technology — Snapdragon 8 Elite Gen 5 for Galaxy, 6.9-inch display and first built-in Privacy Display for limiting side-angle screen visibility. The festive offer lands near ₹1,24,999 because July sale cuts to the same.


A 200MP main camera with an absolute hardware system which can’t be broken easily. Buyers who are looking for 2026 latest smartphones at a range over 1 lakh, this is the best time to think about it.

Limitation: Because it’s this fresh, don’t expect S25 Ultra–style 35% festive cuts. If your budget caps around ₹1 lakh, the S25 Ultra is the more realistic festive buy.

4. Samsung Galaxy S25 FE — Best Mid-Flagship Pick

Flipkart teased S25 FE deals alongside the S25/S25 Ultra as part of its Big Billion Days smartphone lineup, Galaxy S25 FE discounted prices will land near ₹60,000. Buyers who can’t afford S26 Ultra for the series design language and camera hardware, this one provides them the same two features at an affordable range in this festive season.

Limitation: Detailed specs and confirmed pricing are still pending official reveal — if you need certainty before buying, wait for Flipkart’s price-reveal window closer to the sale date rather than an early-bird listing.

👉 Apple iPhone Duo Changes the Cost Effectively With These Methods

Compare iPhone 17 vs. Galaxy S25 Ultra On an Overview

iPhone 17 (256GB)Galaxy S25 Ultra (256GB)
Expected festive priceUnder ₹80,000₹85,000–95,000 (based on recent 2026 sale pricing)
Display6.3″, Super Retina XDR6.9″, Dynamic AMOLED 2X, 2,600 nits
Standout strengthCleaner ecosystem, resale valueBigger screen, S Pen support, titanium build

If display size and a stylus matter more to you than the Apple ecosystem, the S25 Ultra is the better festive buy at a comparable post-discount price. If you want the newest chip generation with the smallest footprint, the iPhone 17 wins.

Don’t Lock Into One Platform Too Early

Amazon and Flipkart are running near-identical bank-offer structures this year, but the specific phone deals won’t be identical — Samsung’s S25 Ultra pricing has historically differed by a few thousand rupees between the two platforms in past sales, and the same is likely this October. 

Check both listings once early access opens on October 7–8 before finalising a purchase; a single-retailer comparison isn’t a real comparison.

👉 Upgrade Laptop Like New Model In Low Budget

Conclusion

If your budget is under ₹80,000 and you want the newest possible chip, wait for the iPhone 17’s Festive Season Sale price to drop and buy it in the first 48 hours of early access — historically, the steepest festive cuts on genuinely new-generation phones show up early, before stock tightens.

If you’re chasing flagship specs on a ₹85,000–95,000 budget, the Galaxy S25 Ultra is the stronger buy this cycle, since last year’s flagship pricing has already proven it can fall that far. And if you specifically want Samsung’s newest chip and can stretch past ₹1.2 lakh, hold out for the S26 Ultra rather than compromising — buying older hardware you’ll regret in a year isn’t really a discount.

One practical step regardless of which phone you pick: add it to your Amazon or Flipkart wishlist now, and note the current listed price before October 7. That’s the only way to verify a “festive discount” is real rather than a price that was quietly bumped up the week before the sale.

Leave a Comment

Your email address will not be published. Required fields are marked *

Collateral vs No Collateral Loan Amount Where Collateral Starts Making Financial Sense

Collateral vs No Collateral Loan

Ask most people whether a secured loan beats an unsecured one, and they’ll say yes without blinking — lower interest rate, obviously better. That’s the assumption. It’s also where the math quietly falls apart, because a lower rate on paper doesn’t always mean a lower cost in your pocket. Don’t get confused about Collateral vs No Collateral Loan, understand where it matters.

Whether collateral actually saves you money depends on how much you’re borrowing, and more specifically, on what kind of asset you’re pledging to get that lower rate.

This isn’t a “secured is always cheaper” point. It’s about the exact moment moves depending on the collateral where the interest-rate discount stops being eaten alive by fees, valuation costs, and paperwork.

What Changes When You Add Collateral to a Loan

A collateral loan amount decision comes down to three things shifting at once, not just the rate.

The interest rate drops, because the lender’s risk drops. If you default, they recover the loan by selling or auctioning the pledged asset. As of late 2026, unsecured personal loans in India typically run 11–18% per year for a reasonably qualified borrower, and unsecured business loans usually start closer to 16%. Gold loans from banks price between roughly 8.5% and 12%, and loans against property (LAP) generally fall between 8.5% and 14%, though NBFC gold loans for weaker profiles can climb well past 20%.

Fixed costs show up that don’t exist on an unsecured loan. Asset valuation, legal verification, mortgage registration, sometimes insurance on the pledged asset. These are flat charges — they don’t scale down for a small loan the way percentage-based interest does.

Your money moves slower, and your asset stops being liquid. A personal loan can land in your account same-day. A property-backed loan needs valuation, title checks, and registration, which can take one to three weeks. During that time, and for the life of the loan, that asset is off the table if you need to sell it, gift it, or use it as collateral again elsewhere.

That third point is the one people underweight, and it matters more as the loan amount grows, not less which is part of why there’s no single “collateral is worth it above this number” answer.

The Real Threshold Depends on Which Asset You’re Pledging

The breakeven point isn’t one number in Collateral vs No Collateral Loan. It’s a different number for every type of collateral, because the fixed costs attached to each one are wildly different.

Gold or fixed-deposit collateral has almost no fixed-cost floor. A gold loan can be sanctioned in under an hour, valuation is done on the spot, and processing fees run 0.25–1% of the loan amount — often just a few hundred rupees on a small ticket. Because there’s barely any fixed cost to clear, a gold loan can make financial sense on amounts as small as ₹50,000–₹1 lakh. The rate gap versus an unsecured loan (often 4–8 percentage points) starts saving you money almost immediately.

Property as collateral (LAP) is the opposite case. Valuation fees, legal verification, and mortgage registration or stamp duty typically add up to somewhere between ₹15,000 and ₹30,000, depending on the state and lender — and that’s before you factor in the two-to-three-week processing time. On a small loan, that fixed cost can wipe out most or all of the interest savings. LAP generally only starts making financial sense somewhere in the ₹5–8 lakh range, and it becomes clearly worthwhile above ₹10 lakh, where the fixed costs shrink to a rounding error against the total interest saved.

Vehicle or equipment-backed business loans sit in between — moderate valuation costs, faster processing than property, and a breakeven point that usually lands somewhere in the ₹2–4 lakh range.

A Quick Numbers Comparison 

Here’s a simplified comparison over a 3-year tenure, using a representative unsecured rate of 15–16% against a representative secured rate of 10% (gold loan) or 10% (LAP), before fixed costs:

Loan AmountInterest Paid Unsecured (~16%)Interest Paid Secured (~10%)Raw Interest SavedTypical LAP Fixed CostsNet Saving After Fixed Costs
₹1,00,000~₹25,000~₹16,000~₹9,000N/A (use gold loan, not LAP)Gold loan: still net positive
₹2,00,000~₹53,000~₹32,000~₹21,000~₹20,000Roughly breakeven
₹5,00,000~₹1,33,000~₹81,000~₹52,000~₹20,000~₹32,000 saved
₹15,00,000~₹3,98,000~₹2,42,000~₹1,56,000~₹25,000~₹1,31,000 saved

Note: these are illustrative figures based on representative rate bands, reducing-balance EMI math, and typical fee ranges reported by Indian lenders as of August 2026. 

The pattern holds regardless of the exact numbers: 

On a ₹1 lakh loan, a gold loan wins easily because there’s almost no fixed cost standing between you and the rate discount. On a ₹2 lakh loan taken as a property-backed loan specifically, the fixed costs and the interest savings roughly cancel out — which is exactly why lenders rarely push LAP that small in the first place. By ₹5 lakh and above, the fixed cost stops mattering and the rate gap does all the work.

When Collateral Still Doesn’t Make Sense, Even Above the Threshold

Crossing the breakeven number doesn’t automatically make collateral the right call. A few situations flip the decision back toward unsecured, even at a large loan amount and you started searching for  Collateral vs No Collateral Loan.

  • You need the money in days, not weeks. An unsecured personal loan can disburse within 24–48 hours. A property loan’s valuation and registration process can eat two to three weeks — a real cost if the need is urgent (medical, a time-bound business opportunity, an admission deadline).
  • The asset has a use you’d lose access to. Gold jewelry you might need to sell or gift, or a property you’re planning to sell within the loan tenure, becomes harder to move once it’s pledged. Foreclosure and part-release processes add time and fees of their own.
  • Your income is genuinely unstable. Secured loans still get called in on default — the lender auctions the asset. If repayment is uncertain, adding “losing the collateral” on top of “damaged credit score” is a worse outcome than an unsecured default alone, all else equal.
  • The rate gap has shrunk. RBI rate cuts through 2025 and 2026 have compressed the spread between top-tier unsecured personal loans (some starting near 10%) and secured options in certain cases. Always compare Collateral vs No Collateral Loan live quotes — a hypothetical rate gap on a post isn’t the rate you’ll actually be offered.

Which One Should You Pick Between Collateral vs No Collateral Loan?

Match the collateral type to the loan size, not the other way round:

  • Borrowing under ₹2 lakh and you own gold or have a fixed deposit sitting idle? Pledge it — the fixed-cost floor is low enough that it almost always wins over an unsecured loan.
  • Borrowing ₹2–5 lakh? Run the actual numbers from at least two lenders before deciding. This is the genuine grey zone where fees can cancel out the rate advantage.
  • Borrowing ₹5 lakh or more and you have a property or a high-value asset to pledge? Collateral almost always wins on cost, provided you can tolerate the slower disbursal and the asset being locked up for the tenure.
  • Need the money within a week, regardless of amount? Unsecured is usually the only realistic option, and the speed premium is worth paying for.

The rate on the sanction letter is only half the decision. The other half is whether your loan amount is big enough to make the fixed costs of pledging that asset disappear into the background — and that number changes depending on what you’re pledging, not just how much you’re borrowing.

Read More 👉 Your Credit Score Ignores 90% of Your Financial Life — What Your First Credit Card Changes 

Conclusion

Collateral doesn’t automatically make a loan cheaper if you understand at what point it financially makes sense then you won’t get confused ever. The loan amount, the asset you pledge, and the rate difference all have to work in your favour. 

Which kind of loan you are seeking is also a matter, Gold or FD-backed loans can make sense even at smaller amounts because their upfront costs are low, while other higher loans such as property-backed loans usually need a much larger ticket before the interest savings outweigh valuation, legal, and registration costs.

Collateral vs No Collateral Loan is not a big confusion, there is no universal ₹5 lakh or ₹10 lakh cutoff where collateral suddenly becomes worth it. So you must understand where your interest savings finally outweigh the real cost and inconvenience of pledging the asset. 

Leave a Comment

Your email address will not be published. Required fields are marked *

Apple iPhone Duo Changes the Cost Effectively With These Methods

Apple iPhone

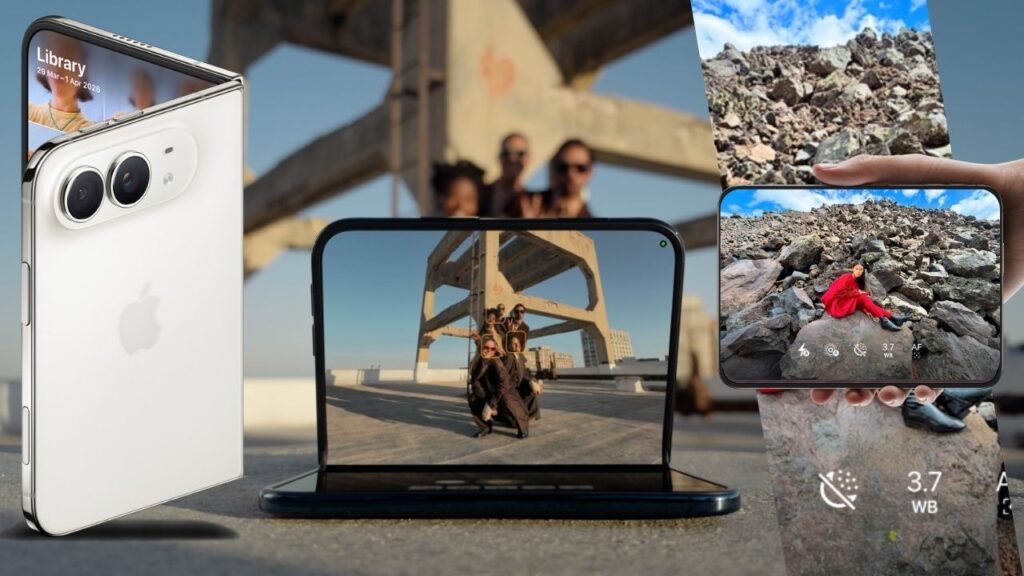
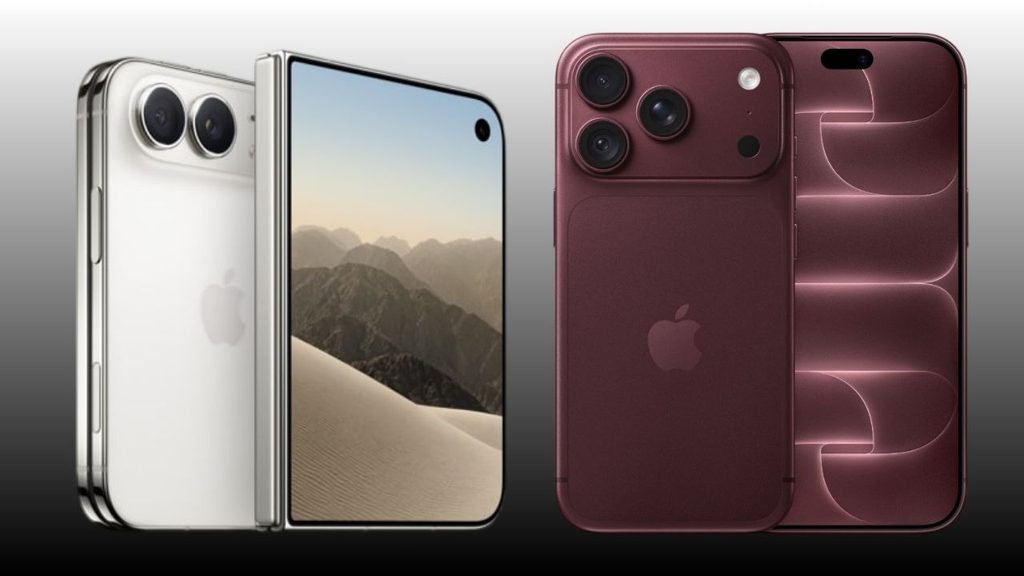
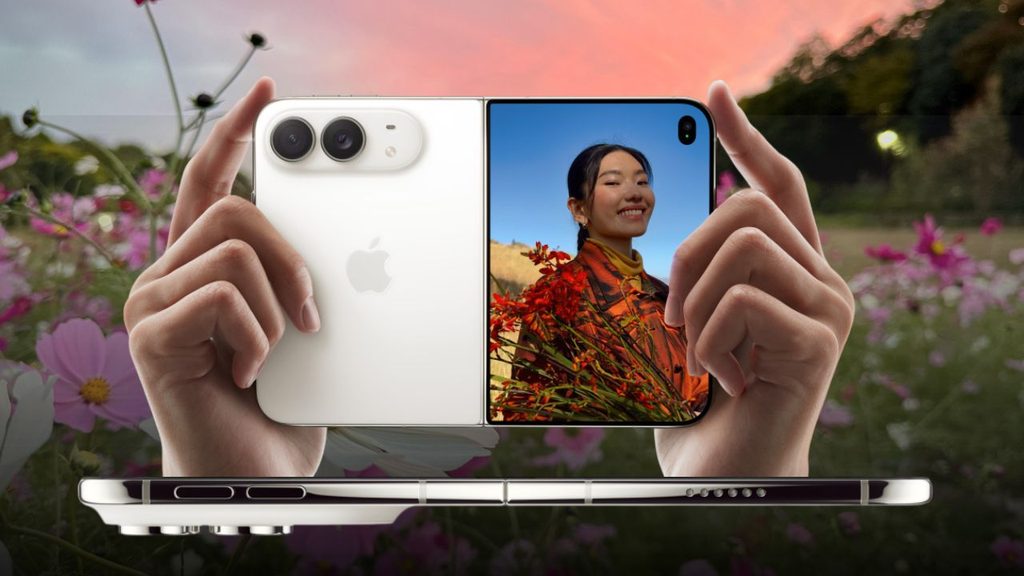
The Apple’s iPhone Duo is unlike any iPhone before with foldable versatility and 50% larger screen than iPhone 18 Pro Max. Apple iPhone Duo price started at ₹2,99,900 for a base 256GB model. The EMI run down to ₹48,817 a month sounds almost manageable until you realise that’s just for the base model if you want more space, the cost is going higher.

The top 2TB configuration crosses ₹4,49,900, either way, Apple’s first foldable is the most expensive iPhone the company has ever sold in India, and pre-orders open at 5:30 PM IST on October 16, with units shipping from October 23. 

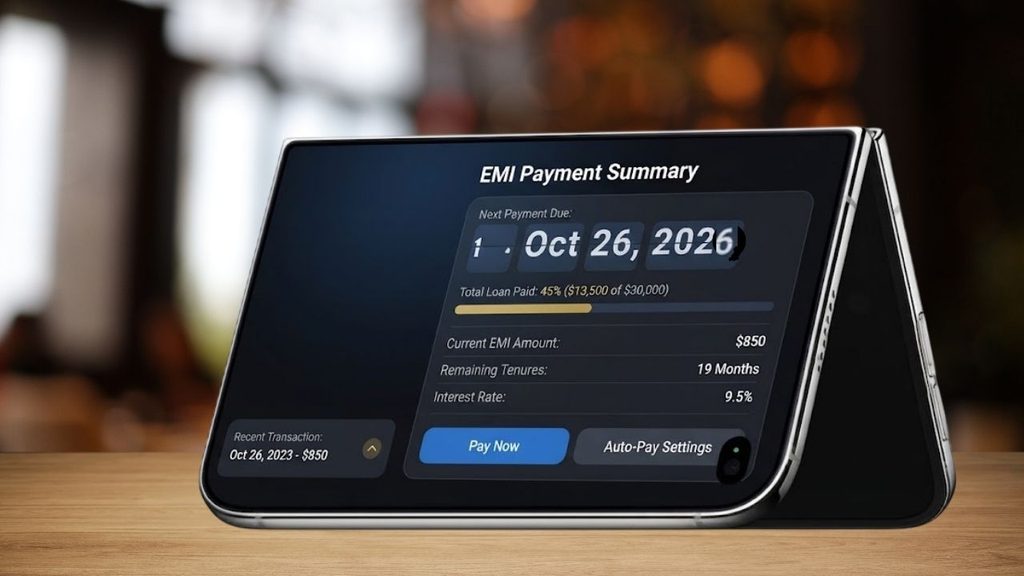
Between No Cost EMI, card cashback, and trade-in credit, there are real ways to bring the effective cost down, and just as many ways to misread the fine print and end up paying more than you expected. 

What the Apple iPhone Duo Costs in India

Apple has published pricing for all four storage tiers of the Duo:

  • 256GB — ₹2,99,900
  • 512GB — ₹3,24,900
  • 1TB — ₹3,74,900
  • 2TB — ₹4,49,900 

The iPhone 18 Pro starts at ₹1,64,900 and the iPhone 18 Pro Max at ₹1,79,900. The Duo’s entry price is roughly ₹1,35,000 above the Pro — not a small step up, and one reason Apple’s foldable debut in India has drawn as much attention for its billing as for its 7.6-inch inner display and A20 Pro chip. 


Unlike the standard iPhone 18 line, the iPhone Duo isn’t manufactured locally, so import duty and GST land on top of a device that already costs more to make. In the US, the same phone starts at $1,999 (roughly ₹1.7 lakh at the going exchange rate) — a reminder that Indian pricing on the Duo carries a heavier markup than usual, even by iPhone standards.

Apple iPhone Duo EMI: What Costs You Per Month

Apple’s No Cost EMI on the Duo runs over 3 or 6 months through most major card issuers — noticeably shorter than what Apple offers elsewhere. The US gets 24-month Apple Card Monthly Installments at roughly $83/month; the UK gets 30 months at 0% APR, working out to about £67/month. India’s 6-month cap is the shortest interest-free tenure Apple offers on the Duo anywhere, which is exactly why the monthly number here looks so heavy.

Published monthly EMI figure against each storage tier, and what six payments actually add up to versus the list price:

StorageMonthly EMI6-Month TotalSavings vs List Price
256GB₹48,817₹2,92,902₹6,998 under
512GB₹52,983₹3,17,898₹7,002 under
1TB₹61,317₹3,67,902₹6,998 under
2TB₹73,817₹4,42,902₹6,998 under

The Cashback Catch: ₹15,000 Sounds Bigger Than It Is

Apple India advertises “up to ₹15,000 instant cashback” across its entire store for customers using eligible American Express, Axis Bank, or ICICI Bank cards. That ₹15,000 is a store-wide ceiling — it’s not a number attached to the Duo, or to any single product. 

Run the EMI math above and the actual deduction baked into Apple’s Duo pricing lines up with ₹7,000, the same figure that’s been reported for the iPhone 18 Pro launch offer. Budget for that, not for ₹15,000.


A few conditions apply regardless of which figure you’re chasing:

  • Minimum transaction value of ₹10,001
  • Maximum two qualifying orders per rolling 90-day period
  • Not available to Business Store customers, and can’t be stacked with Education or Corporate Employee Purchase Plan pricing
  • Apple India explicitly reserves the right to revise or withdraw these terms without notice 

Apple hasn’t published a cashback figure specific to the Duo, a list of exactly which card variants qualify, an AppleCare+ price for the folding display, or what a screen repair would cost outside warranty. If any of those numbers matter to your decision, wait for the October pre-order.

Read More 👉 Your Dollar Income Isn’t Fixed: How INR Volatility Changes Freelancers Earning 

Turning Your Old iPhone Into a Down Payment

Apple’s exchange program advertises “save up to ₹62,000” when you trade in an eligible smartphone — available both online and in-store. Treat that ₹62,000 as a ceiling for a high-end device in excellent condition, not a number your specific phone will hit. 

A three-year-old iPhone with a cracked back glass is not pulling anywhere near that figure. If trade-in is central to your plan, get an online valuation for your exact device and condition before pre-order day, so you’re not recalculating your budget at checkout.


Third-party platforms like Cashify have historically run parallel exchange bonuses on top of card-linked EMI offers — ICICI’s Instant EMI programme has combined a 24-month deferred payment structure with additional exchange bonuses up to ₹6,000 on older iPhone models. 

The ICICI offer terms currently list iPhone 16 and 17-series devices, not the Duo. It’s reasonably expected that Duo-specific versions of these programmes will show up once pre-orders open.

Where You Can Buy Apple iPhone Duo

Apple India’s own store — with UPI, net banking, and EMI on eligible cards — is the confirmed channel from October 23. Authorized Apple resellers and large retail chains are expected to carry it too, based on how Apple has rolled out every recent flagship. 

Amazon and Flipkart listings are widely expected to go live around the launch window, though neither platform has published Duo-specific financing or exchange terms as of now. 

If a Bajaj Finserv No Cost EMI card or a Flipkart-specific bank offer matters to your plan, that’s one more thing to check on launch day rather than assume.

Apple iPhone Duo vs iPhone 18 Pro Max: Is the Jump Worth Financing?

The comparison that actually matters for your wallet isn’t Duo-to-Duo storage tiers — it’s Duo versus the iPhone 18 Pro Max, since that’s the next phone up in Apple’s current India lineup.

The iPhone 18 Pro Max starts at ₹1,79,900, less than two-thirds of the Duo’s ₹2,99,900 entry price, and runs on the same A20 Pro silicon. What you’re paying the extra ₹1,20,000 for is the fold itself: a 7.6-inch inner display Apple says is 50% larger than the Pro Max screen, a 5.4-inch cover display carrying over 90% of the Pro Max’s screen area when closed, and software in iOS 27 built specifically to adapt across open, half-folded, and closed states — split-screen Safari and Siri-driven multitasking that the Pro Max’s single flat screen can’t replicate.


That’s the real difference between these two smartphones. It’s a much harder case to make if your actual use is calls, camera, and social media, where the Pro Max’s flat 6.9-inch OLED does the job for a lot less money and without a hinge to eventually worry about. If the fold itself isn’t pulling you toward the Duo, the EMI math above becomes a much easier decision: skip it.

There’s also a first-generation-hardware question worth asking before you commit six months of EMI to it. The Duo’s hinge uses more than 100 parts and a magnet array to snap shut, sits under a titanium frame, and pairs Ceramic Shield 2 on the outer front with regular Ceramic Shield on the back — Apple’s most reinforced build on any iPhone. That’s a serious engineering effort, but it’s also Apple’s first attempt at a folding mechanism, with no multi-year track record the way the flat-screen Pro Max has. 

If you’ve never owned a folding phone and are financing this on EMI you can’t easily walk away from, it’s worth being honest about whether you’re the kind of owner who’ll baby a hinge for two years, or the kind who’ll drop it once every four months.

Read More 👉 Foreign Education Loan Currency Explained: How INR Depreciation Can Increase Your Loan Cost 

Apple’s eSIM-Only & 31 Hours Battery Power Doesn’t Affect On Duo Costs

The Apple iPhone Duo has no physical SIM tray, anywhere in the world. Every line runs on eSIM, with two eSIMs active at once and room to store eight or more profiles. Apple says this is part of why the phone manages up to 31 hours of video playback on the inner display and up to 44 hours on the outer one — the tray took up space that now goes to the dual-battery system instead.

That’s not a deal-breaker in India, where Jio, Airtel, and Vi have supported eSIM on postpaid and select prepaid plans for years. But it does mean two things worth planning around before you finance a ₹3-lakh phone. 


First, if you’re switching from an Android phone with a physical SIM, you can’t just pop the card across — you’ll need to get an eSIM profile issued by your carrier, which usually means a store visit or an app-based request, not an instant swap. 

Second, if your trade-in plan involves handing over your current iPhone the same day you activate the Duo, do the eSIM transfer before you box up the old phone, not after — Apple’s eSIM Quick Transfer works phone-to-phone, but only while both devices are in hand. Neither issue affects what the Duo costs, but both affect how smoothly your launch-day purchase goes, and a botched activation is a bad way to start a 6-month EMI commitment.

Read More 👉 SSC CPO SI CAPF Online Form 2026

Conclusion — Which Financing Route Fits You?

If you’ve got a recent flagship iPhone to trade in for Apple iPhone Duo, exchange + EMI is your cheapest real path — get the online trade-in estimate first, then layer 6-month No Cost EMI with an eligible Axis, ICICI, or Amex card on whatever balance is left.

If you don’t have a trade-in and want the lowest monthly hit, 6-month EMI beats 3-month by roughly half the monthly outflow for the same total cost — there’s no financial reason to choose the shorter tenure unless your card’s credit limit forces it.

If you’re on the fence about needing the fold at all, the iPhone 18 Pro Max buys you the same chip and most of the camera capability for ₹1,20,000 less, with a financing plan that’s easier on the wallet either way.

And if none of the current numbers work for your budget, waiting past October 16 costs you nothing — Apple, Amazon, and Flipkart have all historically added deeper festive-season offers on new iPhone within weeks of launch, and the Duo’s card-specific cashback terms are explicitly subject to change before then.

Leave a Comment

Your email address will not be published. Required fields are marked *

Bihar STET 2026 Online Form Out: Check Exam Syllabus and Pattern To Get Teacher Job

Bihar STET

Bihar STET 2026 Online Form Out on August 17 2026 and the last date to fill that form is September 15, 2026. Apply early to avoid last minute errors and server breaks, to score in Bihar State Eligibility Test (BSTET/STET 2026) examination, understand the exam syllabus and pattern.  

Download the official notification of Bihar STET 2026 to get all the details about eligibility, how to apply, and confirmed date for examination. While understanding the exam pattern which gets you selected.

Why Bihar STET 2026 Is Necessary For Teachers

Bihar STET — the Secondary Teacher Eligibility Test — isn’t a recruitment exam by itself. It’s a qualifying test conducted by BSEB that makes you eligible to apply for teaching posts in Bihar government-recognized schools, the same way BPSC TRE recruitment cycles have required in recent years. 

Clear it once, and BSEB now treats the certificate as valid for life rather than expiring after a few years, which is a meaningful change from the older TET/STET cycles where candidates had to keep re-qualifying. 

That’s the real reason so many people apply even when there’s no active teacher vacancy notification running at the same time — it’s a credential you bank for whichever recruitment drive comes next.

Bihar STET 2026 Important Dates

Save these dates into your calendar so don’t miss the day. Check updates on the official site every week for the exam date.

EventDate/Details
Notification released14/August/2026
Online application start17/August/2026
Original last date31/August/2026
Extended last date for application and fee payment15/September/2026
Official portalsThe dedicated application portal at stetregistration.cbrt.co.in
Exam DateThe exam date itself has not been officially announced. 

Eligibility Criteria for Paper 1 and Paper 2

The minimum age is 21 years as on August 1, 2026, confirmed consistently across the notification coverage. The upper limit is reported as 37 years for general candidates in some write-ups and as high as 42 for reserved and women candidates in others — since this figure hasn’t been consistent, check the age-relaxation table in the PDF notification itself before you rule yourself out.

Academic eligibility splits cleanly by paper:

  • Paper 1 (Secondary level, Classes 9–10): a Bachelor’s degree in the relevant subject with at least 50% marks, plus a B.Ed from an NCTE-recognized institution.
  • Paper 2 (Higher Secondary level, Classes 11–12): a Master’s degree in the relevant subject with at least 50% marks, plus a B.Ed.

Computer Science applicants are exempt from the mandatory B.Ed requirement if they meet the notification’s alternate qualification combinations, and the reduced qualifying marks, fee concessions, and age relaxations are only available to candidates with permanent Bihar domicile. 

Apply from outside the state, and you’re processed as a general-category male candidate regardless of your actual category — a detail that trips up a fair number of applicants from neighboring states every cycle.

Read More 👉 Your Dollar Income Isn’t Fixed: How INR Volatility Changes Freelancers Earning 

Bihar STET 2026 Online Form Fee Structure

The fee depends on category and on whether you’re applying for one paper or both:

  • General, BC, and EWS candidates: ₹960 for one paper, ₹1,440 for both
  • SC, ST, and PwD candidates: ₹760 for one paper, ₹1,140 for both

The fee is not refundable if you don’t pass the examination as this is the processing fee of your application.

Bihar STET 2026 Exam Pattern

Both papers follow the same structural pattern:

Exam ParticularsDetails
ModeComputer-Based Test (CBT)
Total questions150 multiple-choice questions
Total marks150 marks
Marks per question1 mark
Duration150 minutes (2 hours 30 minutes)
Negative markingNo negative marking

Of the 150 marks, 100 come from your chosen subject and the remaining 50 come from a section common to every candidate — Arts of Teaching and Other Competencies, covering General Knowledge, Reasoning Ability, Environmental Science, basic Mathematics, and Teaching Aptitude. 

Read More 👉 SSC CPO SI CAPF Online Form 2026

What To Study For Bihar STET Examination?

The subject-specific syllabus for Paper 1 broadly mirrors the graduate-level curriculum taught across Bihar’s universities. For Paper 2, it steps up to the graduate honours-level syllabus used for that subject in state universities — meaningfully deeper than Paper 1, which is worth remembering if you’re eyeing both papers back to back.

Your subject accounts for two-thirds of the total marks, so subject depth should be where most of your study hours go. But don’t write off the 50-mark common section as an afterthought — because most candidates do treat it as an afterthought, a candidate who actually revises General Knowledge, Reasoning, Environmental Science, and Teaching Aptitude systematically picks up an edge that’s disproportionate to how little competition they face there.

How to Apply for Bihar STET 2026

  1. Go to the official application portal of Bihar STET.
  2. Start a new registration and fill in basic details — name, mobile number, email.
  3. Verify your mobile number via OTP; a login ID and password get generated and sent to you.
  4. Log in and complete your personal and educational details in the application form.
  5. Upload a recent photograph, signature, and the required certificates.
  6. Pay the application fee online through the available payment modes.
  7. Submit the form and save or print the confirmation copy.

Several candidates in this cycle have reported that correction options after final submission are limited. Double-check your subject choice, category, and uploaded documents before you hit submit rather than assuming you can fix it afterward.

Selection Process and Certificate Validity

There’s no interview or separate merit round for STET itself — selection is based purely on your normalized CBT score against the qualifying threshold for your category. 

General category candidates need 50% to qualify; SC, ST, PwD, and women candidates need 40%. Once you clear that bar, BSEB issues a certificate that, under current policy, doesn’t expire — meaning you carry that eligibility forward into whichever Bihar teacher recruitment drive (including future BPSC TRE rounds) comes next, rather than needing to re-clear STET every cycle.

Read More 👉 Apple iPhone Duo Changes the Cost Effectively With These Methods

Conclusion

Bihar STET 2026 Online Form Out in August and now the deadline is coming, so you still have time to apply for the teacher eligibility test. Knowing the exam syllabus and pattern will help you get a high score and open many opportunities.

The one thing worth deciding today is whether you’re eligible for both papers — because qualifying for STET is separate from being recruited into a specific post, applying for both when you meet both qualification bars simply widens which recruitment drives you can walk into later without paying for and sitting through a second STET cycle. 

And since the exam date isn’t out yet, don’t waste energy hunting for a leaked schedule — put that time into the subject syllabus instead, since that’s the one variable in this entire process that’s already fully in your control.

Leave a Comment

Your email address will not be published. Required fields are marked *

Scroll to Top