UP SuperTET Vacancy Notification 2026: Check Out Details, Dates, & Eligibility

SuperTET

If you’ve been searching continuously on Google for “UP SuperTET 2026 Notification Out, you are not alone because many future teachers are googling it but don’t panic. You are not late, because the official notification has not been released yet. The vacancy numbers are a guess if you see anywhere.  

When Will The UP SuperTET Notification Get Released?

UPBEB is going to publish the SuperTET 2026 notification soon and it carries the exam date, required documents, eligibility, and exam pattern information for the candidates. The best way of starting the process is to read that notification carefully once it is released before going to fill the form for UP SuperTET 2026. 

It’ll land after the UPTET result is out, so most of the candidates get eligible for the SuperTET so there should be a larger number of vacancies. But that’s an educated guess about timing, not a commitment from the The Uttar Pradesh Basic Education Board. 

Where You Can Find The SuperTET Updates? 

Skip the YouTube shorts and forward-heavy WhatsApp groups. The two sources worth bookmarking are:

Vacancy For UP SuperTET Exam 2026

From the past cycle and current teacher-shortage data, it is precisely reasonable that UP SuperTET 2026 Vacancy lies around 69,000, 85,000. But these numbers aren’t shared by the officials so treat them as a closer guess. 

The 2019 SuperTET drive filled around 69,000 posts so it became the usual provisional around number. Until UPBEB publishes district-wise and category-wise vacancy breakdowns in the actual notification.

SuperTET Salary and Eligibility 

Vacancy and dates can change year by year but 80% of the stuff is the same each year. SuperTET eligibility, salary, exam pattern are not going to change, even if it does, only slight change can happen. 

ParameterDetails
PostAssistant Teacher – Primary (Classes 1–5) and Upper Primary (Classes 6–8)
Pay Scale₹35,400 – ₹1,12,400 (Level 6, 7th Pay Commission)
EligibilityValid CTET or UPTET:- Paper I for Primary (Classes 1–5)- Paper II for Upper Primary (Classes 6–8)Plus relevant qualifying degree and/or B.Ed as per recruitment rules
Exam PatternObjective-type test, 150 marks, covering:- Language proficiency- Pedagogy (teaching methodology)- General Knowledge- Subject-specific content knowledge

Qualifying Numbers are easily let you pass by acquiring 40% (60/150) if you are General category candidate and 33% (49.5/150) for the candidates who belong to SC/ST/OBC-NCL/PwD but they are not a scoring score to win this battle among thousands candidates. 

Actual merit cutoff: if you actually want to get selected then score from 90 to 130+ out of 150 to hold out your position. These are the actual merit numbers, it also depends up on your category and how many seats are open. 

That gap between “qualifying score” and “actual selection score” trips people up every cycle. SuperTET isn’t a pass/fail eligibility test — it’s a straight competitive recruitment exam. Scoring the minimum gets you nowhere near a job.

UPSSSC PET Exam Date 2026 Out

How To Prepare Yourself For The Exam

  1. Don’t wait to start preparing. The syllabus and pattern are already finalized by UP authorities, which is usually a sign the recruitment machinery is moving even if the notification isn’t out yet.
  2. Keep your CTET/UPTET certificate and documents ready. Once the form opens, the window is typically short — 20 to 30 days and document scrambling under deadline pressure is a self-inflicted wound.
  3. Ignore vacancy-number debates on social media. They change nothing about your prep and mostly exist to farm engagement.
  4. Set a check-in habit, not a refresh habit. Checking the official website once a day is enough. Constant refreshing just adds stress without adding information.

Conclusion 

Start focusing on the syllabus, pattern, expected post structure before UP SuperTET 2026 Notification Out because it’s released, you won’t get enough time to prepare after that. There’s no confirmed vacancy count but there’s a guessing number, the competition will be higher. 

Prepare like the exam is close, because structurally it looks like it is, but don’t let unverified numbers shape your expectations or your plans.

Always cross-check every information on the official website of UP Super TET 2026 Notification Out before acting on any detail published by educational sites.

Leave a Comment

Your email address will not be published. Required fields are marked *

Best App To Get Instant Loan Without Salary Slip 

Best App To Get Instant Loan Without Salary Slip

Your landlord isn’t waiting, the hospital isn’t waiting, and your bank’s personal loan officer just told you to come back “once you have three months of payslips.” That forces you to google for the Best App To Get Instant Loan Without Salary Slip because you need ₹20,000 urgently. Because there is no payslip coming from a freelancer, or small start ups owner.

This is the exact gap that a new generation of lending apps was built to close. Instead of a salary slip, they read your bank statements, your PAN and Aadhaar history, your UPI transaction pattern, and sometimes your GST filings, and turn that into a credit decision in minutes. 

However, “no salary slip” doesn’t mean “no scrutiny” and it definitely doesn’t mean every app claiming this is safe to use. Below are the Best App To Get Instant Loan Without Salary Slip, let’s see what they actually cost, and how to tell a legitimate lender from a data-harvesting clone before you hand over your Aadhaar.

Why Salary Slips Stopped Being the Only Option

Banks built their lending rules around one kind of borrower: someone with a fixed monthly salary landing on the same date, from the same employer, verifiable on a letterhead. That description fits a shrinking share of India’s workforce. Freelancers, gig-platform workers, small traders, and contract staff earn real, trackable income — it just doesn’t arrive in payslip form.

Digital lenders solved this by switching the input. Instead of a payslip, they pull 3–12 months of bank statements to see how much money moves through your account and how consistently. Self-employed applicants can usually substitute ITR filings, GST returns, or business account statements. 

Some apps go further and factor in your digital footprint — how long you’ve held your phone number, your UPI activity, even your app usage patterns to build a risk score. None of this is charity; it’s just a different, faster underwriting model, and it’s why approval on these apps can take minutes instead of the two-week wait typical of a bank.

Skipping The Salary Slip Doesn’t Mean The Requirement of Documents Ends

Skipping the salary slip doesn’t mean skipping documentation — it just shifts what counts as proof. Across the apps below, the standard ask is a PAN card, Aadhaar for e-KYC, and 3–6 months of bank statements showing regular inflows. 

Self-employed applicants typically add one of: ITR filings for the last one or two years, GST returns if registered, or a business current-account statement. A few apps, like Fibe and mPokket, lean more heavily on alternative signals — how long you’ve had your phone number, your UPI transaction frequency, even basic device data — specifically for applicants who have no ITR or GST paperwork to show at all. 

None of this is optional paperwork replaced by “trust us” — every legitimate lender still needs some way to estimate whether you can repay, it’s just reading your cash flow instead of your employer’s letterhead.

Best Instant Loan Apps Without a Salary Slip Are Listed

1. KreditBee — Best for Small, Fast Loans With No CIBIL History

KreditBee lends through Krazybee Services, an RBI-registered NBFC, and is built for speed on smaller ticket sizes. Loan amounts run from about ₹5,000 up to ₹10 lakh, with tenures between 3 and 60 months. 

Interest rates officially start at 12% p.a., but that floor is reserved for the strongest profiles — most first-time or thin-file borrowers land closer to 24–29.95% p.a., and self-employed applicants specifically are often quoted in the 16–29.95% range. 

Processing fees can run up to roughly 4–5% of the loan amount, deducted upfront from disbursal. The minimum income requirement is just ₹10,000 a month, and a CIBIL score isn’t mandatory. 

Best for: someone who needs ₹10,000–₹50,000 fast and doesn’t have a credit history yet — not for large-ticket borrowing, since the cost climbs fast at that end.

2. Navi — Best for Lower Rates and Larger Loan Amounts

Navi, backed by Navi Finserv, is an app to check if your credit score is solid and you need more money for longer. Loan amounts stretch from around ₹10,000 to ₹20 lakh (some listings show up to ₹10 lakh depending on the product), with tenures up to 84 months. 

Rates start near 9.9–9.99% p.a. for borrowers with a CIBIL score of 700+, but can rise to 29–45% p.a. for weaker profiles — a wider spread than most competitors, so the advertised low rate isn’t guaranteed. 

Processing fees range from 0% to about 4% plus GST. Both salaried and self-employed applicants are eligible with a minimum score of roughly 650. 

Best for: self-employed borrowers with a decent credit file who want a bigger loan without a bank’s paperwork.

3. Fibe (formerly EarlySalary) — Best for Speed

Fibe is an RBI-registered NBFC-P2P platform (license N-13.02139) built around a two-minute approval promise, using an AI model that scans over 100 data points instead of a payslip. Loan amounts go up to ₹5 lakh, rates start at 12% p.a., and it’s known for letting borrowers with no CIBIL score qualify by leaning on digital and social-footprint signals instead. It’s particularly active in Tier-2 and Tier-3 cities where bank branches and traditional documentation checks are less accessible. 

Best for: first-time borrowers who need money today and can accept a higher rate in exchange for near-instant disbursal.

4. PaySense — Best for Consistent Self-Employed Income

PaySense, run on PayU Finance India’s lending infrastructure, uses risk-based pricing rather than one flat rate, so two applicants for the same amount can get different offers. Published eligibility asks for a minimum monthly income of ₹18,000 for salaried applicants and ₹20,000 for self-employed ones, with interest rates typically quoted between 14% and 36% p.a. depending on profile. It accepts a low or even zero CIBIL score, which makes it accessible, but that flexibility shows up in the rate you’re offered. 

PaySense is the Best App To Get Instant Loan Without Salary Slip for self-employed borrowers with steady, provable cash flow who don’t yet have a strong credit file.

5. MoneyView — Best for Tier-2/Tier-3 Self-Employed Borrowers

MoneyView is frequently the first recommendation for salaried applicants outside metro cities and for self-employed or gig workers who want minimal paperwork. It’s positioned between the small-ticket apps and the larger NBFC lenders, with loan amounts up to around ₹10 lakh and rates generally in the low-to-mid double digits for stronger profiles, rising for thinner files — broadly comparable to KreditBee’s range, though it’s often described as steadier on collection practices in user reviews. 

Best for: borrowers outside major metros who want a mid-sized loan without a Tier-1-city credit profile.

6. mPokket — Best for Students and Thin-File Gig Workers

mPokket is built specifically for people the traditional system ignores entirely — students and gig workers with little or no credit history. Loan sizes are smaller than the others on this list, aimed at short-term, small-amount needs like covering a bill or a temporary cash gap rather than a big-ticket expense. It shouldn’t be treated as a recurring source of funds — the sizes and terms make it best suited to occasional, short-duration borrowing. 

Best for: students or new-to-credit gig workers who need a small amount and have nowhere else to turn.

Read More 👉 How to Start a Mineral Water Business: Complete Guide

How To Get an Instant Personal Loan Through Paytm, PhonePe, GPay, and Bhim

The same apps you use to split a dinner bill or pay your electricity bill can also get you a loan — often within minutes. Here’s how each one actually works:

Paytm

Open the Paytm app, head to the “Loans & Credit Cards” section, and tap “Personal Loan.” Paytm lets you apply anytime for an instant loan online in about two minutes, with a fully digital process and loan amounts ranging from ₹5,000 to ₹15 lakh, flexible tenure, and the option to foreclose anytime. 

Paytm doesn’t lend the money itself — it partners with RBI-regulated NBFCs and banks who actually underwrite and disburse the loan. You’ll go through PAN and Aadhaar-based KYC either way.

PhonePe

Same idea, different app. PhonePe doesn’t hand out loans directly — it has partnered with various banks and NBFCs to offer instant loans, so you can apply without ever leaving the app.  Loan amounts go up to ₹5 lakh, repayable over tenures of up to 60 months, at rates starting around 13% per annum, with the approved amount transferred straight to your bank account.  Most lenders here look for a stable income and a credit score around 650 or higher.

Google Pay

Google Pay follows the same partner-lending model as Paytm and PhonePe — it doesn’t lend directly but connects you to its NBFC and bank partners for a pre-approved or application-based personal loan inside the app, with KYC handled digitally via Aadhaar and PAN.

BHIM

This one surprises people, since BHIM is best known as NPCI’s bare-bones UPI app. But it’s expanded: BHIM now lets you explore a personal loan without leaving the app, again through its network of lending partners rather than lending in-house.

How to Check an App Isn’t a Scam Before You Apply

RBI does not license individual apps — it regulates the bank or NBFC behind them. That distinction is the entire safety check:

  • Find the named NBFC or bank. A legitimate app discloses its lending partner clearly in the app, on the Play Store listing, or in the loan agreement. If you can’t find a specific company name, stop.
  • Verify that name on rbi.org.in or the RBI’s Digital Lending Apps directory before you submit any documents.
  • Never pay upfront. Processing fees, “insurance,” or “security deposits” requested before disbursal are the single most common fraud pattern. Legitimate lenders deduct fees from the loan amount after approval, not before.
  • Check what permissions it wants. A real KYC process needs your camera for a selfie and basic identity/banking access — not your full contact list, photo gallery, SMS logs, or call history. Apps that demand those are usually building leverage for harassment-based recovery later, not assessing creditworthiness.
  • Look for a Key Fact Statement (KFS). RBI’s digital lending rules require one before disbursal, listing the all-in APR, not just a headline interest rate. A “1% per month” rate can look harmless until the APR reveals fees stacked on top.
  • Confirm a named grievance officer with a phone number and email — not just a generic contact form.

If two or more of these are missing, treat the app as a red flag regardless of its Play Store rating, which is not proof of regulatory legitimacy. Because the best app to get instant loan doesn’t mean every app is trustworthy.

Advertising Rate Is Always Different From Actual Amount You Receive in Your Account

Headline interest rates on these apps are quoted per annum, but the real cost shows up in the APR, once processing fees and GST on those fees are added in. A concrete example: on a KreditBee loan disbursed at roughly ₹1 lakh, one published breakdown shows a ₹4,000 processing fee (4%), ₹720 GST on that fee, and ₹10 in documentation charges — pushing the effective APR to 29.66%, even though the headline rate for that borrower’s tier read lower. 

The amount that actually lands in the bank account was around ₹95,270, not the full ₹1 lakh. This is exactly what the Key Fact Statement is meant to expose, and it’s why comparing apps on their advertised “starting from” rate alone is close to useless — always ask for the APR and the net disbursal amount before accepting an offer, not just the interest rate.

Read More 👉 How to Apply for an Education Loan Online

Which App Should You Consider For Instant Personal Loan?

  • If you’re a gig worker or freelancer with no credit history and need a small amount fast, start with KreditBee or Fibe. 
  • If you’re self-employed with steady bank statements and want a lower rate on a bigger amount, check Navi or MoneyView first and let your CIBIL score decide between them. 
  • If you’re a student or new to credit entirely, mPokket is built for exactly that gap, but treat it as a short-term bridge, not a repeat solution. 

Conclusion

Whichever  Best App To Get Instant Loan Without Salary Slip you land on, run it through the RBI-verification checklist above before you type in your PAN — that two-minute check is what separates a fair loan from a very expensive mistake.

The absence of a salary slip requirement is a documentation shortcut, not a signal that the loan is free of risk. A ₹20,000 loan at 28% p.a. with a 4% upfront fee still needs to be repaid on schedule, and missed EMIs on these apps report to CIBIL just like a bank loan would. 

Borrow the amount you need for the problem in front of you, not the maximum the app is willing to approve — the higher your sanctioned limit looks, the more tempting it is to take more than the situation actually calls for.

Note: Rates, loan limits, and fees above reflect published figures as of mid-2026 and change frequently based on lender policy and individual credit profile — confirm current terms in-app before applying.
Leave a Comment

Your email address will not be published. Required fields are marked *

Bihar STET 2026 Online Form Out: Check Exam Syllabus and Pattern To Get Teacher Job

Bihar STET

Bihar STET 2026 Online Form Out on August 17 2026 and the last date to fill that form is September 15, 2026. Apply early to avoid last minute errors and server breaks, to score in Bihar State Eligibility Test (BSTET/STET 2026) examination, understand the exam syllabus and pattern.  

Download the official notification of Bihar STET 2026 to get all the details about eligibility, how to apply, and confirmed date for examination. While understanding the exam pattern which gets you selected.

Why Bihar STET 2026 Is Necessary For Teachers

Bihar STET — the Secondary Teacher Eligibility Test — isn’t a recruitment exam by itself. It’s a qualifying test conducted by BSEB that makes you eligible to apply for teaching posts in Bihar government-recognized schools, the same way BPSC TRE recruitment cycles have required in recent years. 

Clear it once, and BSEB now treats the certificate as valid for life rather than expiring after a few years, which is a meaningful change from the older TET/STET cycles where candidates had to keep re-qualifying. 

That’s the real reason so many people apply even when there’s no active teacher vacancy notification running at the same time — it’s a credential you bank for whichever recruitment drive comes next.

Bihar STET 2026 Important Dates

Save these dates into your calendar so don’t miss the day. Check updates on the official site every week for the exam date.

EventDate/Details
Notification released14/August/2026
Online application start17/August/2026
Original last date31/August/2026
Extended last date for application and fee payment15/September/2026
Official portalsThe dedicated application portal at stetregistration.cbrt.co.in
Exam DateThe exam date itself has not been officially announced. 

Eligibility Criteria for Paper 1 and Paper 2

The minimum age is 21 years as on August 1, 2026, confirmed consistently across the notification coverage. The upper limit is reported as 37 years for general candidates in some write-ups and as high as 42 for reserved and women candidates in others — since this figure hasn’t been consistent, check the age-relaxation table in the PDF notification itself before you rule yourself out.

Academic eligibility splits cleanly by paper:

  • Paper 1 (Secondary level, Classes 9–10): a Bachelor’s degree in the relevant subject with at least 50% marks, plus a B.Ed from an NCTE-recognized institution.
  • Paper 2 (Higher Secondary level, Classes 11–12): a Master’s degree in the relevant subject with at least 50% marks, plus a B.Ed.

Computer Science applicants are exempt from the mandatory B.Ed requirement if they meet the notification’s alternate qualification combinations, and the reduced qualifying marks, fee concessions, and age relaxations are only available to candidates with permanent Bihar domicile. 

Apply from outside the state, and you’re processed as a general-category male candidate regardless of your actual category — a detail that trips up a fair number of applicants from neighboring states every cycle.

Read More 👉 Your Dollar Income Isn’t Fixed: How INR Volatility Changes Freelancers Earning 

Bihar STET 2026 Online Form Fee Structure

The fee depends on category and on whether you’re applying for one paper or both:

  • General, BC, and EWS candidates: ₹960 for one paper, ₹1,440 for both
  • SC, ST, and PwD candidates: ₹760 for one paper, ₹1,140 for both

The fee is not refundable if you don’t pass the examination as this is the processing fee of your application.

Bihar STET 2026 Exam Pattern

Both papers follow the same structural pattern:

Exam ParticularsDetails
ModeComputer-Based Test (CBT)
Total questions150 multiple-choice questions
Total marks150 marks
Marks per question1 mark
Duration150 minutes (2 hours 30 minutes)
Negative markingNo negative marking

Of the 150 marks, 100 come from your chosen subject and the remaining 50 come from a section common to every candidate — Arts of Teaching and Other Competencies, covering General Knowledge, Reasoning Ability, Environmental Science, basic Mathematics, and Teaching Aptitude. 

Read More 👉 SSC CPO SI CAPF Online Form 2026

What To Study For Bihar STET Examination?

The subject-specific syllabus for Paper 1 broadly mirrors the graduate-level curriculum taught across Bihar’s universities. For Paper 2, it steps up to the graduate honours-level syllabus used for that subject in state universities — meaningfully deeper than Paper 1, which is worth remembering if you’re eyeing both papers back to back.

Your subject accounts for two-thirds of the total marks, so subject depth should be where most of your study hours go. But don’t write off the 50-mark common section as an afterthought — because most candidates do treat it as an afterthought, a candidate who actually revises General Knowledge, Reasoning, Environmental Science, and Teaching Aptitude systematically picks up an edge that’s disproportionate to how little competition they face there.

How to Apply for Bihar STET 2026

  1. Go to the official application portal of Bihar STET.
  2. Start a new registration and fill in basic details — name, mobile number, email.
  3. Verify your mobile number via OTP; a login ID and password get generated and sent to you.
  4. Log in and complete your personal and educational details in the application form.
  5. Upload a recent photograph, signature, and the required certificates.
  6. Pay the application fee online through the available payment modes.
  7. Submit the form and save or print the confirmation copy.

Several candidates in this cycle have reported that correction options after final submission are limited. Double-check your subject choice, category, and uploaded documents before you hit submit rather than assuming you can fix it afterward.

Selection Process and Certificate Validity

There’s no interview or separate merit round for STET itself — selection is based purely on your normalized CBT score against the qualifying threshold for your category. 

General category candidates need 50% to qualify; SC, ST, PwD, and women candidates need 40%. Once you clear that bar, BSEB issues a certificate that, under current policy, doesn’t expire — meaning you carry that eligibility forward into whichever Bihar teacher recruitment drive (including future BPSC TRE rounds) comes next, rather than needing to re-clear STET every cycle.

Read More 👉 Apple iPhone Duo Changes the Cost Effectively With These Methods

Conclusion

Bihar STET 2026 Online Form Out in August and now the deadline is coming, so you still have time to apply for the teacher eligibility test. Knowing the exam syllabus and pattern will help you get a high score and open many opportunities.

The one thing worth deciding today is whether you’re eligible for both papers — because qualifying for STET is separate from being recruited into a specific post, applying for both when you meet both qualification bars simply widens which recruitment drives you can walk into later without paying for and sitting through a second STET cycle. 

And since the exam date isn’t out yet, don’t waste energy hunting for a leaked schedule — put that time into the subject syllabus instead, since that’s the one variable in this entire process that’s already fully in your control.

Leave a Comment

Your email address will not be published. Required fields are marked *

iPhone 18 Pro on EMI: A Complete Buying Guide

iPhone 18 Pro

Apple hasn’t confirmed a single detail about the iPhone 18 Pro yet, but that hasn’t stopped Indian buyers from searching iPhone 18 Pro EMI options months before launch — and for good reason. With expected pricing starting north of ₹1,34,000, paying the full amount upfront isn’t realistic for most people. 

The real question isn’t whether you should use EMI. It’s which EMI actually saves you money, and which one just makes an expensive phone feel cheaper than it is for a few months.

When Is the iPhone 18 Pro Launching in India?

Every recent report points to September 2026, alongside the iPhone 18 Pro Max and for the first time — Apple’s foldable iPhone. What’s changed this year is the rest of the lineup. Bloomberg’s Mark Gurman reported that Apple is splitting its release schedule for the 18 series: only the Pro, Pro Max, and the foldable arrive this September, while the standard iPhone 18 and a new iPhone 18e get pushed to spring 2027. If that holds, this is the first year in a while where the “regular” iPhone won’t launch alongside the Pro models.

Going by Apple’s usual pattern (the iPhone 17 event was held on September 9, 2025, with sales opening ten days later), a keynote in the first two weeks of September 2026 is the safest bet, with stock hitting stores roughly a week to ten days after that. Some trackers are floating September 8–9 specifically; others leave more room, up to September 10. Take the exact date as a placeholder until Apple sends out invites, which usually happens about three weeks ahead of the event.

Expected iPhone 18 Pro Price in India

Price leaks are all over the place right now, which is normal this far out. Here’s the range being reported across sources as of this writing:

VariantExpected India price
iPhone 18 Pro, 256GB₹1,34,900 – ₹1,44,900
iPhone 18 Pro, 512GB₹1,52,500 – ₹1,69,990
iPhone 18 Pro Max, 256GB (starting)₹1,49,900 – ₹1,60,000

A few sources argue Apple will hold pricing close to the iPhone 17 Pro’s ₹1,34,900 launch price, citing “aggressive supplier negotiations” to protect India pricing. Others expect a hike tied to the RAM bump (12GB is the rumored figure) and camera hardware upgrades — the iPhone 18 Pro is rumored to carry a triple 48MP setup with a periscope telephoto lens and a variable-aperture main camera, on a 2nm A20 Pro chip. Rumors are also split on whether Face ID moves under the display this generation or stays as-is; one supply chain report specifically says it won’t happen this year due to production delays.

Budget for the ₹1,34,900–1,44,900 band on the base 256GB Pro, and don’t be surprised if the number lands closer to the top of that range once Apple accounts for import duty and GST on the final config.

What’s the Actual Difference In No-Cost EMI vs Standard EMI? 

This is where most buyers get it wrong. “No-cost EMI” doesn’t mean the bank is doing you a favour — it means the retailer or Apple absorbs the interest that would normally apply, so you pay roughly the sticker price split into installments instead of sticker price plus interest. Depending on the bank, this shows up in one of two ways: the interest is stripped out at checkout, or you’re charged interest upfront and it comes back to you as cashback within about 90 days (this is how ICICI’s scheme works on longer tenures). Either way, you’ll still pay a processing fee, GST on that fee, and — if you close the loan early — a foreclosure charge, typically around 3% of the outstanding principal plus the next month’s interest.

Standard EMI is the version without the safety net: real interest, usually in the 12–16% per annum range on credit card conversions, on top of the base price.

The gap adds up fast. On a ₹1,34,900 iPhone 18 Pro, a 24-month standard EMI at 14% p.a. works out to roughly ₹6,477 a month — about ₹20,500 more than the phone’s actual price by the time you’re done paying. The same tenure under a genuine no-cost scheme costs ₹5,621 a month, with no premium at all. That ₹20,500 difference is the entire reason to check which scheme you’re actually being offered before you tap “confirm” at checkout.

Read More👉 Best Laptops for Coding and Programming: Top Picks for Every Budget

Where You’ll Be Able to Buy iPhone 18 Pro on EMI

You’ll have more than one route in, and it’s worth comparing before you commit to any single one. Apple’s own online store runs its no-cost EMI tie-ups directly with Bajaj Finance, HDB Financial Services, ICICI Bank, IDFC First Bank, and TVS Credit — the current scheme window on Apple’s authorised platforms runs through late September 2026, which should carry into the 18 Pro’s launch. Apple Authorised Resellers such as iStore, Unicorn, Croma, Reliance Digital, and Vijay Sales layer their own instant cashback offers on top for Axis Bank, ICICI Bank, and SBI Card users, usually on 6-month no-cost tenures with low-cost EMI kicking in beyond that.

Amazon and Flipkart are the other major channels, particularly around sale events — Amazon’s Great Freedom Sale and Flipkart’s Freedom Sale both ran in early August 2026, and both platforms typically repeat similar EMI-plus-bank-discount stacking for major flagship launches. Flipkart also supports the Bajaj Finserv Instant EMI Card for buyers without a traditional credit card. Debit card EMI is more limited — HDFC, Axis, and ICICI extend it to pre-approved debit cardholders, but the pool of eligible customers is smaller and interest rates run similar to credit card EMI.

Whichever channel you pick, check the fine print on tenure caps — 6-month no-cost EMI is nearly universal, but 12- and 24-month no-cost schemes are usually restricted to specific banks and specific card tiers.

How Much Will Your Monthly EMI Be?

Based on the expected price bands above, here’s what a genuine no-cost EMI would look like at common tenures:

Tenure256GB Pro (~₹1,34,900)512GB Pro (~₹1,52,500)Pro Max 256GB (~₹1,54,900)
3 months₹44,967₹50,833₹51,633
6 months₹22,483₹25,417₹25,817
9 months₹14,989₹16,944₹17,211
12 months₹11,242₹12,708₹12,908
24 months₹5,621₹6,354₹6,454

These are straight divisions of the expected MRP with no interest added — that’s what “no-cost” is supposed to mean. If a bank quotes you anything higher than these figures for the same price and tenure, ask specifically whether interest is being charged, because it likely is.

Exchange Offer + EMI Combo — Lowering Your Effective EMI

Trading in your current phone reduces the amount you actually finance, which lowers every EMI figure above. As an example: on a ₹1,44,900 iPhone 18 Pro, a mid-range trade-in like a working iPhone 13 128GB might fetch around ₹15,000 in exchange value plus a ₹6,000 exchange bonus — a combined ₹21,000 off, bringing the amount you’d actually put on EMI down to ₹1,23,900. Financed over 12 months no-cost, that’s roughly ₹10,325 a month instead of ₹12,075.

The catch is that the trade-in values swing enormously based on the model, storage, and physical condition of your old device, and different assessors don’t agree with each other. Apple’s own trade-in estimate, a reseller’s in-store quote, and a third-party service like Cashify can differ by several thousand rupees for the same phone. 

Get quotes from at least two sources before you finalise, and remember that exchange bonuses on top of the base trade-in value are usually time-limited promotions, not permanent policy — they’re the kind of thing that disappears the week after a big sale ends.

Step-by-Step Guide To Buying iPhone 18 Pro on EMI

  1. Shortlist your retailer first, not the phone colour. Compare what Apple’s own store, your nearest authorised reseller, Amazon, and Flipkart are each offering on EMI tenure and bank tie-ups — the same phone can carry different effective costs depending on where you buy it.
  2. Check your card’s pre-approved EMI limit. Most banks let you check this via SMS or net banking before you shop, so you’re not caught out at checkout with a card that can’t support the tenure you want.
  3. Get an exchange quote in advance if you’re trading in. Apple’s trade-in tool and your reseller’s in-store estimate both take a few minutes and give you a real number to plan around.
  4. Select the EMI option at checkout that matches your card and target tenure. No-cost options are usually listed separately from standard EMI — don’t assume the first EMI option shown is the no-cost one.
  5. Confirm the breakdown before you pay. Look for a line item showing interest and processing fee separately. If the total EMI amount adds up to more than the phone’s price divided by the number of months, you’re paying interest somewhere.
  6. Read the foreclosure terms. If there’s a chance you’ll want to pay off the balance early, know the foreclosure charge upfront rather than finding out later.
  7. Save your EMI schedule and transaction confirmation. You’ll need these if a cashback-style no-cost EMI scheme (like ICICI’s) hasn’t been credited on schedule.

Read More👉 iPhone 18 Pro Launching Next Month: 12 New Features Worth Knowing About

Conclusion 

The iPhone 18 Pro’s price and launch date will stay rumors until Apple actually sends out event invites, and it’s worth waiting for that confirmation before you lock in a purchase decision — leaked pricing has moved by thousands of rupees between reports even in the past few weeks. 

But the EMI math you plan around today will hold regardless of the exact final price: the difference between a genuine no-cost scheme and a standard one is real money, often ₹15,000–20,000 over a two-year tenure, and it has nothing to do with which bank has the nicest app. 

Compare the tenure and the bank before you compare the storage variant, get your exchange quote sorted early if you’re trading in, and read the checkout screen closely enough to know exactly what you’re signing up for, not just what the monthly number says.

Leave a Comment

Your email address will not be published. Required fields are marked *

Voice-to-Notes Tools for Students: Study Faster Without Typing

Voice-to-Notes Tools

Voice-to-Notes Tools are really helpful from turning large study lectures into simple notes in just few minutes. Writing everything down is an old fashion technique that takes a lot of time for a few pages notes but everything is going easy with fast pacing technologies. Whether it’s hours of session or long research sheets, enabling speech to text is the smarter way to take notes. 

You’re forty minutes into a lecture, the professor has moved through three concepts, and your notes still say “photosynthesis — light reaction —” because your hand gave up before your brain did. Speaking runs at roughly 150-160 words a minute while typing tops out around 40 for most people. 

That gap is the entire case for Voice-to-Notes Tools , and for Indian students juggling coursework in English, Hindi, or a regional language, the tool you pick matters more than the concept itself — because most of the tools were built for American office meetings, not for Indian classrooms. 

Best Voice-to-Notes Tools For Indian Students 

There are plenty of tools that can turn your voice into text but then you find an error — spelling, whole different word (except, accept), not able to turn your regional language — that’s because it doesn’t understand. Some AI integrated voice tools that turn your every word into text without major errors is here:

Gboard Voice Typing — free, and it’s already on your phone

Before downloading anything, check what you have. Google’s Gboard keyboard has an in-built voice typing feature which you can use by clicking on the mic icon. If the icon is invisible then enable it from the setting so Voice-to-Notes can be easy and quick without downloading any new app.


It works in Hindi plus eight regional languages — Bangla, Gujarati, Kannada, Malayalam, Marathi, Tamil, Telugu, and Urdu — Indian students can use this keyboard in any app that takes input in the same language, not just Google’s own apps. 

For a student jotting quick revision notes in Hindi between classes, this is the lowest-friction option because there is no signup, no subscription, no separate app to remember to open.

Google Recorder — real-time transcription, best if you have a Pixel

Google Recorder transcribes live as you speak and runs the processing on-device, which matters if your hostel Wi-Fi is unreliable. The catch: it’s tied to Pixel phones for its full real-time transcription experience, so if you’re on a different Android device or iPhone, this one’s off the table.

Otter.ai — good for English lectures, but it skips Hindi entirely

Otter is the name that comes up first in most “best Voice-to-Notes Tools” lists, and for English-medium lecture capture it’s genuinely capable — live transcription, speaker labels, searchable transcripts. 

The free tier gives you 300 minutes of transcription a month, capped at 30 minutes per recording, which covers maybe eight or nine standard lecture sessions before you hit the wall. The Pro plan runs $16.99/month billed monthly, or roughly $8.33/month if you pay annually (about $99.99/year). 

But for Indian students: Otter’s transcription supports English and a small set of other languages — Spanish, French, German, Japanese, Chinese depending on the source you check — but not Hindi or Indian regional languages. If your coursework happens in Hindi medium, Otter simply won’t understand you, no matter which plan you’re on.

Wispr Flow

Wispr Flow is the strongest option because it works inside almost any application. Students who want long-form writing and fast drafting can use this tool but unlimited dictation requires a subscription, which costs around $15 per month or $12 per month when billed annually. Since it supports more than 100 languages and gives accuracy for names and jargon along with AI editing, the cost is worth it.

VoiceToNotes.ai 

Its features include real-time transcription, grammar correction, AI summaries so it can become a useful tool for students which turn spoken thoughts into structured notes. Some professionals consider this tool as more affordable than many full-featured AI assistants but free usage is limited. The catch: accuracy still depends on microphone quality and background noise.

Mindgrasp

Mindgrasp is primarily an AI learning and content-understanding platform. Students can use it for lectures and study material — it helps in creating flashcards and quizzes automatically. Best for exam preparation and research but some features are tied to specific subscription tiers. 

Lisup 

Lisup focuses on accessibility and hands-free writing. It can be used across desktop applications so access will be easy and it is specifically designed for in-place speech-to-text features. It’s not built for broader use but enough for students to take notes easily. 

Soniox — the app actually built for Hindi dictation

Soniox is less well-known in student circles but solves exactly the gap Otter leaves open. It handles Hindi across regional varieties like Khariboli and Braj Bhasha, works system-wide across any app or text field on your phone rather than locking you into one note-taking interface, and covers 60-plus languages total with the ability to switch languages mid-sentence. 


It’s useful if you naturally code-switch between Hindi and English while explaining a concept to yourself. It’s free to start, with weekly free credits rather than a hard monthly cap, and the company states it doesn’t store your recordings or use them for model training, which is worth knowing if you’re dictating exam-prep notes you’d rather keep private.

Sarvam AI — worth watching, not quite a student app yet

Sarvam is India’s most-funded sovereign AI company, and its speech models (Saaras v3) handle 22 Indian languages with genuinely strong accuracy claims. But as of now, Sarvam’s product lineup is built mainly for enterprises — voice agents for banks and government call centers, APIs for developers — rather than a polished consumer app you’d install and use for lecture notes. 

A consumer-facing voice app was announced in February 2026, aimed at exactly this kind of mass-market, multilingual use case, but a public launch isn’t happening right now.

Read Also 👉 Why ChatGPT Ads Deserve a Place In Your 2027 Media Plan 

Why Do Students Need These Tools?

Most of the time students missed points while trying to understand the same topic simultaneously. Writing it down on paper or in a mobile is the same thing — it consumes a lot of time and misses points. So, these Voice-to-Notes Tools help students take notes without tiring their hands. 

There are some free and some paid tools, if you just need to take notes of what your processor is explaining then a free tool is enough for you. But if you are a Ph.D student or you need to do heavy research, organize every note, and make summaries from online content, you need a tool which can handle all of that, even if it costs you a little.

Which Speech-to-Text Tools are Best For Studies?

Google’s Gboard keyboard is the best free Voice-to-Notes Tools which I have used personally and crafting many documents in English, Hindi and Urdu. I recommended to students who wanted to take notes before exams and stop writing everything manually and waste their time. 


Gboard offers unlimited access to use on any other applications like docs, word, and on any device (mobile or laptop). Most of the students take their mobile to the college, so it runs smoothly. But sometimes it makes minor errors in spelling which you can edit later. 

Second is Wispr Flow but you have to pay after a limited use and many students can’t afford it but those who can afford can consider Wispr Flow as the best tool for making notes.

Read Also👉 Upgrade Laptop Like New Model In Low Budget

Conclusion for Voice-to-Notes Tools

The world is changing and for solving traditional problems by adapting new technology. One of the old problems is taking notes in a mid-session in your classrooms. Students have to understand the topic and write down their important concepts — two jobs at once.

If they forgot, they have to ask other students and it appears a problem if you don’t have a lot of friends. So the problem is solved now, you can spend your time to understand the topic without worrying about the notes as these Voice-to-Notes Tools do that job for you.

Leave a Comment

Your email address will not be published. Required fields are marked *

How to Apply for a Student Loan to Get a Higher Education & Make Career

Student Loan

How to apply for a Student Loan doesn’t come randomly in anyone’s mind. Getting into a good college is only half the battle. The other half starts the moment you realize a B.Tech at a decent private university now costs ₹8–15 lakh, an MBA at a tier-2 B-school can run past ₹12 lakh, and a master’s abroad easily crosses ₹40 lakh once you add living costs. 

If you don’t have that sort of money lying around, a Student Loan is the only realistic option — and how to get one usually determines how much of that money actually gets deposited into your account, and how much you end up overpaying in interest over the next 10 years. 

This guide walks through the process as it actually works in India in 2026, not the version that shows up in a bank’s marketing brochure.

How to Apply for a Student Loan Through the Vidya Lakshmi Portal

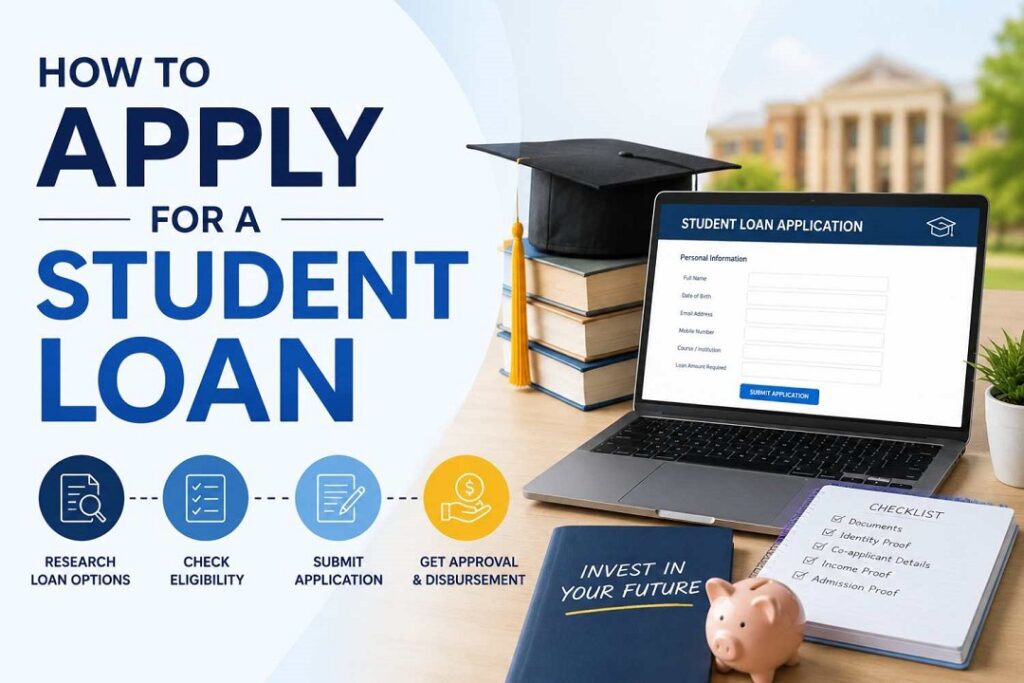
Almost every organized education loan in India now runs through the Vidya Lakshmi portal, a government-backed single window that connects more than three dozen banks and well over 100 loan schemes to one common form. Instead of visiting five bank branches and filling five different applications, you fill one — the Common Education Loan Application Form (CELAF), prescribed by the Indian Banks’ Association and accepted by every participating lender.

The process, in order:

  • Register on the portal with your email ID and a mobile number, ideally the one linked to your Aadhaar, since OTP verification runs through it.
  • Fill the CELAF in sections — personal details, course and institution details, cost breakdown, and your co-applicant’s financial information.
  • Upload KYC documents, academic transcripts, and your admission letter in the required digital format.
  • Use the “Search and Apply” tab to filter loan schemes by amount, interest rate, and whether you’re studying in India or abroad.
  • Shortlist and apply to a maximum of three banks in one go — a sensible mix is usually one public-sector bank (lower rate, slower processing) and one private bank or NBFC (faster, more flexible).
  • Track status from your dashboard. If a bank marks your application “on hold,” it means they want more documents — check the remarks column rather than waiting for an email.

The portal is also linked to the National Scholarship Portal, so if you qualify for a central or state scholarship, you can apply for it in the same sitting.

Where the PM Vidyalaxmi Scheme Fits In

Layered on top of Vidya Lakshmi since 2024–25 is the PM Vidyalaxmi Scheme, a Central Sector Scheme aimed specifically at students who’ve secured admission — through merit-based or open competitive selection — into a Quality Higher Education Institution (QHEI). The official list currently runs past 800 institutions and keeps expanding as new NIRF-ranked colleges get added, so don’t assume your college qualifies; check the current QHEI list on the portal before you plan around this scheme.

What it actually gets you:

  • No collateral, no guarantor for eligible loans. Some official sources describe this as applying to the entire loan regardless of amount; others cap the collateral-free portion at ₹7.5 lakh, after which the bank may ask for security on the balance. This detail genuinely varies by bank in practice — confirm it directly with your chosen lender before you apply, don’t assume either version.
  • A 75% government credit guarantee on loans up to ₹7.5 lakh, which is what makes banks comfortable lending without collateral in the first place.
  • Interest subvention during the moratorium period (course duration plus one year) — full interest subsidy if annual family income is up to ₹4.5 lakh, and a 3% subsidy if family income falls between ₹4.5 lakh and ₹8 lakh, both capped at loans up to ₹10 lakh.
  • Above ₹8 lakh family income, you still get the collateral-free structure and credit guarantee — you just pay the bank’s normal interest rate with no subsidy.

To claim the subvention, you submit an “intent” declaration on the portal along with income proof from an authorized state government authority — it isn’t automatic just because you’re eligible.

Eligibility Criteria You Need to Meet For Student Loan Across Indian Banks

Setting PM Vidyalaxmi aside, general education loan eligibility across Indian banks looks fairly consistent:

  • You need to be an Indian national with confirmed admission to a recognized, full-time regular course — part-time and distance programs are excluded by most lenders, though a few NBFCs make exceptions.
  • A co-applicant, almost always a parent or guardian, is required by nearly every bank once the loan crosses a modest threshold (often ₹4 lakh), and their income and credit history factor directly into how much you’re sanctioned.
  • For merit-based schemes like SBI’s Scholar Loan or PM Vidyalaxmi’s QHEI route, your entrance exam rank or admission channel matters as much as your family’s finances — these schemes exist precisely to reward the admission, not the collateral.
  • There’s no universal age cap, but banks do informally weigh whether you’re likely to complete the course and start repaying within a reasonable working-age window.

Documents to Keep Ready Before You Apply

Missing paperwork is the single most common reason applications sit in limbo for weeks. Have these ready before you start the CELAF, not after:

  • Admission letter and the institution’s official fee/cost structure
  • Mark sheets for 10th, 12th, and any prior degree
  • Identity proof — Aadhaar and PAN at minimum
  • Co-applicant’s income proof: recent salary slips or ITR, and the last six months of bank statements
  • Collateral documents, if your loan amount or scheme requires security
  • Passport and visa copy, if you’re studying abroad

Keep names spelled identically across every document — a mismatch between your Aadhaar and your admission letter is a small thing that causes real delays.

How Much Will It Cost You Across Every Sector Banks

Interest rates on Indian education loans in 2026 span a wide range depending on lender type:

  • Public-sector banks (SBI, PNB, Bank of Baroda, Union Bank, Canara Bank) generally price standard education loans between roughly 8% and 10.75% p.a., floating, tied to each bank’s repo-linked or external benchmark rate. As of mid-2026, the RBI repo rate itself sits around 6.25% — the actual benchmark moves at each monetary policy review, so treat any quoted rate as a starting point to verify, not a fixed number.
  • SBI’s Scholar Loan, reserved for students admitted to premier institutes like IITs, IIMs, and NITs, runs noticeably lower — roughly 6.9% to 7.65% p.a. — compared to its regular Student Loan Scheme at around 9.4% to 9.9%.
  • Private banks and NBFCs (HDFC Credila, Avanse, and similar) typically charge 9.5% to 16% p.a. Rates are higher, but sanction and disbursal are usually faster, and many offer larger unsecured amounts.
  • Most public banks give a 0.5% interest concession to girl students — worth asking about explicitly, since it isn’t always advertised upfront.
  • Several lenders, including SBI and PNB, offer a 0.5–1% rate discount if you pay simple interest during the moratorium period instead of letting it accumulate. Skipping this is the single most expensive mistake students make: unpaid interest during your study years gets added to the principal, so your EMI ends up calculated on a bigger loan than you actually borrowed.

Claiming the Section 80E Tax Benefit Once You Start Repaying

Once repayment begins, Section 80E of the Income Tax Act lets you deduct the entire interest component of your EMI from taxable income — not the principal, just the interest, but with no upper cap, which is unusual among Indian tax deductions.

A few conditions determine whether you actually qualify:

  • The deduction is available for a maximum of eight consecutive years, starting from the year you begin paying interest, or until the interest is fully repaid, whichever comes first.
  • It only applies if you’ve opted for the old tax regime — under the new regime, this deduction isn’t available at all, so run the comparison before you file.
  • The loan must come from a recognized bank, financial institution, or an approved charitable institution. A loan from an employer, a relative, or an informal lender does not qualify, no matter how similar the repayment terms look.
  • You can claim it for a loan taken for yourself, your spouse, your children, or a legal ward — and it applies whether the course was pursued in India or abroad.
  • You’ll need an interest certificate from your lender each financial year, clearly splitting principal from interest, to actually file the claim.

How To Avoid Application Rejection

A few patterns show up again and again in rejected or delayed applications: 

  • Applying to just one bank instead of shortlisting two or three through Vidya Lakshmi and comparing offers side by side
  • Assuming your college is on the PM Vidyalaxmi QHEI list without checking the current portal listing
  • Letting moratorium interest pile up instead of paying it as simple interest each quarter
  • Submitting documents where your name, date of birth, or address doesn’t match exactly across your Aadhaar, admission letter, and bank KYC. 

Each of these is fixable in an afternoon but only if you catch it before submission, not after a bank has already put your file on hold.

Select the Reliable Option for Student Loan

If you’ve been admitted to a QHEI on the current PM Vidyalaxmi list and your family’s annual income is under ₹8 lakh, start there through the Vidya Lakshmi portal — the interest subvention alone can save you lakhs over the loan’s life, and it’s the closest thing to free money in this entire process. 

If your institution isn’t on that list, or your loan requirement crosses ₹10 lakh, shortlist two or three public-sector banks, compare their post-moratorium rates head-to-head, and ask each one directly what your EMI looks like once the subsidy or discount period ends. Not the headline interest rate but that one question is where most students get blindsided.

Conclusion 

The paperwork for Student Loan application is simpler once you have your documents in order, have compared lenders and know the government schemes that apply to you. Vidya Lakshmi portal provides students a one-stop shop to apply for education loans and also compare the loans, while PM Vidyalaxmi can help eligible students by lightening their financial load through interest support and collateral-free loans. 

Before you accept any offer, look beyond the stated interest rate. Check the terms of the moratorium (temporary period in which you don’t have to start paying the regular EMI), your eligibility for subsidy, the amount you need to repay, the amount of collateral required and the total interest you will pay. A bit of comparison before signing can make a big difference to your finances after you graduate.

Leave a Comment

Your email address will not be published. Required fields are marked *

Scroll to Top