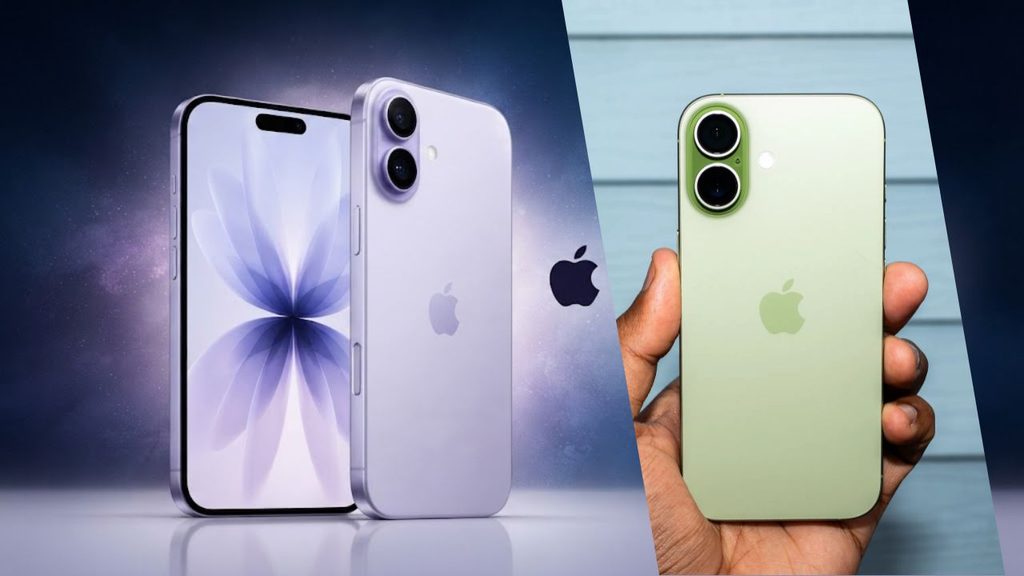
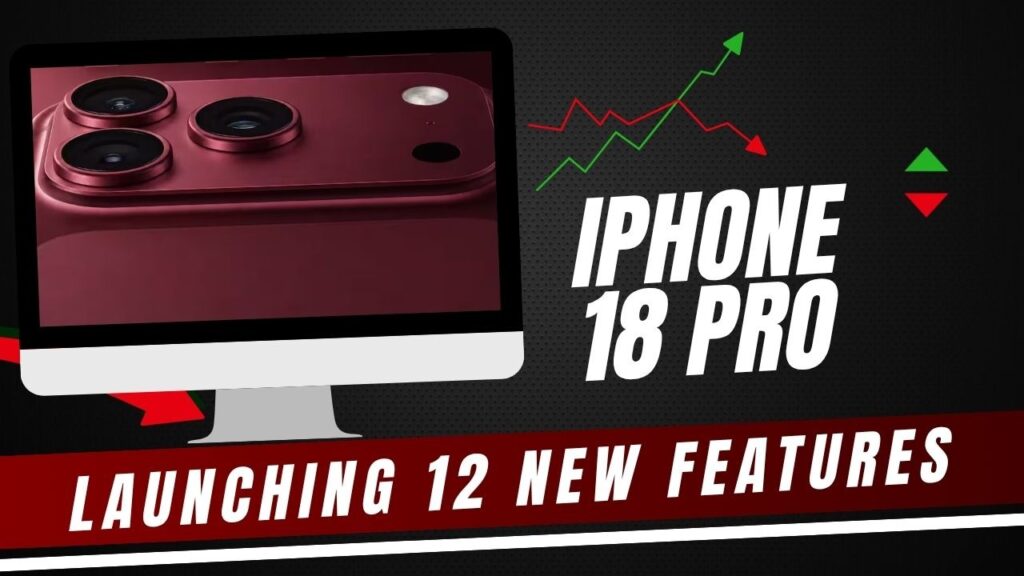
iPhone 18 Pro Launching Next Month: 12 New Features Worth Knowing About

iPhone 18 Pro

If you’ve been putting off a new iPhone purchase this month, that instinct is about to pay off. The iPhone 18 Pro launching next month means in September 2026, and unlike last year’s fairly incremental refresh, this generation brings changes that actually alter how the phone behaves day to day — not just how it looks in a colour catalogue. 

The iPhone 18 Pro comes up with twelve new features that keep resurfacing across leaks from potential sources, and enough of them line up with each other that the list is worth taking seriously, even months before Apple confirms anything on stage.

When Is the iPhone 18 Pro Launching in India?

Apple has not confirmed an exact date of launch but people are guessing according to the leaks of iPhone 18 Pro that it will launch on September 8 and other sources have cited a September 9 date, with sales starting around September 18. Either way, expect the announcement in the first half of September and phones on shelves roughly a week or two later — India has landed in Apple’s first launch wave for the last several cycles, so there’s no reason to expect a delay this time.

The bigger structural change is that Apple is reportedly splitting its iPhone 18 lineup across two events for the first time. Only the iPhone 18 Pro, iPhone 18 Pro Max, and Apple’s first foldable iPhone are expected this fall. The standard iPhone 18, a budget iPhone 18e, and a second-generation iPhone Air are said to be held back until around March 2027. If that holds, it’s a genuine break from Apple’s usual one-event calendar, not just a rumor footnote.

Read More👉 Best Student Laptops for School and University in 2026 

The iPhone 18 Pro Launching Next Month With New Features: 12 Upgrades Leaks 

1. A Smaller Dynamic Island

Apple’s Face ID flood illuminator is rumored to move under the display at the same time, allowing Apple to reduce the size of the pill-shaped cutout at the top of the display for the first time since its introduction. 

2. LTPO+ Displays

Screen sizes stay put at 6.3 inches and 6.9 inches, matching the iPhone 17 Pro line. What’s new is LTPO+ panel technology, which is expected to squeeze out extra battery life without changing the physical footprint.

3. Variable Aperture Camera

The 48-megapixel main camera is rumored to gain a variable aperture — a first for iPhone — giving more control over depth of field. Given how small phone camera sensors are compared to a real DSLR, how much this actually improves photos in practice is still an open question.

4. A20 Pro Chip on 2nm

This would be Apple’s first chip fabricated on TSMC’s 2nm node, up from the 3nm A19 Pro. There’s likely to be a huge jump in both performance and power efficiency, even if Apple hasn’t yet released any figures. 

5. Third-Generation C2 Modem

Apple’s in-house modem line continues past the C1 and C1X with a new C2 chip, expected to keep pushing speed and efficiency ahead of its predecessors.

6. 5G Connectivity via Satellite

Paired with the C2 modem, the iPhone 18 Pro is rumored to support satellite-based web browsing when there’s no Wi-Fi or cellular signal — useful well beyond emergency SOS messaging.
7. New N2 Wireless Chip

The chip that currently handles Wi-Fi, Bluetooth, and features like AirDrop and Personal Hotspot is due for an upgrade to N2. What specifically improves hasn’t leaked yet.

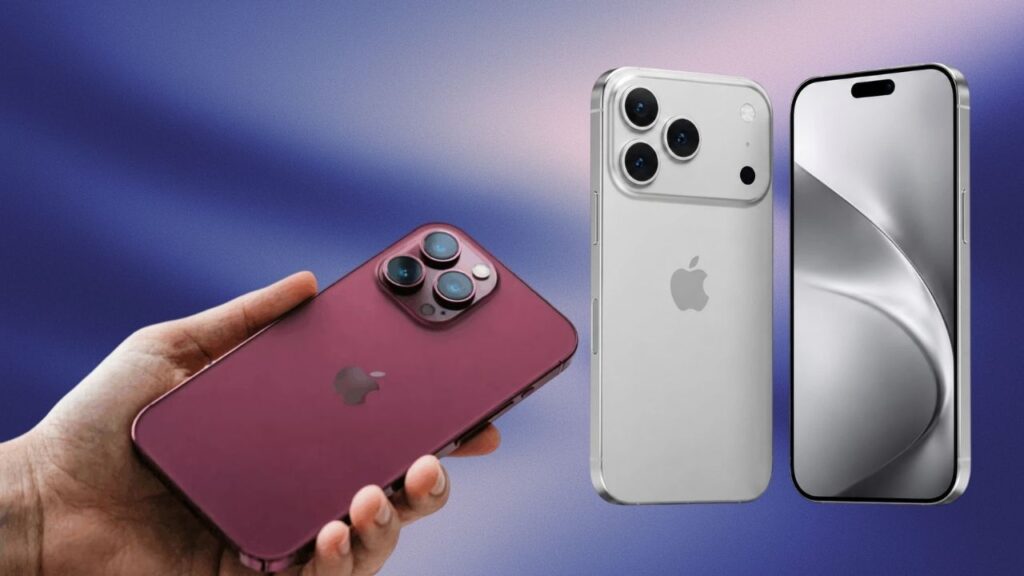
8. A New Dark Cherry Colourway

Reports consistently point to Dark Cherry replacing Cosmic Orange and Deep Blue as the standout shade, alongside Light Blue, Dark Gray, and Silver.

9. A Simplified Camera Control Button

Apple is expected to strip out touch sensitivity and haptic feedback from the Camera Control button, leaving a purely pressure-sensitive click — a response to complaints that the current button is fussy to use.

10. A Cleaner Rear Finish

The Ceramic Shield area around the MagSafe ring is rumored to move to a single frosted finish, replacing the two-tone look on current Pro models.

11. A Bigger Battery on the Pro Max

Alleged Chinese regulatory filings suggest the iPhone 18 Pro Max’s battery capacity could grow by close to 10% over the iPhone 17 Pro Max — a meaningful jump if it holds up.

12. A Thicker Pro Max Body

That extra battery could come with a price: the iPhone 18 Pro Max seems to be a bit thicker than the standard iPhone 18 Pro and last year’s Pro Max, according to leaks. 

iPhone 18 Pro Price in India: What to Expect

Still, no one outside Apple knows the real figure, so consider anything below as a pre-launch estimate and not a quote. Indian retailers trackers like Smartprix, Cashify and LatestLY are now pointing towards a base price of ₹1,39,900 for the 256GB base model of the iPhone 18 Pro — which would be ₹5,000 more than the iPhone 17 Pro started from. 
Some tech enthusiasts notes are less optimistic, citing rising costs for the 2nm chip and faster memory, with a few reports floating figures as high as ₹1,43,990 to ₹1,54,900 depending on storage tier and whether you’re looking at the standard Pro or Pro Max. The spread between these numbers is wide enough that none of them should be treated as settled until Apple confirms pricing at the keynote.

Should You Wait for the iPhone 18 Pro?

If you’re still on an iPhone 15 Pro or older, this generation is worth waiting for — the variable aperture camera and the A20 Pro’s efficiency gains are the kind of changes you’d actually notice in daily use, not just on a spec sheet. If you already own an iPhone 17 Pro, none of the 12 rumored changes look big enough on their own to justify an upgrade this cycle — the two most significant jumps, the larger battery and thicker body, apply mainly to the Pro Max. 

And if price is what’s holding you back either way, keep an eye on the iPhone 17 Pro once the new lineup launches — Apple typically keeps the outgoing Pro model on sale at a reduced price, and that discount is usually the better deal in late September than paying full price for year-one rumors that haven’t been battle-tested yet.

Read More 👉 Top Lightweight Student Laptops to Buy in 2026

Conclusion 

The iPhone 18 Pro launching next month seems like a worthwhile upgrade in a nutshell, featuring a new A20 Pro chip, variable-aperture camera, smaller Dynamic Island, better connectivity, and bigger Pro Max battery. But keep in mind that all of the 12 features are still leaks until Apple officially unveils the phone. 

If you have an older iPhone, then holding out for the September release is a good idea. If you’re already an iPhone 17 Pro owner, there’s probably no need to hurry unless the camera improvements or Pro Max battery life are plenty of temptation. 
Leave a Comment

Your email address will not be published. Required fields are marked *

Best Student Loans for College Students

Student Loans

Your admission letter came through and you are stressed about its fees? That’s the moment you’ll start looking for the best student loans for college students. Between tuition, hostel, a laptop, and living costs, a B.Tech at a decent private college or a master’s abroad can run anywhere from ₹8 lakh to over ₹1 crore, and very few Indian families are sitting on that kind of cash without dipping into a fixed deposit meant for something else. 

This is exactly where the best Student Loans in the market — from SBI’s Scholar Loan to NBFCs like HDFC Credila and Avanse, start doing real work, provided it actually fits your situation instead of just going with whichever bank branch is nearest to your house.

This blog walks through the loan for education options Indian students actually use in 2026 — public banks, private banks, NBFCs, and the government’s PM Vidyalaxmi scheme with real numbers, what each one is genuinely good at, and where it falls short.

Who Can Get These Loans for Education

If you’re an Indian student (or a parent reading this on their behalf) heading into an undergraduate program, a postgraduate course, or a study-abroad admission, and you need a study loan rather than paying out of pocket, this comparison is built for you. It splits lenders into three buckets — public sector banks, private banks, and specialised NBFCs because each serves a different kind of borrower, and picking the wrong bucket is the single most common reason students overpay by lakhs over a 15-year tenure.

Interest rates on education loans are floating and revised frequently by each lender’s internal benchmark. The figures below reflect indicative ranges reported by lenders and comparison platforms as of mid-2026. Treat every rate here as a starting reference, not a quote so confirm the live number on the lender’s own site before you apply.

Best Student Loans For College Students in India

1. SBI Scholar Loan / Global Ed-Vantage — Best for Domestic Students and Government-Bank Trust

  • Rate: roughly 8.15%–10.75%, MCLR-linked (floating)
  • Loan amount: up to ₹7.5 lakh without collateral for listed premier institutes; higher amounts with collateral, up to ₹1.5 crore under Global Ed-Vantage for study abroad
  • Processing fee: flat ₹10,000 — no percentage-based fee
  • Tenure: up to 15 years

SBI remains the default first stop for most Indian students, and there’s a simple reason: as the largest public bank, it consistently prices education loans lower than private banks and NBFCs, and its flat processing fee actually saves real money on larger loans compared to a percentage-based charge. 

The trade-off is speed — SBI’s sanction process for study-abroad loans can take four to eight weeks, and IBA guidelines require 15% margin money on foreign education loans above ₹4 lakh, meaning you’ll need to arrange that slice yourself. 

Best for: students with time before their visa deadline who want the lowest lifetime interest cost.

2. HDFC Credila — Best for Speed and High-Value Unsecured Loans

  • Rate: roughly 9.5%–13%, secured loans starting near 9.95%, unsecured (no collateral) starting near 11.25%
  • Loan amount: up to ₹50–60 lakh for premier institutes, sometimes higher
  • Processing fee: 1%–1.5% plus GST
  • Tenure: up to 15 years

Credila built its business on what it calls a “future employability” assessment rather than collateral value, which is why students without property to pledge still get approved here. Sanctions typically land in 7–14 days, which matters enormously when a visa interview is on the calendar and SBI’s timeline doesn’t fit. 

The catch is that unsecured Credila loans run meaningfully higher than SBI’s rate, and the processing fee, a percentage plus GST are added up fast on a ₹50 lakh loan. 

Best for: students on a tight admission or visa timeline who need fast, collateral-free approval and can absorb a higher rate.

3. Bank of Baroda — Best for Large Loans to Global Universities

  • Rate: competitive with SBI, generally in the 8.5%–11% band depending on the institute tier
  • Loan amount: up to ₹1.5 crore for premium global universities
  • Processing fee: typically lower than private banks; concessions available for girl students
  • Tenure: up to 15 years

BoB doesn’t get the same attention as SBI or the big NBFCs, but for students heading to genuinely expensive programs like top-50 global MBAs or engineering master’s — its higher loan ceiling and public-bank pricing make it worth a direct comparison. 

Best for: high-ticket study-abroad admissions where you need both a large sanction and a public-bank rate.

4. Avanse Financial Services — Best for Broad Course Coverage

  • Rate: roughly 11%–14.5%
  • Loan amount: up to ₹50–75 lakh
  • Processing fee: 1.25%–1.75% plus GST
  • Tenure: up to 15 years

Avanse is one of the few lenders that regularly finances courses public banks are cautious about — niche postgraduate programs, some online degrees, and vocational tracks. It’s genuinely useful when your course doesn’t fit a PSU bank’s approved list. The limitation is its rates sit at the higher end of the NBFC range, so it’s rarely the cheapest option on the table. 

Best for Student Loans for college students whose course or university isn’t covered by public-bank lending lists.

Read More👉 RRB JE Notification OUT With RRB JE Vacancy Of 3,993 Posts 

5. Axis Bank / ICICI Bank Education Loan — Best for Existing Bank Customers Wanting Fast Digital Processing

  • Rate: roughly 9.5%–13.5%
  • Loan amount: up to ₹40 lakh
  • Processing fee: moderate, varies by profile
  • Tenure: typically 10–15 years

If you or your parents already bank with Axis or ICICI, pre-approved education loans can be sanctioned in as little as 72 hours for existing customers, bundled with a forex card and a student account for study abroad. The point here is convenience, not price — you’re paying slightly more for an integrated, faster experience with a bank you already have a relationship with. 

Best for: existing customers who value speed and a bundled international banking package over shaving off the last percentage point of interest.

SBI vs HDFC Credila: The Two-Lender Face-Off

These two get compared constantly because they represent opposite philosophies — lowest cost versus fastest approval.

SBI Global Ed-VantageHDFC Credila
Starting rate~8.15%–9.65%~9.5%–11.25% (unsecured)
Processing feeFlat ₹10,0001%–1.5% + GST
Sanction time4–8 weeks7–14 days
CollateralRequired above ₹7.5 lakhOptional, employability-based
Best forLowest total interest costTight visa or admission deadlines

On a ₹50 lakh, 15-year loan, roughly every 100 basis points of extra interest costs about ₹7.5 lakh over the loan’s life, so the gap between these two isn’t cosmetic. Take Credila or Avanse first to secure fast disbursal for the visa file, then refinance into SBI once the loan is live and the pressure is off.


This works better than it used to, because the RBI’s Prepayment Charges Directions, effective January 1, 2026, banned foreclosure and prepayment charges on floating-rate loans to individual borrowers — a rule that covers nearly every education loan in this list. Before this, NBFCs could charge 2%–5% of the outstanding principal to close a loan early; that lock-in is now gone.

Don’t Skip the Government Route: PM Vidyalaxmi Scheme

Before comparing private lenders at all, check whether you qualify for PM Vidyalaxmi, the Centre’s collateral-free education loan scheme launched in November 2024. It isn’t a separate lender — it works through participating banks but it changes the math significantly for eligible students:

  • Collateral-free, guarantor-free loans up to ₹7.5 lakh, backed by a 75% government credit guarantee
  • Covers students admitted purely on merit (not management or NRI quota) to around 1,425 listed Quality Higher Education Institutions
  • A 3% interest subvention during the moratorium period for families with annual income up to ₹8 lakh, on loans up to ₹10 lakh
  • Rates capped at the bank’s benchmark lending rate plus 0.5%, with banks free to offer an extra 1% concession if you service interest during your study period
  • Subsidy is disbursed directly through the PM Vidyalaxmi Digital Rupee (CBDC) app

More than 1.12 lakh loans had been sanctioned under the scheme as of July 2026, so it’s no longer a pilot — it’s a live, functioning route worth checking on the PM Vidyalaxmi portal before you approach a bank directly.

Read More 👉 Best Student Laptops for School and University in 2026 

Two Rules That Apply Regardless of Which Lender You Choose

Section 80E tax benefit: the entire interest you pay on student loans for college students — not principal, and with no upper cap is deductible from your taxable income for up to 8 years from the year you start repaying. This applies to loans from any bank or approved NBFC and is one of the few genuinely uncapped deductions left in Indian tax law.

The girl-student concession: most public banks, including SBI and PNB, shave 0.5% off the standard rate for female applicants. It’s easy to miss because it’s rarely advertised loudly — ask for it explicitly when you apply for any of these student loans for college students.

Conclusion

If your priority is the lowest total interest over 15 years and you have a few weeks before your deadline, start with SBI — check PM Vidyalaxmi eligibility first if your loan need is under ₹7.5 lakh. 

If your visa interview or admission deposit deadline is within two weeks and you need money to move fast, HDFC Credila or Avanse will get you there, with the option to refinance into a cheaper public-bank loan later at no penalty under the new RBI rule. And if your course or university sits outside what PSU banks typically approve, Avanse’s broader course coverage is worth a direct call before you assume you’re out of options. 

Whichever lender you pick, don’t sign with the first offer you get on Student Loans for college students — pull two or three live quotes through the Vidya Lakshmi portal, apply the 80E deduction into your repayment planning from day one, and claim every concession you’re eligible for.

Note: Interest rates, fees, and scheme terms mentioned above are indicative and change frequently. Verify current figures directly with the lender or on official government portals before applying. 

Leave a Comment

Your email address will not be published. Required fields are marked *

Your Credit Score Ignores 90% of Your Financial Life — What Your First Credit Card Changes 

Credit Score

Once your first credit card is approved, you probably think that you are eligible for loan or finance. But you’re wrong because your credit score matters and it is built from repayment history not from your financial status or expenses. There are four active bureaus (CIBIL, Experian, Equifax, CRIF High Mark) in India and they all sit between 300 and 900 score. 

And it doesn’t know your salary, your savings account, your mutual fund SIPs, or the fact that you’ve never once missed a rent payment. It tracks exactly one thing closely: how you’ve handled borrowed money. 

That gap between what the score sees and what your financial life actually looks like is where most first-time cardholders get caught off guard.

What Your Credit Score Measures in Your Financials

A score is built almost entirely from repayment behavior. FICO, the US model most bureaus borrow their logic from, publishes its weighting: payment history (about 35%), credit utilization (about 30%), length of credit history (about 15%), credit mix (about 10%), and new credit inquiries (about 10%). 

It breaks it down, the ingredients look roughly like this:

  • Payment history — whether you’ve paid EMIs and card bills on time. This carries the heaviest weight, often estimated at around 30-35%.
  • Credit utilization — how much of your available credit limit you’re actually using. Maxing out a card, even if you pay it off in full, can quietly hurt you. 
  • Length of credit history — how long your oldest active account has been open. This is exactly why closing your first credit card years later can lower your score instead of helping it. 
  • Credit mix — a blend of secured loans (car, home) and unsecured ones (credit cards, personal loans) reads better than having only one type. 
  • New credit inquiries — every time you apply for a loan or card, a “hard inquiry” gets logged, and too many in a short window signals risk to lenders. 

CIBIL doesn’t publish its exact formula, but the underlying behavior it rewards and punishes is the same. None of this touches your bank balance. It only starts once you’ve borrowed something — a loan, an EMI, a credit card and shows how consistently you paid it back.

Read More 👉 Best App To Get Instant Loan Without Salary Slip

The 90% of Credit Score Never Sees Your Financial Life

Your salary doesn’t appear on your first credit card report. Neither does your savings balance, your fixed deposits, your stock or mutual fund portfolio, property you own, freelance or side income, or rent you’ve paid on time for years (unless you’ve specifically enrolled in one of the newer rent-reporting services, which are still rare in India). Utility bills and UPI spending don’t count either, since none of that is borrowed money. 

This cuts both ways. Someone with a strong income and zero loans can be “credit invisible” — no score at all, simply because they’ve never borrowed. Someone drowning in personal debt but paying the minimum on time every month can carry a technically decent score while their actual finances are falling apart. The number reflects repayment discipline, not net worth.

Why This Number Still Runs Your Financial Life

Even though it’s a narrow measurement, it’s the one lenders trust most. A home loan applicant with a score above 750 might get an interest rate a full percentage point lower than someone below 650 — on a 20-year loan, that gap alone can add up to lakhs of rupees in extra interest. 

Your score also decides which credit cards you qualify for and what limit you’re offered, and in some sectors — finance, banking, occasionally government roles — employers run a credit check as part of background verification. 

Landlords in a few metro markets have started asking for credit reports too. None of that is about how much you earn. It’s entirely about whether you’ve paid back what you owed, on time, before.

The Mistakes That Wreck a First-Time Cardholder’s Score

Paying Only the Minimum Due

The minimum due usually around 5% of the outstanding bill — keeps your account technically current, but the remaining balance starts accruing interest immediately, typically in the range of 3 – 3.5% a month, which works out to somewhere near 36–42% annualized. It’s one of the most expensive ways to borrow money that exists, and the balance compounds faster than most first-time users expect.

Maxing Out the Limit

Spending close to your full limit every month signals risk to lenders, even if you clear the bill in full. Keeping usage under roughly 30% of your available limit protects the score far more than people assume — this is often a bigger factor than the actual bill amount.

Applying for Multiple Cards in the First Year

Every new application triggers a hard inquiry, and each one dents the score slightly while sitting on your report for a couple of years. Several applications close together read to lenders as credit hunger, not creditworthiness.

Missing the Due Date, Even Once

A single day late usually just costs a late fee. But once a payment crosses roughly 30 days overdue, it typically gets reported to the bureau and that single entry can move the score sharply and stay visible for years.

Closing the Card Too Early

Shutting down  your first credit card within the first year shortens your average credit age, which is one of the more underrated factors in the score. A longer, active history — even on a card you barely use — tends to help more than starting fresh with a new one.

Read More 👉 How to Apply for an Education Loan Online

The Right Way to Spend From Your First Card

Treat it like a debit card with a receipt trail, not free money. Pick one or two recurring expenses — a mobile recharge, one subscription, fuel and route them through the card on autopay. This builds a steady, low-risk repayment pattern without tempting you into overspending. 

Pay the full statement balance every cycle, not the minimum. Check your statement monthly for errors or unfamiliar charges. Avoid withdrawing cash on the card entirely — interest usually starts from the day of withdrawal with no grace period, on top of a flat fee near 2.5–3%. 

And think twice before converting purchases to EMI, even “no-cost” ones; the discount you’d have gotten on the outright price is often quietly folded back into the total.

How Fast Can a Credit Score Really Move?

Scores don’t jump in percentages — there’s no such thing as a score rising “by 90%.” They move in points, and how fast depends on which factor you’re fixing. 

Utilization moves quickest: pay down a high balance before your statement date, and the next reporting cycle, usually 30 to 45 days later, can reflect a meaningful jump, sometimes 50 or more points on the 900-point scale, because utilization updates almost as fast as your balance does. 

Payment history moves slower and compounds instead: one on-time payment barely registers, but six to twelve months of consistent on-time payments builds a track record lenders actually trust. Bureau errors — a closed loan still showing as open, a paid card marked as defaulted, can also produce a fast correction once flagged, sometimes within a single reporting cycle. 

For someone starting with a thin or nonexistent credit file, a workable, lender-friendly score in six to twelve months of disciplined use is a realistic target. Overnight is not.

Before Cardholder Swipe That First Time

Pull your free annual report from the bureau and note your starting number before you spend a single rupee. Set autopay for the full statement amount, not the minimum, and add a separate calendar reminder a few days before the due date as backup. 

Pick one recurring bill to run through  your first credit card and leave the rest alone for now. Then check the number again in three months, not three weeks — that’s roughly how long it takes the system to actually reflect what you did.

Read More 👉 Business Ideas for Students With Zero Investment — Easy Startup Guide

Conclusion

Your financial health doesn’t increase your Credit Score and it is important to maintain that score. It’s a way for lenders to understand how responsibly you’ve handled borrowed money, not how much you earn, save, invest, or own. 

For a first-time cardholder, utilization should be lower, pay the statement balance on time, do not fill unnecessary applications, be patient and give time for your credit history to grow. Treat your first credit card as a tool for building trust with lenders, so when you actually need a bigger loan or good credit, you can get it easily. 

Leave a Comment

Your email address will not be published. Required fields are marked *

Festive Season Sale In October Is About to Reshape Smartphone Prices in India 

Festive Season Sale

This year’s Festive Season Sale in October will bring many new offers and discounts on electronic products — massive offers hit on smartphones. If you’ve been sitting on an upgrade — whether that’s finally moving off a three-year-old Galaxy or jumping into the iPhone ecosystem for the first time — this is the window the entire Indian smartphone retail calendar builds toward. 

When the sale is live, which smartphone will actually get a discount and what’s coming to this season, know everything before planning around.

When Does the Festive Season Sale Start?

The Amazon Great Indian Festival 2026 is going live on October 8 with no closing date, so treat this as a multi-week sale. Prime members get early access from October 7. This Festive Season Sale has flagged on many categories, including mobile phones, electronics, home appliances, and fashion. With 160,000 seasonal jobs secured by Amazon to handle the load, this shows how big this year’s event is expected to be.

Flipkart’s Big Billion Days 2026 goes live for everyone on October 9, a day after Amazon, with early access on October 8 for Flipkart Plus, Flipkart Black and select co-branded credit card holders. Flipkart has also been running a slower build-up than usual: Early Bird Deals started September 24, and official price reveals on flagship phones have been trickling out since September 26.

October 7–9 for early access across both platforms, then the main event running through most of October. If you’re the type who wants to plan a purchase around the calendar rather than react to a flash notification, mark October 7 as your first checkpoint.

What Discounts and Bank Offers to Expect

Neither platform has published final smartphone pricing yet — genuinely, this is one area where numbers are still moving daily, and anyone claiming exact final prices two weeks out is guessing. What’s confirmed on the banking side is more solid:

On Amazon, SBI credit and debit card users get a flat 10% instant discount on eligible transactions, including EMI purchases, and Amazon has said overall discounts across electronics could run up to 80%, with an additional 10% on top for SBI cardholders. There’s already a Prime Coupon Bonanza running ahead of the main event, offering up to ₹6,000 off select Samsung and Sony televisions — a hint at how aggressive the electronics category is shaping up to be.

On Flipkart, Axis Bank and ICICI Bank cardholders get a 10% instant discount on eligible debit and credit card transactions, Flipkart Plus and Black members get up to 12% additional card discount, and Bajaj Finance EMI options are being pushed hard for higher-ticket purchases like flagship phones. Flipkart is projecting discounts climbing as high as 90% across electronics, appliances, fashion and home decor — though that ceiling figure almost always applies to accessories and older inventory rather than current-generation flagships.

Best Smartphone Deals Expected This Festive Season

1. iPhone 17 (256GB) — Best for iOS Upgraders on a Budget

The launch price of iPhone 17 is ₹82,900 for 256GB storage but if you purchase 512GB, the price rises up to ₹1,02,900. Flipkart’s dropping iPhone 17 price under ₹80,000 during Big Billion Days. From above Rs 1 lakh to Rs 80 thousand, the difference is quite big.


At a sub-₹80,000 price point, this is the cheapest true current-generation iPhone has ever launched into a festive sale with outstanding features including 6.3-inch Super Retina XDR display, A19 chip, dual rear camera system. It is available in 5 colours — Black, White, Mist Blue, Sage and Lavender.

Limitation: You still don’t get the telephoto lens or ProMotion display that the Pro models carry, so heavy zoom-shooters and gamers chasing 120Hz will feel the gap. But a perfect model for anyone upgrading from an older iPhone who needs a clear camera and high-end features.

Read More 👉 Why ChatGPT Ads Deserve a Place In Your 2027 Media Plan 

2. Samsung Galaxy S25 Ultra — Best Flagship Value Pick

Samsung put the launching price ₹1,29,999 on Galaxy S25 Ultra which was around ₹84,999 after a discount during Amazon’s July Prime Day and as low as ₹94,999 during the May Great Summer Sale and both offers flagged by the same retailer. Now it’s preparing for the festive push. Expect festive pricing to land in a similar ₹85,000–₹95,000 band.


You’re getting a phone that was a ₹1.3 lakh flagship a year ago for roughly two-thirds the
price. Buyers who are searching for best cameras and display smartphones can afford the Snapdragon 8 Elite for Galaxy chipset, which still holds up against 2026 competition. The flagship specifications 6.9-inch Dynamic AMOLED 2X display at up to 2,600 nits brightness, 12GB RAM, titanium frame with Corning Gorilla Armor 2 glass. 

Limitation: It’s now the previous generation — no Galaxy S26’s Snapdragon 8 Elite Gen 5 or the newer Privacy Display feature, and Samsung’s software support clock started a year earlier than on the S26.

3. Samsung Galaxy S26 Ultra — Best for the Latest Hardware

Another Samsung’s flagship model launched in 2026 at ₹1,39,999 for 12GB+256GB and for higher storage, price rises up to ₹1,59,999 for 512GB and ₹1,89,999 for 16GB+1TB. This smartphone is delivering a high-end technology — Snapdragon 8 Elite Gen 5 for Galaxy, 6.9-inch display and first built-in Privacy Display for limiting side-angle screen visibility. The festive offer lands near ₹1,24,999 because July sale cuts to the same.


A 200MP main camera with an absolute hardware system which can’t be broken easily. Buyers who are looking for 2026 latest smartphones at a range over 1 lakh, this is the best time to think about it.

Limitation: Because it’s this fresh, don’t expect S25 Ultra–style 35% festive cuts. If your budget caps around ₹1 lakh, the S25 Ultra is the more realistic festive buy.

4. Samsung Galaxy S25 FE — Best Mid-Flagship Pick

Flipkart teased S25 FE deals alongside the S25/S25 Ultra as part of its Big Billion Days smartphone lineup, Galaxy S25 FE discounted prices will land near ₹60,000. Buyers who can’t afford S26 Ultra for the series design language and camera hardware, this one provides them the same two features at an affordable range in this festive season.

Limitation: Detailed specs and confirmed pricing are still pending official reveal — if you need certainty before buying, wait for Flipkart’s price-reveal window closer to the sale date rather than an early-bird listing.

Read More 👉 Apple iPhone Duo Changes the Cost Effectively With These Methods

Compare iPhone 17 vs. Galaxy S25 Ultra On an Overview

iPhone 17 (256GB)Galaxy S25 Ultra (256GB)
Expected festive priceUnder ₹80,000₹85,000–95,000 (based on recent 2026 sale pricing)
Display6.3″, Super Retina XDR6.9″, Dynamic AMOLED 2X, 2,600 nits
Standout strengthCleaner ecosystem, resale valueBigger screen, S Pen support, titanium build

If display size and a stylus matter more to you than the Apple ecosystem, the S25 Ultra is the better festive buy at a comparable post-discount price. If you want the newest chip generation with the smallest footprint, the iPhone 17 wins.

Don’t Lock Into One Platform Too Early

Amazon and Flipkart are running near-identical bank-offer structures this year, but the specific phone deals won’t be identical — Samsung’s S25 Ultra pricing has historically differed by a few thousand rupees between the two platforms in past sales, and the same is likely this October. 

Check both listings once early access opens on October 7–8 before finalising a purchase; a single-retailer comparison isn’t a real comparison.

Read More 👉 Upgrade Laptop Like New Model In Low Budget

Conclusion

If your budget is under ₹80,000 and you want the newest possible chip, wait for the iPhone 17’s Festive Season Sale price to drop and buy it in the first 48 hours of early access — historically, the steepest festive cuts on genuinely new-generation phones show up early, before stock tightens.

If you’re chasing flagship specs on a ₹85,000–95,000 budget, the Galaxy S25 Ultra is the stronger buy this cycle, since last year’s flagship pricing has already proven it can fall that far. And if you specifically want Samsung’s newest chip and can stretch past ₹1.2 lakh, hold out for the S26 Ultra rather than compromising — buying older hardware you’ll regret in a year isn’t really a discount.

One practical step regardless of which phone you pick: add it to your Amazon or Flipkart wishlist now, and note the current listed price before October 7. That’s the only way to verify a “festive discount” is real rather than a price that was quietly bumped up the week before the sale.

Leave a Comment

Your email address will not be published. Required fields are marked *

SSC CPO SI CAPF Online Form 2026

SSC CPO SI CAPF

The SSC CPO SI CAPF Online Form 2026 finally went live on 10 September, now you can go on the official website to fill it. The official notification of SSC CPO brings fewer seats and a reshuffled exam pattern. The Staff Selection Commission has opened applications for CPO Sub-Inspector posts in Delhi Police and Central Armed Police Force (CAPF) Exam 2026.

The window runs from 10 September to 30 September 2026, 11 PM, and if past years are anything to go by, the SSC server tends to buckle in the last 48 hours. Registering early isn’t just good advice, it’s basic risk management.

DetailsInformation
Exam nameSSC Sub-Inspector in Delhi Police and CAPFs Examination 2026
Conducting bodyStaff Selection Commission
Total vacancies1,871
Application modeOnline
Online application begins10 September 2026
Last date to apply30 September 2026
Official websitessc.gov.in
Application fee₹100 for applicable candidates
Fee exemptionWomen, SC, ST and Ex-Servicemen candidates

Vacancies SSC CPO Are Numbered This Year

There are a total 1,871 vacancies for 2026 announced by SSC which is less in numbers from last year. Even after CISF’s new Fire wing added 234 posts to the count. Still it doesn’t beat last year’s vacancy count. 

SSC CPO SI male seats rose from 142 to 205 and SI female vacancies doubled from 70 to 112 this year. CAPF SI (GD) postings, which usually get higher in number, have shrunk considerably this year.

Sub-Inspector in CAPF seats for male are 1173 and 147 for females. So the total empty seats in CAPF are 1320.

Sub-Inspector (Fire) in CISF also vacant for 234 male candidates. The category-wise distribution of seats is also accessible from the official notification. The conclusion is general category male seats are more in numbers than other categories or females.

Eligibility For SSC CPO in 2026 

Education and Age Limit For SI: Any bachelor degree from a recognised university is accepted. Candidates’ age must lie between 20 to 25 years for Delhi Police SI and CAPF SI. The age relaxation is given for 3-years (OBC) and 5 years (SC/ST).

CISF SI (Fire) runs on a separate, wider band of 18 to 30 years, so if you’ve aged out of the general SSC CPO bracket, this is worth a second look.

Male applicants for Delhi Police SI (Executive) must hold a valid LMV driving licence — both motorcycle and car — on the day of the physical test, not on the day of application. If you don’t have one yet, start the process now; RTOs aren’t fast. 

Read More 👉 Your Dollar Income Isn’t Fixed: How INR Volatility Changes Freelancers Earning 

Physical Standards For SSC CPO SI Post 

Candidate categoryMale heightMale chestFemale height
General/OBC/SC/EWS170 cm80 cm unexpanded, 85 cm expanded157 cm
Candidates from specified hill areas, North-Eastern States and Sikkim165 cm80 cm unexpanded, 85 cm expanded155 cm
Scheduled Tribe candidates162.5 cm77 cm unexpanded, 82 cm expanded154 cm

Physical Endurance Test for SI Post

CandidateEventRequirement
Male100-metre race16 seconds
Male1.6-kilometre race6.5 minutes
MaleLong jump3.65 metres in 5 attempts
MaleHigh jump1.2 metres in 3 attempts
Female100-metre race18 seconds
Female800-metre race4 minutes
FemaleLong jump2.7 metres in 3 attempts
FemaleHigh jump0.9 metre in 3 attempts

What’s Changed in the SSC CPO SI CAPF Online Form 2026 Exam Pattern

SSC has restructured both papers for this cycle, and different question counts and marks splits for Paper I and Paper II. 

Paper I remains the general screening test covering Reasoning, General Awareness, Quantitative Aptitude, and English Comprehension, and Paper II is the English Language and Comprehension paper, with negative marking of 0.25 for wrong answers carried over from the previous pattern. 

For the exact number of questions and marks per section, go to the official notification PDF provided by the Staff Selection Commission.

How To Apply — SSC CPO SI CAPF Application Form

  1. Visit on the official website mentioned in the above overview.
  2. If you already have a One Time Registration (OTR) profile, log in and apply directly against the SSC SI in Delhi Police and CAPFs Examination, 2026 listing. 
  3. New applicants need to register first. 
  4. SSC is pushing Aadhaar-based authentication hard this cycle — opt into it, because it exempts you from photo and signature rejections on formatting grounds and saves you from carrying printed photo ID to the exam centre. 
  5. The photograph itself has to be captured live through the application at the time of registration; you can’t upload an old passport photo. 
  6. Signatures go in as a JPEG between 10 and 20 KB. 
  7. General, OBC, and EWS candidates pay a ₹100 application fee; women, SC/ST, PwBD, and ex-servicemen candidates are exempt, as usual.
  8. Once you’ve paid and submitted, use the preview option before final submission of SSC CPO SI CAPF online form— corrections later are limited to a fixed window (8 to 10 October, per current reporting) and won’t cover every field.

Salary of Sub-Inspector in Delhi Police and Central Armed Police Force

Salary is given under Pay Level 6 of the 7th Pay Commission, candidates who get selected for SI post going to earn up to ₹35,400 which rise up to ₹1,12,400. The total in-hand salary of a SSC CPO SI CAPF is somewhere between ₹55,000 and ₹75,000 a month by adding allowances.

The fixed salary of Sub-Inspector is shared with you after the selection depending upon the location of your post, as metro postings pull the number toward the higher end because of city-category HRA.

Read More👉 UP SuperTET Vacancy Notification 2026: Check Out Details, Dates, & Eligibility

Conclusion

Fill SSC CPO SI CAPF Online Form 2026 now to secure your seat because waiting for the last hour means you can make a mistake while filling the form in hurry or the site will crash down at the last minute and you’ll miss the chance.

So don’t take that risk and apply now for Sub-Inspector, prepare for the theory examination as well as physical standards. Check the eligibility and get your documents ready before going to fill the form.

Leave a Comment

Your email address will not be published. Required fields are marked *

Bihar STET 2026 Online Form Out: Check Exam Syllabus and Pattern To Get Teacher Job

Bihar STET

Bihar STET 2026 Online Form Out on August 17 2026 and the last date to fill that form is September 15, 2026. Apply early to avoid last minute errors and server breaks, to score in Bihar State Eligibility Test (BSTET/STET 2026) examination, understand the exam syllabus and pattern.  

Download the official notification of Bihar STET 2026 to get all the details about eligibility, how to apply, and confirmed date for examination. While understanding the exam pattern which gets you selected.

Why Bihar STET 2026 Is Necessary For Teachers

Bihar STET — the Secondary Teacher Eligibility Test — isn’t a recruitment exam by itself. It’s a qualifying test conducted by BSEB that makes you eligible to apply for teaching posts in Bihar government-recognized schools, the same way BPSC TRE recruitment cycles have required in recent years. 

Clear it once, and BSEB now treats the certificate as valid for life rather than expiring after a few years, which is a meaningful change from the older TET/STET cycles where candidates had to keep re-qualifying. 

That’s the real reason so many people apply even when there’s no active teacher vacancy notification running at the same time — it’s a credential you bank for whichever recruitment drive comes next.

Bihar STET 2026 Important Dates

Save these dates into your calendar so don’t miss the day. Check updates on the official site every week for the exam date.

EventDate/Details
Notification released14/August/2026
Online application start17/August/2026
Original last date31/August/2026
Extended last date for application and fee payment15/September/2026
Official portalsThe dedicated application portal at stetregistration.cbrt.co.in
Exam DateThe exam date itself has not been officially announced. 

Eligibility Criteria for Paper 1 and Paper 2

The minimum age is 21 years as on August 1, 2026, confirmed consistently across the notification coverage. The upper limit is reported as 37 years for general candidates in some write-ups and as high as 42 for reserved and women candidates in others — since this figure hasn’t been consistent, check the age-relaxation table in the PDF notification itself before you rule yourself out.

Academic eligibility splits cleanly by paper:

  • Paper 1 (Secondary level, Classes 9–10): a Bachelor’s degree in the relevant subject with at least 50% marks, plus a B.Ed from an NCTE-recognized institution.
  • Paper 2 (Higher Secondary level, Classes 11–12): a Master’s degree in the relevant subject with at least 50% marks, plus a B.Ed.

Computer Science applicants are exempt from the mandatory B.Ed requirement if they meet the notification’s alternate qualification combinations, and the reduced qualifying marks, fee concessions, and age relaxations are only available to candidates with permanent Bihar domicile. 

Apply from outside the state, and you’re processed as a general-category male candidate regardless of your actual category — a detail that trips up a fair number of applicants from neighboring states every cycle.

Read More 👉 Your Dollar Income Isn’t Fixed: How INR Volatility Changes Freelancers Earning 

Bihar STET 2026 Online Form Fee Structure

The fee depends on category and on whether you’re applying for one paper or both:

  • General, BC, and EWS candidates: ₹960 for one paper, ₹1,440 for both
  • SC, ST, and PwD candidates: ₹760 for one paper, ₹1,140 for both

The fee is not refundable if you don’t pass the examination as this is the processing fee of your application.

Bihar STET 2026 Exam Pattern

Both papers follow the same structural pattern:

Exam ParticularsDetails
ModeComputer-Based Test (CBT)
Total questions150 multiple-choice questions
Total marks150 marks
Marks per question1 mark
Duration150 minutes (2 hours 30 minutes)
Negative markingNo negative marking

Of the 150 marks, 100 come from your chosen subject and the remaining 50 come from a section common to every candidate — Arts of Teaching and Other Competencies, covering General Knowledge, Reasoning Ability, Environmental Science, basic Mathematics, and Teaching Aptitude. 

Read More 👉 SSC CPO SI CAPF Online Form 2026

What To Study For Bihar STET Examination?

The subject-specific syllabus for Paper 1 broadly mirrors the graduate-level curriculum taught across Bihar’s universities. For Paper 2, it steps up to the graduate honours-level syllabus used for that subject in state universities — meaningfully deeper than Paper 1, which is worth remembering if you’re eyeing both papers back to back.

Your subject accounts for two-thirds of the total marks, so subject depth should be where most of your study hours go. But don’t write off the 50-mark common section as an afterthought — because most candidates do treat it as an afterthought, a candidate who actually revises General Knowledge, Reasoning, Environmental Science, and Teaching Aptitude systematically picks up an edge that’s disproportionate to how little competition they face there.

How to Apply for Bihar STET 2026

  1. Go to the official application portal of Bihar STET.
  2. Start a new registration and fill in basic details — name, mobile number, email.
  3. Verify your mobile number via OTP; a login ID and password get generated and sent to you.
  4. Log in and complete your personal and educational details in the application form.
  5. Upload a recent photograph, signature, and the required certificates.
  6. Pay the application fee online through the available payment modes.
  7. Submit the form and save or print the confirmation copy.

Several candidates in this cycle have reported that correction options after final submission are limited. Double-check your subject choice, category, and uploaded documents before you hit submit rather than assuming you can fix it afterward.

Selection Process and Certificate Validity

There’s no interview or separate merit round for STET itself — selection is based purely on your normalized CBT score against the qualifying threshold for your category. 

General category candidates need 50% to qualify; SC, ST, PwD, and women candidates need 40%. Once you clear that bar, BSEB issues a certificate that, under current policy, doesn’t expire — meaning you carry that eligibility forward into whichever Bihar teacher recruitment drive (including future BPSC TRE rounds) comes next, rather than needing to re-clear STET every cycle.

Read More 👉 Apple iPhone Duo Changes the Cost Effectively With These Methods

Conclusion

Bihar STET 2026 Online Form Out in August and now the deadline is coming, so you still have time to apply for the teacher eligibility test. Knowing the exam syllabus and pattern will help you get a high score and open many opportunities.

The one thing worth deciding today is whether you’re eligible for both papers — because qualifying for STET is separate from being recruited into a specific post, applying for both when you meet both qualification bars simply widens which recruitment drives you can walk into later without paying for and sitting through a second STET cycle. 

And since the exam date isn’t out yet, don’t waste energy hunting for a leaked schedule — put that time into the subject syllabus instead, since that’s the one variable in this entire process that’s already fully in your control.

Leave a Comment

Your email address will not be published. Required fields are marked *

Scroll to Top