Best Lightweight Sunglasses for Student Life 

Sunglasses

A pair of sunglasses in a college backpack is a choice of your comfort. When the college campus is large and you need to walk in direct sunheat or you go out randomly somewhere with your friends and your eyes start to burn in the heat. That’s where you start hunting for Best Lightweight Sunglasses for students, the best is the one which gives you comfort, weightless, and perfect for your face.

What Actually Matters for Campus-Ready Sunglasses

Frame weight comes down to material, not brand name. TR-90 and polycarbonate frames flex instead of snapping when they get crushed in a bag, and they sit lighter on the nose during a three-hour library stretch than metal or thick acetate does. UV protection — specifically UV400 — isn’t optional no matter how cheap the pair is; it’s the one spec that protects your eyes rather than your outfit. 

Polarization is worth paying a little more for if you’re on a bike or scooter daily, since it cuts glare off wet roads and car windshields far better than plain tinted lenses. And because these things get lost, borrowed by roommates, or sat on at least once a year, price-to-replacement-cost matters more here than it would for a pair you’d baby at home.

The 5 Best Lightweight Sunglasses for Students 

1. Fastrack Polarized Wayfarers and Aviators

Price: ₹950–₹5,000 | Frame: TR-90 polycarbonate | Lens: UV400, polarized options | Best for: tightest-budget daily wear
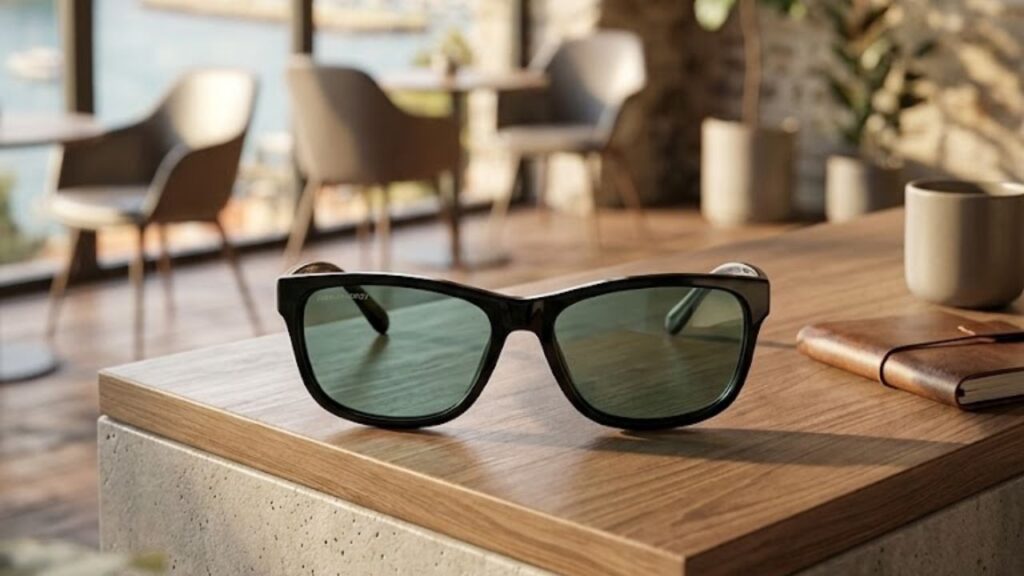

Fastrack’s entry-level polarized range starts under ₹1,000 and still comes with a 1-year warranty on lenses and frames, which is unusual at that price point. The TR-90 build is genuinely flexible — it survives the kind of backpack abuse a rigid acetate frame won’t. The trade-off is build quality at the very bottom of that price range: some buyers report the cheapest models feeling plasticky compared to what ₹2,000+ gets you in the same lineup. Good for someone who wants a backup pair as much as a main one.

2. Vincent Chase by Lenskart

Price: From ₹999, polarized from ₹1,299 | Frame: TR90 | Lens: 100% UV protected, polarized | Best for: best value-for-money on a first “real” pair
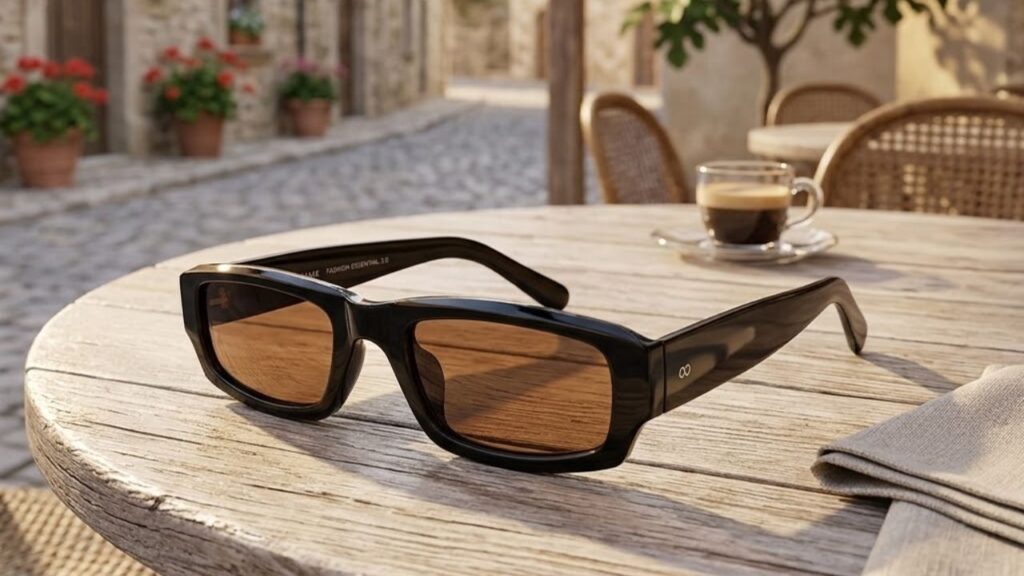

Vincent Chase is Lenskart’s in-house line, and it’s built around the same TR90 material for the same reason — daily wear without weight. The advantage over Fastrack is availability: Lenskart runs frequent Buy 1 Get 1 offers on this line, which effectively gets you a backup pair for the price of one. The catch is that heavy discounting means style availability shifts often, so a specific frame you like online today may not be there in three months if you need a replacement in the exact same shape.

3. OPIUM Eyewear

Price: ₹1,500–₹5,000 | Frame: lightweight polycarbonate | Lens: UV400, polarized, AVS coating | Best for: students who scratch or drop glasses often
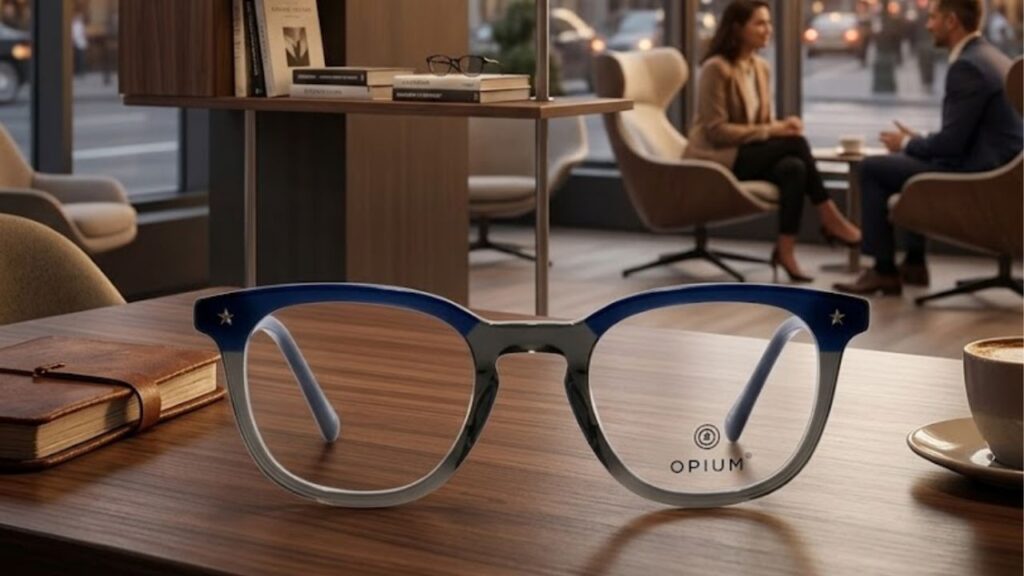

OPIUM’s AVS lens coating adds hydrophobic, oleophobic, and anti-static properties on top of standard UV/polarized protection — practically, that means fewer smudges from fingerprints and better scratch resistance when the lenses rub against keys or coins loose in a bag. It sits a notch above Fastrack and Vincent Chase in price, which is the real trade-off: you’re paying for lens durability, not a jump in style tier.

4. IDEE

Price: ₹899–₹1,499 | Frame: lightweight, sporty builds | Lens: UV protected | Best for: gym, sports, or an active daily commute
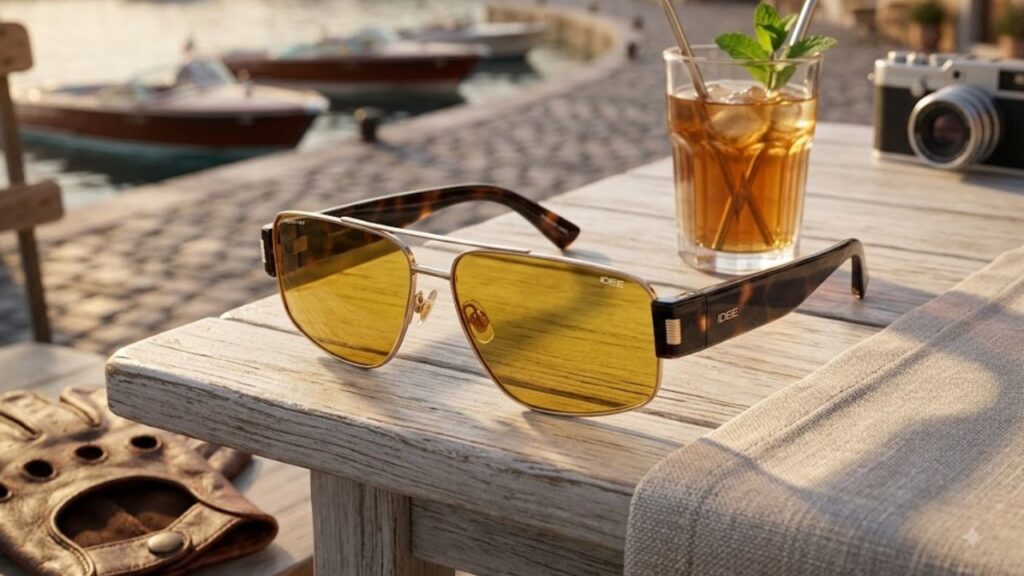

IDEE leans into bold, sporty designs — wraparounds and neon accents rather than classic wayfarer shapes — and stays cheap while doing it. If your daily routine includes a run, a cycle to campus, or intramural sports, the closer-wrap fit holds better than a flat wayfarer frame. The limitation is versatility: the sportier shapes don’t double as well for a formal event or an internship interview the way a classic frame does.

5. Ray-Ban (Aviator / Wayfarer)

Price: roughly ₹7,000–₹15,000 depending on style and retailer | Frame: acetate/metal | Lens: UV400, optional polarized | Best for: one pair meant to last through all four years

Ray-Ban is the outlier on this list by price, and it’s here for a specific reason: it’s the one pair that isn’t disposable. The Original Wayfarer and Aviator have been in continuous production since 1952 and 1937 respectively, which means replacement parts, nose pads, and repairs are easy to find at any optician years later — something none of the budget brands above can promise. It only makes sense if you can absorb the upfront cost and genuinely won’t be swapping styles every semester.

The Real Face-Off of Fastrack & Vincent Chase 

These two get compared constantly because they’re the two brands most students actually cross-shop, so here’s the direct read:

FastrackVincent Chase
Entry price₹950₹999
Polarized entry priceIncluded in mid-rangeFrom ₹1,299
Warranty1 year (lens + frame)Standard return window, no stated 1-yr warranty
Where to buyFastrack’s own site, Titan Eye+, Flipkart, Tata CLiQLenskart, Amazon.in
Recurring offersOccasional salesFrequent Buy 1 Get 1

If warranty coverage matters more to you than getting two pairs, Fastrack wins. If you’d rather have a spare pair sitting in a drawer for when the first one inevitably gets sat on, Vincent Chase’s BOGO structure is hard to beat on pure economics.

Which One Should You Actually Buy?

If your budget is genuinely under ₹1,200 and you just need something functional for the sun on your walk to class, get the Fastrack or Vincent Chase entry model — there’s no meaningful difference in daily performance between them at that price. If you’re riding a two-wheeler daily, prioritize a polarized lens over anything else on this list; glare off a windshield or wet road is a real safety issue, not just comfort. 

If you’re the person who’s cracked three pairs of earphones and lost two water bottles this year, don’t buy OPIUM or Ray-Ban — buy the cheapest polarized Fastrack you can find and expect to replace it. And if you’ve got one splurge in your accessory budget for the year and want something that’ll still be wearable at your graduation photos, the Ray-Ban is the only pair on this list built to actually last that long.

One habit that extends your sunglasses lifespan –  a hard case, not the soft pouch that comes in the box. Most lens scratches on student sunglasses don’t happen while wearing them, they happen loose in a bag next to keys and a laptop charger.

Read More👉 iPhone 18 Pro on EMI: A Complete Buying Guide

Conclusion

The Best Lightweight Sunglasses for Everyday Student Life aren’t always expensive. Whatever you opt for, be sure to focus on UV400 protection, a lightweight frame, a comfortable fit, and polarization for when glare is an issue. Toss a hard case In Addition your backpack, and even a modest pair can make it through life on the daily grind of college. Pocket your case for your backpack and even a thrifty pair can easily keep up with daily college life. 
Leave a Comment

Your email address will not be published. Required fields are marked *

UP Anganwadi Bharti 2026 — District-Wise Vacancies & Recruitment Details

UP Anganwadi Bharti 2026

UP Anganwadi Bharti 2026 recruitment is live and you can apply if the application portal is still live in your district. There’s no one deadline for the recruitment drive because it has a lot of separate district-level drives. It offers various posts such as Karyakatri and Sahayika, so these are open for females only.

First, understand the structure, eligibility, and selection process for UP Anganwadi Bharti then apply with all the required documents.

ParameterDetails
Recruitment NameUP Anganwadi Bharti 2026 (ICDS, Uttar Pradesh) 
Conducting AuthorityDistrict Programme Officer (DPO), Bal Vikas Seva evam Pushtahar Vibhag, UP 
Department / SchemeIntegrated Child Development Services (ICDS), Women & Child Development, UP 
Posts OfferedAnganwadi Worker (Karyakartri), Mini Worker, Anganwadi Helper / Sahayika 
Total Vacancies (Indicative)~60,000–61,600+ posts 
Eligibility Only female candidates, 10th / 12th pass
Residency ConditionCandidate must be resident of the same village/ward of the Anganwadi centre for which she applies
Application FeeNo fee for any category (General/OBC/EWS/SC/ST) 
Notification & Application WindowMain notification from Nov 2025; applications open/close district-wise through early–mid 2026 
Salary (Indicative)Around ₹5,500 – ₹12,000 per month 
Official WebsiteClick Here

Structure of UP Anganwadi Bharti 2026 — District by District

The notification is out from each district for the recruitment under the state government which directed the Department of Women and Child Development, to fill vacant Anganwadi Karyakatri (Worker) and Anganwadi Sahayika (Helper) posts across Uttar Pradesh. Instead of one recruitment drive, each District Programme Officer releases and manages notification and recruitment for their district at different times.

DistrictPostsLast date to apply
Jhansi223 (across 9 CDPOs)7 /September /2026
Maharajganj3051 /September /2026
Chitrakoot92 (23 Karyakatri + 69 Sahayika)5 /September /2026
HamirpurActive16/September/ 2026
BalrampurActive23 /September /2026
Amroha (J.P. Nagar)105 (across 7 projects)24 /September /2026

Earlier in the year, Bagpat and Kannauj ran their own window for 760 combined posts, applying from 25 June to 16 July 2026 — that cycle is closed, and candidates there are now waiting on the merit list.

Who Can Apply For UP Anganwadi Post

A few conditions hold across nearly every district notification:

  • Only female candidates are eligible — there’s no male category in this recruitment. 
  • Female candidates should be between 18 and 45 years, calculated as on 1 July 2025. Relaxation given only reserved category.
  • Anganwadi Karyakatri posts sometimes require an Intermediate marksheet, depending on the district rules. 
  • Helper (Sahayika) posts have historically carried a lower bar in some districts, occasionally as low as 8th pass.

The condition that trips up the most applicants isn’t age or education — it’s domicile. You can’t apply to whichever district has the most vacancies. Each post is tied to a specific ward (in urban areas) or gram/nyaya panchayat (in rural areas), and you must be a permanent resident of that exact unit. A vacancy list in Jhansi is not open to a resident of Kanpur, even within the same state.

Read More 👉 UP SuperTET Vacancy Notification 2026: Check Out Details, Dates, & Eligibility

Vacancies Numbers Are Huge

The total vacancies are more than 60000 across the state. Open your district’s latest 2026 notification PDF to check the vacancy number.

DistrictPost TypeVacanciesKey Detail
FatehpurWorker + Helper389150 Worker + 239 Helper (Aug–Sept 2026)
BandaWorker122Last date 22 Sept 2026
HamirpurWorker80Last date 16 Sept 2026
UnnaoWorker336Last date 11 Aug 2026
GhaziabadHelper341Last date 07 Aug 2026
JhansiWorker (Karyakatri)223Across 9 projects; last date 07 Sept 2026
Kanpur NagarHelper (Sahayika)307Across 12 projects; last date 05 Sept 2026
KushinagarWorker245Project-wise split available
KushinagarHelper (Sahayika)214Separate Helper notification
MaharajganjWorker + Helper305164 Worker + 141 Helper
SonbhadraWorker201Project-wise vacancy table available
MuzaffarnagarWorker146Anganwadi Worker posts only
GhazipurHelper1,352Among larger Helper batches
BulandshahrWorker + Helper678Combined posts
BagpatHelper374Helper-only batch
AzamgarhHelper265Helper-only batch

Selection Process & Application Fee

There’s no written test and, in the vast majority of district notifications reviewed so far, no interview either. Selection is by merit list, built from your marks in 10th, 12th, and graduation, all being equal. There’s no application fee for any category, including SC, ST, PwBD, and general female candidates — this recruitment is free to apply for, full stop.

Salary Of UP Anganwadi Posts

A ₹10,000/month for Anganwadi Worker, ₹7,500 for Mini Worker, and ₹4,500 for Helper as honorarium (not salary — these are Anganwadi posts, not salaried government service, and the distinction affects things like PF and pension eligibility). 

Getting Your Application In Before Your Window Closes

Applications go through upanganwadibharti.in 

On the homepage, you’ll find a running list of “active” district notifications with their upload and closing dates; this list changes weekly as new districts come online and others close.

Fill your details correctly in the form and submit with all the necessary documents attached. There is no application fee, so apply early and correctly.

The real trap here is timing, not eligibility. Most district windows stay open for only two to four weeks from the upload date — Hamirpur’s notification, for example, went up on 27 August and closes 16 September, an 18-day window. 

Bookmark the official portal itself, and search for your specific ward or gram panchayat, not just your district name; that’s the actual unit your eligibility is judged against.

Documents Required To Apply

Gather your documents first before your district application portal goes live. The necessary documents are listed in the notification PDF but you can also catch it here:

  • Your education proof – any 10th, 12th, and graduation marksheets, 
  • Domicile certificate for resident confirmation, 
  • Caste certificate (if you belong to reserved category), 
  • Aadhaar/ PAN Card, and 
  • A recent passport size photograph 
  • Signature on the blank page

Get ready with all these documents before your ward’s notification even drops.

Read More 👉 Planning MBBS or Master’s Abroad? Country-Wise Costs, Loan Limits and Lenders

Conclusion

UP Anganwadi Bharti 2026 notification is out but recruitment is active in some districts and closed in few districts. If the recruitment is active in your region then apply now before it gets closed. The vacancy numbers are huge, more than 60,000 posts are vacant and these seats are only open for females. 

But you must be the resident of that village to apply, and the documents must be prepared including your adhaar, high school marksheet, domicile certificate etc. You can apply for free but check the notification before you apply for the Karyakatri and Sahayika position.

Leave a Comment

Your email address will not be published. Required fields are marked *

iPhone 18 Pro on EMI: A Complete Buying Guide

iPhone 18 Pro

Apple hasn’t confirmed a single detail about the iPhone 18 Pro yet, but that hasn’t stopped Indian buyers from searching iPhone 18 Pro EMI options months before launch — and for good reason. With expected pricing starting north of ₹1,34,000, paying the full amount upfront isn’t realistic for most people. 

The real question isn’t whether you should use EMI. It’s which EMI actually saves you money, and which one just makes an expensive phone feel cheaper than it is for a few months.

When Is the iPhone 18 Pro Launching in India?

Every recent report points to September 2026, alongside the iPhone 18 Pro Max and for the first time — Apple’s foldable iPhone. What’s changed this year is the rest of the lineup. Bloomberg’s Mark Gurman reported that Apple is splitting its release schedule for the 18 series: only the Pro, Pro Max, and the foldable arrive this September, while the standard iPhone 18 and a new iPhone 18e get pushed to spring 2027. If that holds, this is the first year in a while where the “regular” iPhone won’t launch alongside the Pro models.

Going by Apple’s usual pattern (the iPhone 17 event was held on September 9, 2025, with sales opening ten days later), a keynote in the first two weeks of September 2026 is the safest bet, with stock hitting stores roughly a week to ten days after that. Some trackers are floating September 8–9 specifically; others leave more room, up to September 10. Take the exact date as a placeholder until Apple sends out invites, which usually happens about three weeks ahead of the event.

Expected iPhone 18 Pro Price in India

Price leaks are all over the place right now, which is normal this far out. Here’s the range being reported across sources as of this writing:

VariantExpected India price
iPhone 18 Pro, 256GB₹1,34,900 – ₹1,44,900
iPhone 18 Pro, 512GB₹1,52,500 – ₹1,69,990
iPhone 18 Pro Max, 256GB (starting)₹1,49,900 – ₹1,60,000

A few sources argue Apple will hold pricing close to the iPhone 17 Pro’s ₹1,34,900 launch price, citing “aggressive supplier negotiations” to protect India pricing. Others expect a hike tied to the RAM bump (12GB is the rumored figure) and camera hardware upgrades — the iPhone 18 Pro is rumored to carry a triple 48MP setup with a periscope telephoto lens and a variable-aperture main camera, on a 2nm A20 Pro chip. Rumors are also split on whether Face ID moves under the display this generation or stays as-is; one supply chain report specifically says it won’t happen this year due to production delays.

Budget for the ₹1,34,900–1,44,900 band on the base 256GB Pro, and don’t be surprised if the number lands closer to the top of that range once Apple accounts for import duty and GST on the final config.

What’s the Actual Difference In No-Cost EMI vs Standard EMI? 

This is where most buyers get it wrong. “No-cost EMI” doesn’t mean the bank is doing you a favour — it means the retailer or Apple absorbs the interest that would normally apply, so you pay roughly the sticker price split into installments instead of sticker price plus interest. Depending on the bank, this shows up in one of two ways: the interest is stripped out at checkout, or you’re charged interest upfront and it comes back to you as cashback within about 90 days (this is how ICICI’s scheme works on longer tenures). Either way, you’ll still pay a processing fee, GST on that fee, and — if you close the loan early — a foreclosure charge, typically around 3% of the outstanding principal plus the next month’s interest.

Standard EMI is the version without the safety net: real interest, usually in the 12–16% per annum range on credit card conversions, on top of the base price.

The gap adds up fast. On a ₹1,34,900 iPhone 18 Pro, a 24-month standard EMI at 14% p.a. works out to roughly ₹6,477 a month — about ₹20,500 more than the phone’s actual price by the time you’re done paying. The same tenure under a genuine no-cost scheme costs ₹5,621 a month, with no premium at all. That ₹20,500 difference is the entire reason to check which scheme you’re actually being offered before you tap “confirm” at checkout.

Read More👉 Best Laptops for Coding and Programming: Top Picks for Every Budget

Where You’ll Be Able to Buy iPhone 18 Pro on EMI

You’ll have more than one route in, and it’s worth comparing before you commit to any single one. Apple’s own online store runs its no-cost EMI tie-ups directly with Bajaj Finance, HDB Financial Services, ICICI Bank, IDFC First Bank, and TVS Credit — the current scheme window on Apple’s authorised platforms runs through late September 2026, which should carry into the 18 Pro’s launch. Apple Authorised Resellers such as iStore, Unicorn, Croma, Reliance Digital, and Vijay Sales layer their own instant cashback offers on top for Axis Bank, ICICI Bank, and SBI Card users, usually on 6-month no-cost tenures with low-cost EMI kicking in beyond that.

Amazon and Flipkart are the other major channels, particularly around sale events — Amazon’s Great Freedom Sale and Flipkart’s Freedom Sale both ran in early August 2026, and both platforms typically repeat similar EMI-plus-bank-discount stacking for major flagship launches. Flipkart also supports the Bajaj Finserv Instant EMI Card for buyers without a traditional credit card. Debit card EMI is more limited — HDFC, Axis, and ICICI extend it to pre-approved debit cardholders, but the pool of eligible customers is smaller and interest rates run similar to credit card EMI.

Whichever channel you pick, check the fine print on tenure caps — 6-month no-cost EMI is nearly universal, but 12- and 24-month no-cost schemes are usually restricted to specific banks and specific card tiers.

How Much Will Your Monthly EMI Be?

Based on the expected price bands above, here’s what a genuine no-cost EMI would look like at common tenures:

Tenure256GB Pro (~₹1,34,900)512GB Pro (~₹1,52,500)Pro Max 256GB (~₹1,54,900)
3 months₹44,967₹50,833₹51,633
6 months₹22,483₹25,417₹25,817
9 months₹14,989₹16,944₹17,211
12 months₹11,242₹12,708₹12,908
24 months₹5,621₹6,354₹6,454

These are straight divisions of the expected MRP with no interest added — that’s what “no-cost” is supposed to mean. If a bank quotes you anything higher than these figures for the same price and tenure, ask specifically whether interest is being charged, because it likely is.

Exchange Offer + EMI Combo — Lowering Your Effective EMI

Trading in your current phone reduces the amount you actually finance, which lowers every EMI figure above. As an example: on a ₹1,44,900 iPhone 18 Pro, a mid-range trade-in like a working iPhone 13 128GB might fetch around ₹15,000 in exchange value plus a ₹6,000 exchange bonus — a combined ₹21,000 off, bringing the amount you’d actually put on EMI down to ₹1,23,900. Financed over 12 months no-cost, that’s roughly ₹10,325 a month instead of ₹12,075.

The catch is that the trade-in values swing enormously based on the model, storage, and physical condition of your old device, and different assessors don’t agree with each other. Apple’s own trade-in estimate, a reseller’s in-store quote, and a third-party service like Cashify can differ by several thousand rupees for the same phone. 

Get quotes from at least two sources before you finalise, and remember that exchange bonuses on top of the base trade-in value are usually time-limited promotions, not permanent policy — they’re the kind of thing that disappears the week after a big sale ends.

Step-by-Step Guide To Buying iPhone 18 Pro on EMI

  1. Shortlist your retailer first, not the phone colour. Compare what Apple’s own store, your nearest authorised reseller, Amazon, and Flipkart are each offering on EMI tenure and bank tie-ups — the same phone can carry different effective costs depending on where you buy it.
  2. Check your card’s pre-approved EMI limit. Most banks let you check this via SMS or net banking before you shop, so you’re not caught out at checkout with a card that can’t support the tenure you want.
  3. Get an exchange quote in advance if you’re trading in. Apple’s trade-in tool and your reseller’s in-store estimate both take a few minutes and give you a real number to plan around.
  4. Select the EMI option at checkout that matches your card and target tenure. No-cost options are usually listed separately from standard EMI — don’t assume the first EMI option shown is the no-cost one.
  5. Confirm the breakdown before you pay. Look for a line item showing interest and processing fee separately. If the total EMI amount adds up to more than the phone’s price divided by the number of months, you’re paying interest somewhere.
  6. Read the foreclosure terms. If there’s a chance you’ll want to pay off the balance early, know the foreclosure charge upfront rather than finding out later.
  7. Save your EMI schedule and transaction confirmation. You’ll need these if a cashback-style no-cost EMI scheme (like ICICI’s) hasn’t been credited on schedule.

Read More👉 iPhone 18 Pro Launching Next Month: 12 New Features Worth Knowing About

Conclusion 

The iPhone 18 Pro’s price and launch date will stay rumors until Apple actually sends out event invites, and it’s worth waiting for that confirmation before you lock in a purchase decision — leaked pricing has moved by thousands of rupees between reports even in the past few weeks. 

But the EMI math you plan around today will hold regardless of the exact final price: the difference between a genuine no-cost scheme and a standard one is real money, often ₹15,000–20,000 over a two-year tenure, and it has nothing to do with which bank has the nicest app. 

Compare the tenure and the bank before you compare the storage variant, get your exchange quote sorted early if you’re trading in, and read the checkout screen closely enough to know exactly what you’re signing up for, not just what the monthly number says.

Leave a Comment

Your email address will not be published. Required fields are marked *

Your Dollar Income Isn’t Fixed: How INR Volatility Changes Freelancers Earning 

INR Volatility

If you are a student or IT engineer and have a side freelancing business then exchange rate updates is the second in your search list. Once you understand Impact of Exchange Rates On Freelancers In India and how it moves forward then you can earn a little more. Let’s take a look at some important points to understand INR Volatility isn’t about what you’re actually thinking.

You raised the invoice in August. $1,000, net 30, client in Austin. By the time the payment actually lands in your account in September, the number in rupees isn’t what you calculated when you sent it. Maybe it’s more. Maybe it’s less. Either way, you didn’t do anything different — the client paid exactly what they owed — and your income still moved. 

That gap is what most freelancers mean when they say the rupee is “volatile,” and most of them are only half right about what that word actually costs or earns them. 

Current Changes In INR Volatility 

As of September 9, the dollar was trading around ₹95.13, after touching two-month highs near ₹94.4 the week before on the back of sustained Reserve Bank of India intervention. Zoom out to the 12-month view, the rupee has weakened roughly 8% against the dollar over the past year. For a freelancer billing in USD, that’s not a warning sign — it’s a raise you didn’t ask for.

Run the math on a flat $1,000 invoice. At a rate near ₹88 (roughly where the pair sat a year ago, working backward from the reported annual move — treat this as an approximation, not a verified historical quote), that invoice cleared around ₹88,000. 

At today’s rate, the same $1,000 clears closer to ₹95,000. Same client, same scope, same invoice — ₹7,000 more in your account, before any platform fees. If your Gigs, your budgeting, or your client pricing only accounts for the dollar amount, you’re missing the part of your income that moved on its own.

Why “Volatile” Doesn’t Mean “Falling” 

If you thought “the rupee is volatile” means “the rupee is always losing value, brace yourself.” But that’s not what volatility means, and it’s not what the data shows. The rupee gained about 0.9% in the week leading into September 9, with the RBI actively defending the band using its foreign exchange reserves. A currency that can move up or down 1% in a week, depending on which government or central bank decides to act, is unpredictable — not one-directional.

The near-term pressure right now is coming from oil. Brent crude jumped roughly 8% to around $97 a barrel after US-Iran tensions escalated, and India imports the overwhelming majority of the crude it uses, so a sustained spike pushes the rupee the other way — weaker, which again works in a dollar earner’s favor, but also raises input costs across the economy, indirectly squeezing the Indian clients some freelancers also serve. 

Layer on the US Federal Reserve’s meeting scheduled for September 15–16, where a rate move could swing global dollar demand overnight, and you’ve got a currency pair reacting to three or four separate levers in the same month. Betting on “the rupee only goes one way” is how freelancers get caught flat when it doesn’t.

Read More 👉 UP Anganwadi Bharti 2026 — District-Wise Vacancies & Recruitment Details

Impact of Exchange Rates On Freelancers In India

Here’s the part that costs freelancers real money and rarely makes it into the currency conversation: the spread between the rate you see on Google and the rate you actually receive. This gap is usually bigger than the market’s actual weekly movement. And it fills only when you understand Impact of Exchange Rates On Freelancers In India.

PayPal is the most expensive route by a wide margin — a cross-border transaction surcharge that can run up to 4.4%, stacked with a currency markup of roughly 3.5–4.5%, pushes total cost toward 6% on some routes. 

Payoneer, common for Upwork and Fiverr payouts, charges around 1% to move funds to your bank plus an FX markup that can reach 2% on withdrawal into a different currency — so a $2,000 month can quietly lose $50–60 to fees that never show up as a single visible number. 

Wise is the outlier: it settles at the mid-market rate — the actual number you’d see on Google — with a transparent fee that’s usually under 1% for most USD-to-INR transfers, which is why it’s become the default for freelancers paid directly by clients rather than through a marketplace.

None of that shows up when you’re only watching the headline USD/INR number. A freelancer who tracks the exchange rate obsessively but invoices through PayPal is optimizing the wrong variable.

Read More 👉 Foreign Education Loan Currency Explained: How INR Depreciation Can Increase Your Loan Cost 

How To Check Your USD Income is Moving Forward

Stop checking “what’s the rupee doing today” in isolation. Three things move it, and all three are trackable without a finance degree: RBI intervention behavior (visible in how tightly the rate is held to a band, like the ₹94.5–95.3 range this week), Fed rate decisions (scheduled, public, and usually priced in days ahead), and oil price swings (Brent crude, since India’s import bill is the direct transmission line into rupee weakness or strength).

Practically, that means two things for how you run your freelance income. First, match your payout method to your income source — Payoneer if most of your work comes through marketplaces, Wise if you invoice direct clients — because the fee gap between them is often larger than a month’s currency movement. 

Second, if you’re pricing recurring retainers in USD, revisit them quarterly rather than annually; an 8% currency shift plus a fee structure you haven’t audited in a year is easily a 10–12% swing in what a “fixed” retainer actually pays you in rupees.

Your dollar invoice was never the number that mattered. The rupee number that hits your account is — and that number has three separate forces acting on it before you even get to the part your payment platform quietly takes.

Read More 👉 Planning MBBS or Master’s Abroad? Country-Wise Costs, Loan Limits and Lenders

Conclusion 

For Indian freelancers, earning in dollars doesn’t mean earning a fixed amount. The USD/INR rate, RBI and Fed decisions, oil prices, and payment-platform fees can all change what finally reaches your bank account. A $1,000 invoice can be worth noticeably more or less in rupees without the client changing a thing.

The smart move isn’t to predict the impact of Exchange Rates On Freelancers In India. It’s to understand how currency movements affect your real income, compare payout fees, and review your USD pricing regularly. For IT students planning to freelance or work with overseas clients, learning this early can help turn Dollar Income into something you can actually budget around.

Leave a Comment

Your email address will not be published. Required fields are marked *

SIP For Beginners: Best Time To Start is Your First Salary  

SIP

If you are a fresher then you should understand the value investment to secure your future. SIP for beginners is a basic core to let you know how truly you can enjoy your first paycheck. There’s this urge to celebrate — a new phone, a trip, dinner out every other night. Nothing wrong with any of that. But somewhere between the celebration and the next paycheck, most of us miss a quiet window that never really opens this wide again.

That window is the gap between “I have no financial responsibilities yet” and “I have financial responsibilities I can’t avoid.” And the best tool for that window is SIP which most people postpone for years.

They are 100% safe but not guaranteed. The risks involve which kind of mutual fund investors seek to invest in (equity, debt, or hybrid) not the process itself. 

What Is a SIP?

SIP stands for Systematic Investment Plan. Strip away the jargon and it’s simple — you invest a fixed amount, usually into a mutual fund, at regular intervals (usually monthly), instead of putting in one large sum at once.

Think of it like a gym membership for your money. You don’t need a big lump sum to start. You just need to show up consistently, month after month, and let the process do its work.

Why Your First Salary Is the Ideal Starting Point

There’s a reason financial advisors keep repeating this, even though it sounds like a cliché: time is the one resource that actually multiplies your money for you.

When you invest early, you’re not just investing your money — you’re investing years. And years, thanks to compounding, behave less like addition and more like multiplication.

Say you invest ₹5,000 a month starting at age 23, versus someone who starts the same amount at age 33. Assuming a similar average return over time, the person who started ten years earlier could end up with a corpus that’s not just proportionally bigger — it could be several times larger by retirement. The extra decade at the start does more work than an extra decade added at the end.

This isn’t about being lucky or picking the “right” fund. It’s about giving your money the maximum amount of time to grow.

Read More 👉 Your Credit Score Ignores 90% of Your Financial Life — What Your First Credit Card Changes 

How To Manage SIP Along With Your Daily Expenses

This is a fair point. Rent, EMIs, family contributions, that gym membership you forgot to cancel — early salary life is expensive. But this is exactly why starting small matters more than starting big.

A SIP doesn’t demand a large amount. Many funds let you start with as little as ₹500 a month. The goal in your first year isn’t to build wealth overnight — it’s to build the habit of paying your future self before you pay for anything else.

Pay yourself first, Instead of saving whatever’s left after spending, you flip the order — invest first, spend what remains.

Maintain Your Psychology To Empower Yourself Financially

Your spending habits calcify fast. The lifestyle you build in your first two years of earning tends to become your baseline. Once you get used to spending your entire salary, increasing that SIP amount later feels like a sacrifice, even if you’re earning more.

Starting a SIP with your first paycheck means your lifestyle grows around a slightly smaller number from day one. You never miss what you never got used to spending.

Read More 👉 Collateral vs No Collateral Loan Amount Where Collateral Starts Making Financial Sense

How To Avoid Common Mistakes — SIP For Beginners

Waiting for the “right” market conditions. SIPs are designed to work through ups and downs — that’s the entire point of investing at regular intervals instead of timing the market.

Choosing funds based on friends’ recommendations. What worked for your colleague may not match your goals or risk appetite.

Stopping the SIP the moment markets dip. Volatility is normal, not a signal to panic. Long-term SIPs are built to absorb short-term noise.

Not linking the SIP to an actual goal. A vague “let me just invest” often loses motivation. Tying it to something — a house down payment, early retirement, a five-year trip fund — makes it easier to stay consistent.

A Simple SIP For Beginners Way to Start

You don’t need a finance degree or a stockbroker uncle to get going. Most banking apps and investment platforms let you set up a SIP in under ten minutes:

1. Pick a fund category based on your goal and time horizon (equity for long-term growth, debt for shorter, safer goals).

2. Decide an amount you can commit to without stress — even a small one.

3. Automate it. Set the SIP date right after your salary credit date so it happens before you have a chance to spend it.

4. Increase it gradually as your income grows — many platforms let you “step up” your SIP automatically each year.

Read More 👉 Switching Jobs? Don’t Ignore Your EPF, NPS, and Mutual Fund Investments 

Conclusion

Nobody regrets starting a SIP early. Plenty of people regret waiting for the “perfect moment” that never quite arrives. Your first salary isn’t just your first taste of financial independence — it’s the cheapest, most flexible starting line you’ll ever get for long-term wealth building.

Start small. Start messy if you have to. Just start with the first one. A SIP for beginners guide will help you understand everything from why it is important to how to start, you just have to decide how much you can give for your future.

This post is for general awareness and educational purposes only. Mutual fund and SIP returns are subject to market risk. Please evaluate your own financial goals, risk appetite, and consult a financial advisor before making investment decisions.

Leave a Comment

Your email address will not be published. Required fields are marked *

IIT BHU Non-Teaching Recruitment 2026 — Vacancy and How to Apply

IIT BHU Non-Teaching Recruitment

IIT BHU Non-Teaching Recruitment 2026 is currently live, visit official website to fill the form. The online application time will end on 01/October/2026. It is conducted by the Indian Institute of Technology (Banaras Hindu University), Varanasi to fill 55 regular vacancies across various administrative, technical, engineering, library, and Rajbhasha cadres.

Candidates who are eligible for this recruitment can apply but make sure that you must have official educational documents in hand before applying. Other necessary documents are also required during filling the application.

ItemDetail
OrganizationIndian Institute of Technology (Banaras Hindu University), Varanasi
Total vacancies55 posts (Group B & C)
Application modeOnline via SAMARTH portal only
Online application window25 Aug 2026 – 01 Oct 2026, 5:00 PM (last date extended)
Physical copyMandatory: printout + documents by Speed Post within 7 days of last date
SelectionShortlisting + possible Screening/Written Test, GD, Presentation, Interview (as per post)
Nature of appointmentRegular with probation; institute may offer on contract basis in some cases

Application Fee

Post GroupGeneral / EWS / OBC (Male)SC / ST / PwBD / All Female
Group B (e.g., Junior Superintendent, Assistant/Junior Engineer, JTO)₹500Nil
Group C (e.g., Junior Technician, Junior Library Assistant)₹250Nil

Essential Qualifications Required For IIT BHU Non-Teaching Recruitment 

The eligibility criteria depends on the posts you are applying for because it requires knowledge in that particular area. 

  • Bachelor’s degree in any discipline with at least 55% marks for a Junior Superintendent and supervisory experience also required (3 years at Level 5 or equivalent). 
  • Bachelor’s degree in B.Sc. or B.E./B.Tech or a Diploma in engineering with at least 55% marks for Junior Technician is required. But Diploma holders must also have 1 year of experience in the same field. 
  • Civil Engineering post sets a rule that candidate must qualify B.E./B.Tech or 3-year Diploma in engineering and an experience certificate.
  • To apply for Assistant Engineer, you must have a B.E./B.Tech or Diploma in Civil/Electrical Engineering with extensive experience (5–8 years). 
  • You are required for Bachelor’s/Diploma in Library & Information Science with 55% marks to Junior Library Assistant post. 

Read Also 👉 RRB NTPC 2026 Online Form: Graduate and UG Level Dates, Vacancies, and How to Apply

IIT BHU Non-Teaching Recruitment 2026 Vacancy Breakdown (post-wise)

Post NameCadreGroupPay Level (7th CPC)VacanciesUpper Age Limit
Junior SuperintendentAdministrativeBLevel 621 35 yrs
Junior Technician (Group-I: Chemistry/Physics)TechnicalCLevel-34 27 yrs
Junior Technician (Group-II: Mech/Met/Ceramic/Mat Sci)TechnicalCLevel-311 27 yrs
Junior Technician (Group-III: Electrical/Electronics)TechnicalCLevel-33 27 yrs
Junior Technician (Group-IV: Civil/Arch/Mining)TechnicalCLevel-34 27 yrs
Junior Technician (Group-V: CSE/IT/CCIS)TechnicalCLevel-34 27 yrs
Junior Library AssistantLibraryCLevel-3230 yrs
Assistant EngineerEngineeringBLevel 82 40 yrs
Junior EngineerEngineeringBLevel 63 35 yrs
Junior Translation OfficerRajbhashaBLevel 61 35 yrs

Selection Process IIT BHU Non-Teaching Recruitment

The selection process typically includes an initial screening of applications, based on online data. Shortlisted candidates may be called for Written Test / Skill Test / Presentation or Interview (depending on the post requirements) and document verification. 

Schedules will be sent only by email to registered IDs; no hard copies. Visit the official website of the IIT BHU to check the lists of shortlisted/non-shortlisted candidates. The reason is also mentioned there for your status. 

How to Apply (step-by-step)

  1. Go to SAMARTH portal: https://iitbhunt.samarth.edu.in if you wanna apply for IIT BHU Non-Teaching Recruitment 2026.
  2. Register → fill personal, educational, and experience details carefully (no edits after submission).
  3. Upload photo/signature and required documents.
  4. Pay application fee (if applicable).
  5. Submit online by 01 Oct 2026, 5:00 PM.
  6. Take a printout of the submitted form.
  7. Now you have to send that printout along with copies of your required qualification documents and experience certificate by courier to the Registrar, IIT (BHU), Varanasi – 221005. Application No., Advertisement No., and Post Name & Code must be written on the envelope.
  8. If you’re a serving Govt/Autonomous/Educational employee, ensure your application is forwarded through Proper Channel within 7 days of the last date; upload NOC & Vigilance Clearance (or produce at interview).

Read Also 👉 Festive Season Sale In October Is About to Reshape Smartphone Prices in India 

Conclusion 

IIT BHU Non-Teaching Recruitment 2026 drive is on-going on an official portal. Apply now or you’ll miss the deadline, but check your eligibility before applying and download the official notification for more deeper details. The vacancy breakdown is given so you can guess the competition level for your exam.

Leave a Comment

Your email address will not be published. Required fields are marked *

Scroll to Top