Canara Bank Apprentice Recruitment 2026: 3,500 Seats, Online Form Closes 17 October

Canara Bank Apprentice Recruitment 2026

The Canara Bank Apprentice Recruitment is happening right now, if you are graduated from the university then fill out the form. There are a total of 3,500 Graduate Apprentice seats. The selection doesn’t require a written test, it is based on 12th or diploma marks.

 for 2026-27 offers 3,500 Graduate Apprentice seats with no written test. Selection runs on your 12th or diploma marks. The online form opened on 1 October and shuts on 17 October 2026, and there is one registration you must finish before you can even start it.

The monthly stipend of Rs 16.650 will be given to the apprentice, in-hand earning would be Rs 10,500. Fill the form now and take a seat to start your career journey in the banking sector.

Canara Bank Apprentice Recruitment 2026

Canara Bank Apprentice Recruitment will live from 1 October to 17 October 2026, it is the window to jump into the opportunity. 

The 3,500 seats are split by category: 

Category / StateSeats
Unreserved1,541
OBC845
SC553
EWS335
ST226
Total (category-wise)3,500

The seats are distributed all over India, so check your state’s figures. Karnataka has the most seats at 581, followed by Uttar Pradesh (409), Tamil Nadu (391), Andhra Pradesh (247), Kerala (240) and Maharashtra (205). But Delhi has not a much higher figure—93 and Bihar 122. 

Some states have almost nothing: Manipur has 3 and Mizoram 2. You apply for one state, so pick it deliberately.

Who Is Eligible For Canara Bank Apprentice Recruitment

You need a graduation degree in any discipline from a recognised university. You must have a certification of education and age limit is given:

Candidates who are born between 1988 and 2006 are not somewhere in the 20 — 28 years. So check your date of birth because the candidate’s age must lie in this range. 

Upper age relaxation is given to reserved categories in which SC/ST gets 5 years, 3 years for OBC (non-creamy layer) and 10 years for PwBD. Female candidates who are divorced and remarried, widows can also get age relaxation for 35 years (general), 38 (OBC), 40 (SC/ST).

Widows, divorced women and legally separated women who have not remarried get relaxation up to 35 years for General/EWS, 38 for OBC and 40 for SC/ST.

There is also a language condition. Be careful while selecting the state because local language is important to know. If you have studied that language in school then there is no need for a test. Everyone else is tested at document verification, and failing it means you won’t be engaged.

How Selection Works Without an Exam

The notification describes a state-wise merit list built from your marks in Class 12 (or diploma), highest first. There is a cut-off to clear: 60% for General candidates and 55% for SC/ST/PwBD. After the merit list comes document verification with the language test, then a medical examination.

Your graduation percentage doesn’t drive the ranking. Your 12th marks do. A candidate with a modest degree but 88% in Class 12 can outrank a university topper who scraped through school. Don’t fill the wrong number in the form or you’ll be rejected.

Read Also👉 Google Launches Fitbit Air in India: Features, Price and Availability

Monthly Stipend and Career Growth

This is a 12-month apprenticeship, not a permanent job, and the bank’s notification describes it that way. The stipend is Rs 16,650 a month, made up of Rs 10,500 from Canara Bank and Rs 6,150 as the government’s share through direct benefit transfer. 

Take it as training with an income and a bank name on your CV. This matters for your career rather than nothing as a working experience.

How to Fill the Canara Bank Apprentice Online Form 2026

Register on the NATS portal (nats.education.gov.in) and complete 100% of your profile to get an enrollment ID. Keep your NATS Enrollment ID ready, as it is required in the Canara Bank application form.

  1. Visit the official Canara Bank website: canarabank.bank.in. Then go to Careers and then click Recruitment.
  2. Open the link for “Engagement of Graduate Apprentices in Canara Bank under the Apprentices Act, 1961 for FY 2026-27.”
  3. Click New Registration and enter your basic details, including name, mobile number, and email ID.
  4. Open a website and click on the log in, now you have to enter credentials you have received in the message. 
  5. The application form opens, fill NATS Enrollment ID along with your other information such as personal details, educational qualification, category, and communication details carefully.
  6. Select your preferred state where you know the local language, don’t choose according to the vacancy number. 
  7. Upload your photograph, signature, left thumb impression, and handwritten declaration in the required size and format.
  8. Pay the application fee, if applicable, through the available online payment method.
  9. Review every field carefully, then click Submit. And download and print the confirmation page/application form for future reference.

Don’t leave this for the last weekend. The form will probably be at its slowest in the final days.

Read Also 👉 Gemini 4 Argon: How the New AI Model Can Help Students and Teachers

Conclusion

If you got a first division in your 12th, then finish your NATS profile today and apply for Canara Bank Apprentice Recruitment 2026. Get an opportunity to start your career in banking, as this is the training for exposure. 

Check the vacancies and fill the correct details in the form so you won’t get rejected later. If you’re from Uttar Pradesh and read Hindi or Urdu, the 409 UP seats make more sense than a Karnataka application you can’t support with a marksheet.
Leave a Comment

Your email address will not be published. Required fields are marked *

How to Apply for an Education Loan Online

Education Loan

Your admission letter has a deadline attached to it, and so does the deposit your college wants. That’s usually the exact moment families realise they need an education loan and have no idea where to start — which bank, which portal, how long it takes, or whether the college fee will actually reach the institute on time. Applying for an Education Loan online in India isn’t hard once you know the sequence, but doing it in the wrong order costs weeks you don’t have.

Here’s the sequence that actually works, plus the numbers most guides skip.

Start On The Vidya Lakshmi Portal, Not a Random Bank Branch

The government’s PM-Vidyalakshmi portal (pmvidyalaxmi.co.in) exists precisely to stop students from filling out ten different forms at ten different bank branches. It currently lists 86 education loan schemes from 38 banks, and lets you fill one Common Education Loan Application Form (CELAF) and send it to up to three lenders at once. Each bank evaluates it independently and responds through your dashboard — you compare offers side by side instead of chasing branch managers.

You can still apply directly through a bank’s own app (SBI YONO, HDFC’s portal, or an NBFC like Credila or Avanse), and for study-abroad loans that’s often faster. But if you’re not sure which lender fits your profile, the portal is the better starting point because it also flags which subsidy schemes you qualify for — more on that below.

The Standard Step-By-Step Process on the Portal

Register on The Portal

with your mobile number, email, and Aadhaar. You’ll set up a student login and can save your progress partway.

Fill The CELAF  

Complete the Common Education Loan Application Form — personal and academic bio-data, course and institution details, total cost of education, and collateral info if applicable. One form covers every bank you apply to. 

Search and Shortlist Schemes. 

The portal shows which banks match your course, institute ranking, and loan amount, along with their listed interest rates.

Apply to up to 3 banks

Submit the same CELAF to up to three participating banks simultaneously. Each bank evaluates independently and responds through the portal.

Upload documents 

KYC, admission letter, fee structure/cost estimate, income proof, academic records, and collateral documents (if the loan amount requires security) go up here. Track status in real time — sanctioned, under review, or query raised.

Respond to Bank Queries 

Follow-up document requests, or interview calls show up directly on the dashboard if they ask for additional paperwork. Approval typically runs 15–30 working days depending on profile and paperwork. 

Sanction and Disbursement 

Loans are usually released in tranches per academic year — the first installment around admission time, the rest against fee receipts and progress certificates. Most banks send the amount as a demand draft or transfer straight to the institute, not to you.

Public sector banks typically take 15–25 days to sanction; NBFCs like Credila can do it in 7–14 days, which matters if your visa or admission deadline is tight.

Important Documents You Must Have For Education Loan

  • Admission letter with fee structure, 
  • 10th/12th mark sheets and entrance scorecard (JEE, NEET, CAT, GRE, whatever applies), 
  • Aadhaar and PAN, 
  • Co-applicant’s income proof (last two years’ ITR and Form 16, or salary slips), 
  • Last six months’ bank statements, 
  • Passport-size photos, 
  • Collateral documents if your loan amount needs security. 

Missing or blurry documents are the single biggest reason applications sit in “query raised” status for weeks.

Read More 👉 Business Ideas for Students With Zero Investment — Easy Startup Guide

How Much You Have To Repay in Education Loan Online

Headline rates change with every RBI repo revision, so treat these as indicative starting points as of mid-2026, not fixed numbers — confirm the current rate directly with the lender before you sign anything.

LenderIndicative rate (p.a.)Notes
SBI Scholar Loan (IIT/IIM/ISB/select institutes)6.90% – 7.65%Lowest rates available, but restricted to a specific institute list
SBI Global Ed-Vantage (study abroad)From ~9.15%Flat ₹10,000 processing fee, needs 15% margin money above ₹4 lakh
PNB8.55% – 11.95%Up to ₹20 lakh without collateral for eligible courses
Canara Bank9.25% – 11.95%Strong presence in South India
HDFC Bank9.50% – 13.50%Faster processing than most PSU banks
Axis Bank9.50% – 13.50%Similar positioning to HDFC
ICICI Bank10.50% – 13.50%Higher end of private-bank rates
HDFC Credila (NBFC)~9.75% secured / ~10.25%+ unsecured100% financing possible, sanction in days, but processing fee is 1–1.25% + GST
Avanse / Propelld (NBFC)~10% – 13.5%Collateral-free options up to ₹60–75 lakh, merit-based pricing

The gap between a PSU bank’s lowest rate and an NBFC’s unsecured rate can run 3–4 percentage points. On a ₹15 lakh loan over 10 years, that difference alone adds up to several lakh rupees in extra interest — it’s worth the extra week of paperwork to get a PSU sanction if your timeline allows it.

The Subsidy Most Students Never Check For

Two separate government schemes can cut your effective rate, and they’re easy to confuse:

PM-Vidyalakshmi interest subvention (launched November 2024) gives a 3% interest subvention on loans up to ₹10 lakh, during the study period and moratorium, if your family income is up to ₹8 lakh a year. It only applies if you’re admitted to a Quality Higher Education Institution — over 860 of them qualify, including all IITs, NITs, and IIMs, plus state institutions ranked 101–200 in the NIRF list. There’s also a 75% government credit guarantee on loans up to ₹7.5 lakh, which is why some banks will sanction you without asking for collateral or a guarantor.

Central Sector Interest Subsidy (CSIS) is the older scheme — it covers the full interest during moratorium, but only for families earning up to ₹4.5 lakh a year and only at a separate, narrower list of premier institutions. You can’t claim both on the same loan, so check which one your institute and income bracket actually qualify for before assuming you get nothing.

Apply for whichever subvention you’re eligible for through the same portal — it isn’t automatic.

What Happens Once You Start Your Repayment

Once repayment starts, the interest you pay (not the principal) is fully deductible under Section 80E of the Income Tax Act — no upper limit on the amount. The deduction runs for 8 years from when you start repaying, or until the interest is fully paid off, whichever comes first. 

It applies to loans taken for your own, your spouse’s, or your children’s higher education, but only from a bank or a notified financial institution — a loan from a relative doesn’t qualify.

Read More 👉 How to Start a Mineral Water Business: Complete Guide

How You Can Save Real Money in Education Loan

  • Girl students get an automatic 0.5% rate concession at most public sector banks — ask for it explicitly if it isn’t applied.
  • Pay simple interest during the moratorium if you can manage it, even partially. Left unpaid, it often compounds once repayment begins, and on a ₹10 lakh loan that gap can run into a couple of lakh rupees by the time you graduate.
  • Compare processing fees, not just the headline rate. SBI charges a flat ₹10,000; NBFCs typically charge 1–1.75% of the loan plus GST, which is a meaningful amount on a ₹50 lakh loan.
  • Check margin money requirements. PSU banks generally need you to fund 15% of the cost yourself for loans above ₹4 lakh (domestic) or above a certain threshold for study abroad; several NBFCs offer 100% financing instead.
  • Ask about prepayment penalties before signing with an NBFC — some charge 1–3% if you close the loan early, which matters if your income grows faster than expected.

What If Your Study Loan Application Gets Stuck?

Most delays trace back to one of four things: 

Documents uploaded in the wrong format or half-legible, applying to a bank whose collateral rules don’t match the loan amount requested, assuming you qualify for a subsidy without checking the institute list first, and accepting the first offer instead of comparing at least two or three sanctioned terms side by side.

Register on the Vidya Lakshmi portal, shortlist one PSU bank and one NBFC so you have both a low-rate option and a fast-sanction backup, check which subsidy scheme your institute and income actually qualify for, and get your documents scanned before you start the form — not after a bank asks for them.

Conclusion

Understanding How to Apply for an Education Loan Online lets you avoid mistakes, get your documents ready at time, and not get your application stuck. If you want to pursue your education but can’t afford it, the study loan will help you achieve your dreams. Remember to check the bank’s interest and calculate the cost you have to pay later.

ITBP Head Constable Education & Stress Counsellor Recruitment 2026 Online Form For 16 Post

ITBP

Candidates with a Psychology degree or a B.Ed. have a golden chance to secure a stable and well-paying job right now. ITBP Head Constable (Education & Stress Counsellor) post application form is active until 27 October 2026. Apply early to hold your seat because the Indo-Tibetan Border Police Force announced only 16 available positions.

Everything about ITBP Head Constable from schedule to how to fill the form is given below. Read and check the official notification before applying for this post.

Overview of ITBP Head Constable Recruitment 2026

DetailInformation
PostHead Constable (Education & Stress Counsellor), Group C, Non-Gazetted
Vacancies16 (14 male, 2 female)
Notification date22 September 2026
Application window28 September to 27 October 2026
Advertisement No.CBC 19143/11/0011/2627
PayLevel 4, ₹25,500 to ₹81,100 (7th CPC)
Apply atrecruitment.itbpolice.nic.in

Don’t confuse this with the other ITBP Head Constable drive from the same month, for Motor Mechanic. That one is male-only and has 21 posts. Women can apply here, and that’s the main reason this notification is worth a closer look.

Who Can Apply for ITBP Head Constable (Education & Stress Counsellor)?

You need a bachelor’s degree with Psychology as a subject, or a bachelor’s degree plus a B.Ed. or Bachelor of Teaching. One is enough. A history graduate with a B.Ed. is eligible. A BA Psychology graduate can also apply without a teaching qualification. Final-year students don’t, because the degree must be completed by the closing date.

The age band is 20 to 25 years as on 27 October 2026. That is narrower than the usual 18 to 25 for ITBP constable posts. The relaxations up to 28 for OBC (non-creamy layer) and 30 for SC/ST candidates, with extra relaxation for ex-servicemen. Confirm your relaxation period in the official notification PDF.

The application fee is reported as ₹100 for male General, OBC and EWS applicants, with women, SC/ST candidates and ex-servicemen exempt. 

ITBP Head Constable Vacancy 2026

Fourteen seats are for men and two for women. Beyond that, the category-wise split is unclear. The two women’s seats make that category the tightest on a per-seat basis. The pool of applicants is also smaller than for a general constable drive, since the role needs a specific degree. Smaller doesn’t mean easy, though. Sixteen seats is sixteen seats.

Apply Now 👉 Canara Bank Apprentice Recruitment 2026: 3,500 Seats, Online Form Closes 17 October

ITBP Head Constable Selection Process: Physical Tests Come First

The order is Physical Efficiency Test (PET), Physical Standard Test (PST), written examination, document verification, then a Detailed Medical Examination, with a Review Medical Examination available on appeal. Putting the physical stages before the written paper is the opposite of what many exam-takers expect. A candidate who scores well on psychology and fails the run is out.

PET Standards

CategoryRaceLong JumpHigh Jump
Male1.6 km in 7 minutes 30 seconds11 feet3.5 feet
Female800 metres in 4 minutes 45 seconds9 feet3 feet

Written Examination

This is a Computer-Based Mode exam with 100 objective questions and each mark carries one mark. There is no negative marking and you are given only two hours to complete it. The paper is prepared in bilingual language so it won’t be difficult to understand the question.

Qualifying this exam is important to go to the next stage of the selection process. ITBP prepares merit lists according to written examination scores.

Documents and Medical Test

At document verification, candidates must produce original certificates, including educational qualification proof—such as a recognised degree with Psychology, or a degree along with B.Ed./B.T.—along with matriculation, category and domicile documents where applicable.

The final stage is the DME, conducted under CAPF medical guidelines. Candidates found medically unfit may be considered for the RME, where applicable.

None of the later dates are out yet. PET/PST, the written exam, document verification and the medical will be announced separately on the ITBP portal. The exam pattern, number of questions and negative marking aren’t public either. 

ITBP Head Constable Salary

The selected candidates get a job and their starting salary at ITBP Head Constable is ₹25,500 and a ceiling of ₹81,100. It is disbursed under Pay Level 4 on the 7th CPC matrix. The allowances including Dearness, house, posting-based allowance are also added in the salary.

Postings can include border and high-altitude locations, which carry extra allowances. A newly appointed candidate at the starting basic pay of ₹25,500 will generally receive a monthly gross salary above the basic pay after allowances, while net pay depends on deductions 

How to Apply for ITBP Head Constable Education & Stress Counsellor 2026

  1. Open the official website of ITBP and register yourself first with the correct Email and Mobile number. Then login to fill the Head Constable (Education & Stress Counsellor) application form. 
  2. Fill the exact details asking in each box of application form, upload your documents along with your photo, sign, and pay the fee to process the application.
  3. Before submitting, review every detail carefully, because edits aren’t allowed afterwards. Download the confirmation page.
  4. Keep ready your 10th certificate (for date of birth), your degree marksheets, your Psychology proof or B.Ed. certificate, and your category certificate if you’re claiming reservation. 
  5. If you’re relying on an “equivalent” to a B.Ed., expect to produce an equivalence certificate at document verification.

One prep tip: start your running now, before you open any psychology notes. The PET comes first and failing it ends your application regardless of your marks.

👉 Gemini 4 Argon: How the New AI Model Can Help Students and Teachers

Conclusion

Apply if you meet either degree route and fall within the age band. The competition is thinner than for a mass constable drive, and Level 4 pay is secure central government pay. Skip it if your degree has neither Psychology nor a B.Ed., because document verification is where those applications end. 

If you’re a woman with a qualifying degree, apply early. Two seats won’t wait for the last week. Submit at least three days before 27 October so a portal crash doesn’t decide your future.

How to Apply for a Student Loan to Get a Higher Education & Make Career

Student Loan

How to apply for a Student Loan doesn’t come randomly in anyone’s mind. Getting into a good college is only half the battle. The other half starts the moment you realize a B.Tech at a decent private university now costs ₹8–15 lakh, an MBA at a tier-2 B-school can run past ₹12 lakh, and a master’s abroad easily crosses ₹40 lakh once you add living costs. 

If you don’t have that sort of money lying around, a Student Loan is the only realistic option — and how to get one usually determines how much of that money actually gets deposited into your account, and how much you end up overpaying in interest over the next 10 years. 

This guide walks through the process as it actually works in India in 2026, not the version that shows up in a bank’s marketing brochure.

How to Apply for a Student Loan Through the Vidya Lakshmi Portal

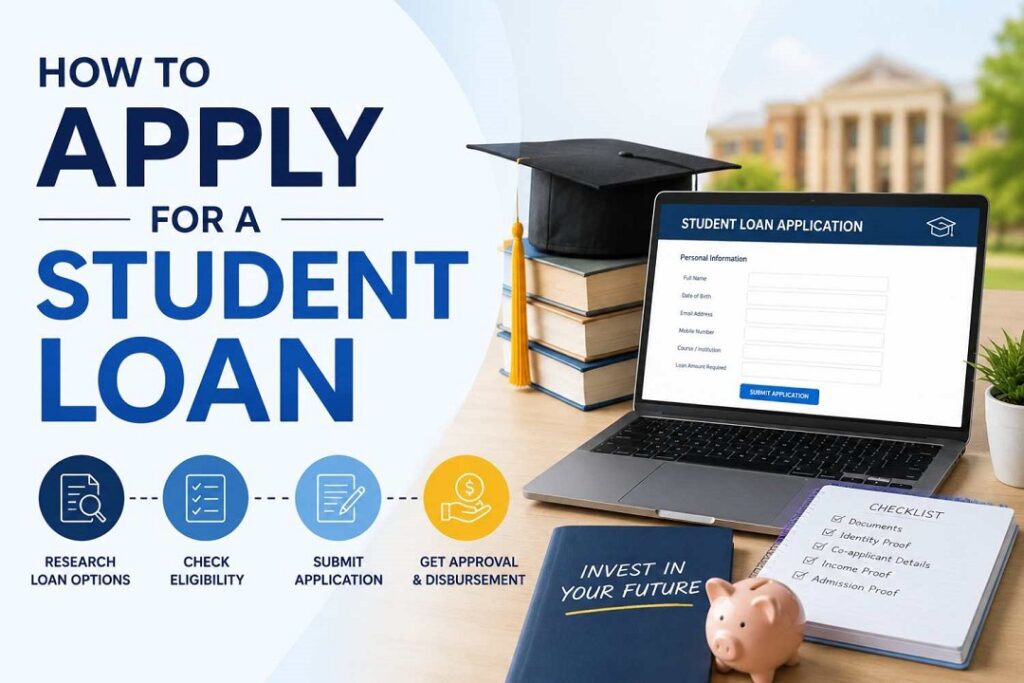
Almost every organized education loan in India now runs through the Vidya Lakshmi portal, a government-backed single window that connects more than three dozen banks and well over 100 loan schemes to one common form. Instead of visiting five bank branches and filling five different applications, you fill one — the Common Education Loan Application Form (CELAF), prescribed by the Indian Banks’ Association and accepted by every participating lender.

The process, in order:

  • Register on the portal with your email ID and a mobile number, ideally the one linked to your Aadhaar, since OTP verification runs through it.
  • Fill the CELAF in sections — personal details, course and institution details, cost breakdown, and your co-applicant’s financial information.
  • Upload KYC documents, academic transcripts, and your admission letter in the required digital format.
  • Use the “Search and Apply” tab to filter loan schemes by amount, interest rate, and whether you’re studying in India or abroad.
  • Shortlist and apply to a maximum of three banks in one go — a sensible mix is usually one public-sector bank (lower rate, slower processing) and one private bank or NBFC (faster, more flexible).
  • Track status from your dashboard. If a bank marks your application “on hold,” it means they want more documents — check the remarks column rather than waiting for an email.

The portal is also linked to the National Scholarship Portal, so if you qualify for a central or state scholarship, you can apply for it in the same sitting.

Where the PM Vidyalaxmi Scheme Fits In

Layered on top of Vidya Lakshmi since 2024–25 is the PM Vidyalaxmi Scheme, a Central Sector Scheme aimed specifically at students who’ve secured admission — through merit-based or open competitive selection — into a Quality Higher Education Institution (QHEI). The official list currently runs past 800 institutions and keeps expanding as new NIRF-ranked colleges get added, so don’t assume your college qualifies; check the current QHEI list on the portal before you plan around this scheme.

What it actually gets you:

  • No collateral, no guarantor for eligible loans. Some official sources describe this as applying to the entire loan regardless of amount; others cap the collateral-free portion at ₹7.5 lakh, after which the bank may ask for security on the balance. This detail genuinely varies by bank in practice — confirm it directly with your chosen lender before you apply, don’t assume either version.
  • A 75% government credit guarantee on loans up to ₹7.5 lakh, which is what makes banks comfortable lending without collateral in the first place.
  • Interest subvention during the moratorium period (course duration plus one year) — full interest subsidy if annual family income is up to ₹4.5 lakh, and a 3% subsidy if family income falls between ₹4.5 lakh and ₹8 lakh, both capped at loans up to ₹10 lakh.
  • Above ₹8 lakh family income, you still get the collateral-free structure and credit guarantee — you just pay the bank’s normal interest rate with no subsidy.

To claim the subvention, you submit an “intent” declaration on the portal along with income proof from an authorized state government authority — it isn’t automatic just because you’re eligible.

Eligibility Criteria You Need to Meet For Student Loan Across Indian Banks

Setting PM Vidyalaxmi aside, general education loan eligibility across Indian banks looks fairly consistent:

  • You need to be an Indian national with confirmed admission to a recognized, full-time regular course — part-time and distance programs are excluded by most lenders, though a few NBFCs make exceptions.
  • A co-applicant, almost always a parent or guardian, is required by nearly every bank once the loan crosses a modest threshold (often ₹4 lakh), and their income and credit history factor directly into how much you’re sanctioned.
  • For merit-based schemes like SBI’s Scholar Loan or PM Vidyalaxmi’s QHEI route, your entrance exam rank or admission channel matters as much as your family’s finances — these schemes exist precisely to reward the admission, not the collateral.
  • There’s no universal age cap, but banks do informally weigh whether you’re likely to complete the course and start repaying within a reasonable working-age window.

Documents to Keep Ready Before You Apply

Missing paperwork is the single most common reason applications sit in limbo for weeks. Have these ready before you start the CELAF, not after:

  • Admission letter and the institution’s official fee/cost structure
  • Mark sheets for 10th, 12th, and any prior degree
  • Identity proof — Aadhaar and PAN at minimum
  • Co-applicant’s income proof: recent salary slips or ITR, and the last six months of bank statements
  • Collateral documents, if your loan amount or scheme requires security
  • Passport and visa copy, if you’re studying abroad

Keep names spelled identically across every document — a mismatch between your Aadhaar and your admission letter is a small thing that causes real delays.

How Much Will It Cost You Across Every Sector Banks

Interest rates on Indian education loans in 2026 span a wide range depending on lender type:

  • Public-sector banks (SBI, PNB, Bank of Baroda, Union Bank, Canara Bank) generally price standard education loans between roughly 8% and 10.75% p.a., floating, tied to each bank’s repo-linked or external benchmark rate. As of mid-2026, the RBI repo rate itself sits around 6.25% — the actual benchmark moves at each monetary policy review, so treat any quoted rate as a starting point to verify, not a fixed number.
  • SBI’s Scholar Loan, reserved for students admitted to premier institutes like IITs, IIMs, and NITs, runs noticeably lower — roughly 6.9% to 7.65% p.a. — compared to its regular Student Loan Scheme at around 9.4% to 9.9%.
  • Private banks and NBFCs (HDFC Credila, Avanse, and similar) typically charge 9.5% to 16% p.a. Rates are higher, but sanction and disbursal are usually faster, and many offer larger unsecured amounts.
  • Most public banks give a 0.5% interest concession to girl students — worth asking about explicitly, since it isn’t always advertised upfront.
  • Several lenders, including SBI and PNB, offer a 0.5–1% rate discount if you pay simple interest during the moratorium period instead of letting it accumulate. Skipping this is the single most expensive mistake students make: unpaid interest during your study years gets added to the principal, so your EMI ends up calculated on a bigger loan than you actually borrowed.

Claiming the Section 80E Tax Benefit Once You Start Repaying

Once repayment begins, Section 80E of the Income Tax Act lets you deduct the entire interest component of your EMI from taxable income — not the principal, just the interest, but with no upper cap, which is unusual among Indian tax deductions.

A few conditions determine whether you actually qualify:

  • The deduction is available for a maximum of eight consecutive years, starting from the year you begin paying interest, or until the interest is fully repaid, whichever comes first.
  • It only applies if you’ve opted for the old tax regime — under the new regime, this deduction isn’t available at all, so run the comparison before you file.
  • The loan must come from a recognized bank, financial institution, or an approved charitable institution. A loan from an employer, a relative, or an informal lender does not qualify, no matter how similar the repayment terms look.
  • You can claim it for a loan taken for yourself, your spouse, your children, or a legal ward — and it applies whether the course was pursued in India or abroad.
  • You’ll need an interest certificate from your lender each financial year, clearly splitting principal from interest, to actually file the claim.

How To Avoid Application Rejection

A few patterns show up again and again in rejected or delayed applications: 

  • Applying to just one bank instead of shortlisting two or three through Vidya Lakshmi and comparing offers side by side
  • Assuming your college is on the PM Vidyalaxmi QHEI list without checking the current portal listing
  • Letting moratorium interest pile up instead of paying it as simple interest each quarter
  • Submitting documents where your name, date of birth, or address doesn’t match exactly across your Aadhaar, admission letter, and bank KYC. 

Each of these is fixable in an afternoon but only if you catch it before submission, not after a bank has already put your file on hold.

Select the Reliable Option for Student Loan

If you’ve been admitted to a QHEI on the current PM Vidyalaxmi list and your family’s annual income is under ₹8 lakh, start there through the Vidya Lakshmi portal — the interest subvention alone can save you lakhs over the loan’s life, and it’s the closest thing to free money in this entire process. 

If your institution isn’t on that list, or your loan requirement crosses ₹10 lakh, shortlist two or three public-sector banks, compare their post-moratorium rates head-to-head, and ask each one directly what your EMI looks like once the subsidy or discount period ends. Not the headline interest rate but that one question is where most students get blindsided.

Conclusion 

The paperwork for Student Loan application is simpler once you have your documents in order, have compared lenders and know the government schemes that apply to you. Vidya Lakshmi portal provides students a one-stop shop to apply for education loans and also compare the loans, while PM Vidyalaxmi can help eligible students by lightening their financial load through interest support and collateral-free loans. 

Before you accept any offer, look beyond the stated interest rate. Check the terms of the moratorium (temporary period in which you don’t have to start paying the regular EMI), your eligibility for subsidy, the amount you need to repay, the amount of collateral required and the total interest you will pay. A bit of comparison before signing can make a big difference to your finances after you graduate.

How to Crack UPPSC RO/ARO Without Coaching  

Crack UPPSC RO/ARO Without Coaching

Every year, lakhs of students in Uttar Pradesh start their RO/ARO preparation the same way — by joining a coaching institute the moment they decide to attempt the exam. It feels like the safe choice. Everyone around you is doing it, the institutes promise structured guidance, and the fear of “missing something important” pushes you toward enrolling even before you’ve opened a single book on your own.

I can’t speak for your specific goals, but what a lot of successful RO/ARO candidates will tell you once they’ve actually passed the test is: coaching never made the difference. What mattered was whether they understood the exam, built a routine around it, and stayed consistent long enough to see results. 

If you fall into the category of not being able to afford coaching or if you’re just an individual who likes to learn on his own terms, there’s no issue in attempting RO/ARO exams. You can start your preparations by yourself with the right guide. Proper syllabus, exam pattern, right schedule, responsibility are the core steps to take to prepare for the exam.

1. Understand Exam Pattern to Make the Right Strategy

You probably saw or heard that self-study failed many students not because they lacked intelligence but because they didn’t understand the exam’s purpose and importance. There are stages in the exams to clear and each one requires a different kind of preparation.

  1. UPPSC RO/ARO has a Preliminary exam to check how well you know General Studies and General Hindi and it rewards speed and accuracy over depth. 
  2. The Mains, on the other hand, wants you to write with clarity and present arguments, not just recall facts. 
  3. And the Typing Test, ignored by most aspirants until the last month, has quietly ended the dreams of candidates who cleared both written exams but never practiced typing seriously.

Before you buy a single book, spend two or three days just going through the official syllabus and the last five years of question papers. You’ll notice patterns almost immediately — certain topics from Indian History, Indian Polity, and UP-specific General Knowledge repeat in some form every year. This is the kind of pattern-recognition that coaching institutes charge lakhs to hand you on a platter. You can get there yourself with a notebook and some patience.

2. Build a Study Routine That Doesn’t Depend on Motivation

Coaching institutes work partly because they impose a schedule on you — classes at fixed times force a kind of discipline that self-study doesn’t naturally have. When you’re preparing alone, motivation runs out fast, usually within the first three weeks. What replaces it is routine.

Pick a time of day when your mind is sharpest — for most people, that’s early morning — and treat that slot as non-negotiable, exam day or not. Break up your week so that you have each subject in a chunk of the day, instead of bouncing around among all of them every day. A general division that helps for RO/ARO is General Studies in the morning, Hindi grammar and comprehension in the afternoon, and revision and mock tests in the evening. The exact hours matter less than the consistency of showing up.

What trips up most self-study candidates isn’t laziness — it’s the absence of a feedback loop. In a coaching class, a teacher tells you when you’re falling behind. Alone, you have to build that feedback into your own routine. Keep a simple tracker, even a basic notebook works, where you log what you studied and how confident you feel about it. Revisit that tracker every Sunday and be honest about the gaps.

Read More 👉 Data Science vs AI: Which Career Is Better?  

3. Choose the Right Books Instead of Too Many Books

One of the biggest traps for self-study aspirants is book overload. When you ask about which books toppers used, they might give you different answers. But each one of them has the topics which are frequently asked in the previous question papers. So, choose the book which you can understand when you read. Stick to that particular book per subject rather than jumping between multiple books hoping one of them “clicks.”

For General Studies, a common NCERT-based core syllabus in History, Geography, Polity and Economy is a much better option than jumping straight into exam-specific guides. Once your basics are solid, move to a UP-specific General Knowledge book, since a noticeable chunk of the RO/ARO paper focuses on state-level facts that national-level books simply don’t cover. For Hindi, focus heavily on grammar rules and previous year papers rather than generic Hindi literature books — the exam tests application, not literary depth.

Newspapers are non-negotiable, but read them with intent. Don’t read every article; scan for anything related to government schemes, UP-specific developments, and national events with policy implications. Ten focused minutes with a newspaper beats an hour of aimless reading.

4. Practice Like the Exam Is Already Tomorrow

Self-study candidates often make the mistake of treating mock tests as an afterthought — something to do once the syllabus is “finished.” In reality, mock tests should start early, even when you know only half the syllabus. Testing yourself regularly does two things coaching classes usually do for you: 

  • It shows you where your weak areas actually are 
  • And it trains your brain to work under time pressure

Solve at least one previous year’s paper or a full-length mock every week, and don’t just check your score — go through every wrong answer and understand why you got it wrong. Was it a factual gap, a silly mistake, or a comprehension issue? Each of these needs a different fix, and lumping them together as “I need to study more” won’t get you anywhere.

The typing test deserves its own separate practice schedule starting at least two months before your written exams are clear, not after. Waiting until results are declared to start practicing typing is one of the most common and avoidable mistakes RO/ARO aspirants make.

5. Find Your Community, Even Without a Classroom

The one genuine advantage of coaching is the peer group — people preparing for the same exam, sharing doubts, comparing notes, and keeping each other accountable. You can recreate this without paying for it. Online communities of RO/ARO aspirants, study groups on messaging apps, and even a couple of serious friends preparing for the same exam can replace this function almost entirely.

Use these groups to clarify doubts, share useful resources, and occasionally test each other. Just be careful they don’t turn into distraction hubs — the goal is accountability, not endless discussion about strategy that never converts into actual studying.

Read More 👉 Top 10 Mistakes to Avoid While Preparing for UPPSC RO/ARO

The Real Difference Between Coached and Self-Taught Candidates

Coaching gives structure to people who can’t build it themselves. If you can build that structure on your own — a study routine, the right books, regular self-testing, and a support system for accountability then there’s genuinely nothing coaching offers that you can’t replicate. 

What ends up separating candidates who clear RO/ARO from those who don’t isn’t whether they paid for classes. It’s whether they stayed consistent long enough, tested themselves honestly, and treated every mock test result as information rather than judgment.

Self-study for RO/ARO isn’t the harder path. It’s simply the path that asks more of your discipline instead of your wallet — and for a lot of aspirants across UP, that trade has worked out just fine.

Conclusion — How to Crack UPPSC RO/ARO Without Coaching

Clearing the UPPSC RO/ARO exam without coaching is entirely achievable if you get started with the right attitude and strategy. The course, past year papers, textbooks, sample tests, and current affairs are all available online nowadays. Because in the end, your success is going to be determined by the work that you do every day, not by how much money you spend on prep. The real challenge isn’t finding resources—it’s using them consistently.

Best Government Jobs in Haryana in 2025

If you are looking for Haryana government jobs in 2025, then you have a lot of great options. Every year the Haryana government recruits many posts in different departments, in which the youth get good salary, secure future and respectable life.

Whether you are 10th pass, 12th pass or graduate – government jobs are available in Haryana according to every qualification. The special thing is that here recruitments are done on many popular posts in police, education, electricity, health, and administrative departments.

Below we have brought you a list of Best Government Jobs in Haryana in 2025, which gives information about the top 15 jobs. This table gives complete information about the name of the job, department, qualification and official website.

S.No.Job TitleDepartment/OrganizationEligibilityOfficial Website
1Haryana Civil Services (HCS)Haryana Public Service Commission (HPSC)Graduation in any disciplinehpsc.gov.in
2Sub-InspectorHaryana PoliceGraduation + HSSC/SSC SI Examharyanapolice.gov.in
3Junior Engineer (JE)Haryana Power Utilities / HSSCDiploma/Degree in Engineeringhssc.gov.in
4PatwariDepartment of Land Records, HaryanaGraduation + Patwari traininghssc.gov.in
5PGT TeacherHaryana Education DepartmentPost-Graduation + B.Ed + HTETharyanatet.in
6ClerkHaryana Staff Selection Commission (HSSC)12th/Graduation + Typinghssc.gov.in
7ConstableHaryana Police12th Pass + Physical Testharyanapolice.gov.in
8Assistant LinemanHaryana Power UtilitiesITI in Electrician/Wiremanhpsc.gov.in
9Staff NurseHealth Department, HaryanaB.Sc Nursing/GNMnhmharyana.gov.in
10Veterinary SurgeonAnimal Husbandry & Dairying Department, HaryanaB.V.Sc & AH + Registration with VCIpashudhanharyana.gov.in
11Forest GuardHaryana Forest Department12th Pass + Physical Testhssc.gov.in
12Canal PatwariIrrigation & Water Resources Department12th Pass + Canal Patwari Certificatehid.gov.in
13Gram SachivPanchayat Department, HaryanaGraduation in any streamhssc.gov.in
14AuditorFinance Department, HaryanaB.Com/M.Comhssc.gov.in
15Assistant ProfessorHigher Education Department, HaryanaPost-Graduation + UGC NEThpsc.gov.in

Scroll to Top