Banking Job vs SSC Job: Details On The Top Government Jobs 

Bank job vs SSC job

Between Bank job vs SSC job which one to choose, this is the real matter of dilemma for all the Government Job aspirants in India. The two career paths are stable, respected, and come with good perks—but that’s about where the similarity ends. Work culture, salary structure, growth, work life balance, everything, Banking jobs and SSC jobs are quite different and these differences can have a telling impact on your lifestyle and long term goals. It is necessary to know about these differences, before you active your years of preparation in for either path.  

Work Culture of Banking Job vs SSC Job 

If you live for adrenaline and aren’t afraid of a high velocity environment, banking may be for you. As a Probationary Officer (PO) or a Clerk, you are the face of the bank. You’ll be handling customers, you’ll be handling cash flows, you’ll be giving and clearing loans. 

New challenges and new people every day. However, let’s not sugarcoat it — it’s a high-stress job in banking. The stereotypical “9-to-5” government job doesn’t really exist here anymore. Now there are targets including loan targets, account opening targets, insurance cross-selling. And you will be responsible for branch performance. 

SSC, on the other hand, is the very embodiment of bureaucracy. If you clear SSC CGL, you get very lucrative posts in central ministries, the CBI, Income Tax or Customs. 

This place has a very different culture of working. It is predominantly administrative. You are part of the massive machinery that runs the country. You will be drafting policies, keeping records, or maybe even conducting field inspections if you pick an Inspector profile. It’s more even-tempered, the deadlines aren’t as crazy, and you almost never have to field irate customers hollering about a failed UPI transaction. 

Salary And Allowances For Bank job vs SSC job

Both Bank job vs SSC job offer good salary and allowances to their employees in the government sector but a small difference is the right perks with right duty is a great combo.

Right from the beginning, a Bank PO generally earns more than a starting SSC CGL officer, more so if you get into SBI. The allowance is fantastic. You get lease accommodation (which is huge in metro cities), medical benefits, petrol allowances and even newspaper allowances.

Bank Employee Salary

Government BanksMonthly Salary
Probationary Officer (PO) ₹52,000 to ₹60,000 
₹30,000 (Perks)
Clerk ₹30,000 and ₹35,000 
Specialist Officer (SO) ₹52,000 to ₹58,000 

But the single biggest perk of being a banker? If you’re buying a house, a car, or paying for an education, you get loans at wildly subsidized interest rates. Over the course of a lifetime, that’s lakhs of rupees you save. 

The SSC salary is decent and the deciding factor for that matter is the Central pay commission only. Though the starting salary you take home may be a little lesser compared to a Bank PO, the perks are out of the world.

SSC CGL Salary 

Pay LevelEntry Basic PayTypical PostsApprox. In-Hand (Metro)
Level 8₹47,600Assistant Audit/Accounts Officer₹75,000 – ₹85,000
Level 7₹44,900ASO, Income Tax Inspector, Excise Inspector₹65,000 – ₹72,000
Level 6₹35,400Divisional Accountant, Sub-Inspector (NIA)₹52,000 – ₹58,000
Level 5₹29,200Auditor, Accountant₹42,000 – ₹48,000
Level 4₹25,500Tax Assistant, UDC₹36,000 – ₹42,000

Then there is the Central Government Health Scheme (CGHS), which offers almost free medical treatment in premier private hospitals to you and your dependents. You get exact DA hikes, HRA, travel concessions(Domestic and International). Additionally, the salary structure in SSC rises exponentially with higher pay bands and ranks. 

SSC CHSL Salary 

PostPay LevelApprox. In-Hand Salary
LDC / JSALevel 2₹27,000 – ₹32,000
DEO (Grade A)Level 4₹37,000 – ₹42,000
DEO (Level 5)Level 5₹40,000+

Work-Life Balance and Peace of Mind

This is where the divergence between the Bank job vs SSC job paths becomes painfully obvious.

In banking, it’s easy to feel like work-life balance is a myth, particularly in your first few years as a PO. You could be clocking out of your branch at 7 or 8 PM on busy days. And then there is the fact that bank jobs mean you get shifted around frequently. You will be shifting base and moving to a new city, at times to a rural village, for your mandatory rural posting every three to five years. 

SSC wins the work-life balance debate of Bank job vs SSC job, hands down. The majority of jobs in ministries are Monday to Friday and you have full, undisturbed weekends. You are out of the office at 5:30 p.m., and the work stays in the office. There are transfers, of course, in SSC, but not anything like in banking, and many secretariat posts can see you through an entire career in Delhi. 

Career Growth 

Bank job vs SSC job have good growth options as the field is huge and it has senior posts as well.

If you want to become a general manager before you get old, go for banking. The pace of promotion in public sector banks is quick and depends on merit to a great extent. Do well, clear your internal JAIIB/CAIIB exams and opt for tough postings, and you can scale the ladders really fast. The Chairman of SBI usually begins their journey as a normal Probationary Officer. 

Probationary Officer (Scale I) → Assistant Manager

Scale II (Manager) — usually 2–3 years

Scale III (Senior Manager) — 5–7 years

Scale IV (Chief Manager)

Scale V–VII (AGM, DGM, GM)

Advancement in SSC is generally end of term and largely seniority based with the number of vacancies available. It’s a slow burn. You can come in as an ASO (Assistant Section Officer) and retire as a Joint Secretary after 30 years. It’s a respectable place to be and you know you’re never going to be laid off, but don’t expect to be leapfrogging up the ladder because you worked extra-hard one year. 

Inspector (Level 7)

Superintendent/ITO (Level 8) — 5–8 years

Assistant Commissioner (Level 10) — 12–15 years

Deputy/Joint Commissioner (Level 11–13) — 18–25 years

Eligibility of Public Sector Banks And SSC Jobs 

Nationality: Citizen of India 

Educational Qualification for Public Sector Banks : A Bachelor’s Degree for any bank post, for clerk post, you must hold a Computer certificate. 

Age Required : 20 years is minimum and maximum is based on the role, for PO, it is 30 years. And for Clerk, it is a 28 years limitation. Now, you have given a chance to work for more years if you belong any of the categories: 

SC/ST: 5 years.

OBC (Non-Creamy Layer): 3 years.

PwBD: 10 years.

Educational Qualification for SSC Jobs : In SSC CGL, candidates are required to have any degree, but for Junior Statistical Officer roles required Math in 12th and Statistics in graduation as a subject.

Age required : 18 to 32 years.

Meanwhile, SSC CHSL candidates required 12th class marksheet, but Data Entry Operator role requires Science stream with Mathematics. 

18 to 27 years is an age criteria for most posts. 

So, every position needs some additional skills, it’s better to check official notification for eligibility in specific posts. 

Skills You Need For These Jobs

Both Bank job vs SSC job need particular skills for the job responsibilities to ensure a smooth workflow.

All of these are about speed and accuracy. The questions aren’t necessarily absurdly difficult, but you only have a few seconds to answer each one. It involves a lot of calculation and data interpretation, some reading comprehension and complex seating arrangement. If you have quick reflexes and don’t mind a ticking clock, bank exams are definitely for you. 

SSC tests your depth of knowledge. Time is a factor, not nearly as brutal as in banking. Here you have to know high-level maths (trigonometry, geometry, algebra), English grammar rules by heart and a ton of Static GK and Current Affairs. If you enjoy memorising a lot and love researching topics, SSC is your playground. 

Read More:- Junior Hindi Translator Recruitment: Exam Pattern, Eligibility, And Salary Details

Conclusion

So, there is no one answer to which one is right for you between Bank job vs SSC job. If you like to work in a dynamic environment, and take pressure with great pay then banking is for you. But if you like to work in a stable environment with predictable timings and want to have a balanced life with job security, SSC jobs surprisingly are best. 

Ultimately, the one you should go between Bank job vs SSC job depends on your own personality, priorities and future plans for your career – so you take a little time to think about what’s most important to you, and then make an informed decision.
Leave a Comment

Your email address will not be published. Required fields are marked *

Best App To Get Instant Loan Without Salary Slip 

Best App To Get Instant Loan Without Salary Slip

Your landlord isn’t waiting, the hospital isn’t waiting, and your bank’s personal loan officer just told you to come back “once you have three months of payslips.” That forces you to google for the Best App To Get Instant Loan Without Salary Slip because you need ₹20,000 urgently. Because there is no payslip coming from a freelancer, or small start ups owner.

This is the exact gap that a new generation of lending apps was built to close. Instead of a salary slip, they read your bank statements, your PAN and Aadhaar history, your UPI transaction pattern, and sometimes your GST filings, and turn that into a credit decision in minutes. 

However, “no salary slip” doesn’t mean “no scrutiny” and it definitely doesn’t mean every app claiming this is safe to use. Below are the Best App To Get Instant Loan Without Salary Slip, let’s see what they actually cost, and how to tell a legitimate lender from a data-harvesting clone before you hand over your Aadhaar.

Why Salary Slips Stopped Being the Only Option

Banks built their lending rules around one kind of borrower: someone with a fixed monthly salary landing on the same date, from the same employer, verifiable on a letterhead. That description fits a shrinking share of India’s workforce. Freelancers, gig-platform workers, small traders, and contract staff earn real, trackable income — it just doesn’t arrive in payslip form.

Digital lenders solved this by switching the input. Instead of a payslip, they pull 3–12 months of bank statements to see how much money moves through your account and how consistently. Self-employed applicants can usually substitute ITR filings, GST returns, or business account statements. 

Some apps go further and factor in your digital footprint — how long you’ve held your phone number, your UPI activity, even your app usage patterns to build a risk score. None of this is charity; it’s just a different, faster underwriting model, and it’s why approval on these apps can take minutes instead of the two-week wait typical of a bank.

Skipping The Salary Slip Doesn’t Mean The Requirement of Documents Ends

Skipping the salary slip doesn’t mean skipping documentation — it just shifts what counts as proof. Across the apps below, the standard ask is a PAN card, Aadhaar for e-KYC, and 3–6 months of bank statements showing regular inflows. 

Self-employed applicants typically add one of: ITR filings for the last one or two years, GST returns if registered, or a business current-account statement. A few apps, like Fibe and mPokket, lean more heavily on alternative signals — how long you’ve had your phone number, your UPI transaction frequency, even basic device data — specifically for applicants who have no ITR or GST paperwork to show at all. 

None of this is optional paperwork replaced by “trust us” — every legitimate lender still needs some way to estimate whether you can repay, it’s just reading your cash flow instead of your employer’s letterhead.

Best Instant Loan Apps Without a Salary Slip Are Listed

1. KreditBee — Best for Small, Fast Loans With No CIBIL History

KreditBee lends through Krazybee Services, an RBI-registered NBFC, and is built for speed on smaller ticket sizes. Loan amounts run from about ₹5,000 up to ₹10 lakh, with tenures between 3 and 60 months. 

Interest rates officially start at 12% p.a., but that floor is reserved for the strongest profiles — most first-time or thin-file borrowers land closer to 24–29.95% p.a., and self-employed applicants specifically are often quoted in the 16–29.95% range. 

Processing fees can run up to roughly 4–5% of the loan amount, deducted upfront from disbursal. The minimum income requirement is just ₹10,000 a month, and a CIBIL score isn’t mandatory. 

Best for: someone who needs ₹10,000–₹50,000 fast and doesn’t have a credit history yet — not for large-ticket borrowing, since the cost climbs fast at that end.

2. Navi — Best for Lower Rates and Larger Loan Amounts

Navi, backed by Navi Finserv, is an app to check if your credit score is solid and you need more money for longer. Loan amounts stretch from around ₹10,000 to ₹20 lakh (some listings show up to ₹10 lakh depending on the product), with tenures up to 84 months. 

Rates start near 9.9–9.99% p.a. for borrowers with a CIBIL score of 700+, but can rise to 29–45% p.a. for weaker profiles — a wider spread than most competitors, so the advertised low rate isn’t guaranteed. 

Processing fees range from 0% to about 4% plus GST. Both salaried and self-employed applicants are eligible with a minimum score of roughly 650. 

Best for: self-employed borrowers with a decent credit file who want a bigger loan without a bank’s paperwork.

3. Fibe (formerly EarlySalary) — Best for Speed

Fibe is an RBI-registered NBFC-P2P platform (license N-13.02139) built around a two-minute approval promise, using an AI model that scans over 100 data points instead of a payslip. Loan amounts go up to ₹5 lakh, rates start at 12% p.a., and it’s known for letting borrowers with no CIBIL score qualify by leaning on digital and social-footprint signals instead. It’s particularly active in Tier-2 and Tier-3 cities where bank branches and traditional documentation checks are less accessible. 

Best for: first-time borrowers who need money today and can accept a higher rate in exchange for near-instant disbursal.

4. PaySense — Best for Consistent Self-Employed Income

PaySense, run on PayU Finance India’s lending infrastructure, uses risk-based pricing rather than one flat rate, so two applicants for the same amount can get different offers. Published eligibility asks for a minimum monthly income of ₹18,000 for salaried applicants and ₹20,000 for self-employed ones, with interest rates typically quoted between 14% and 36% p.a. depending on profile. It accepts a low or even zero CIBIL score, which makes it accessible, but that flexibility shows up in the rate you’re offered. 

PaySense is the Best App To Get Instant Loan Without Salary Slip for self-employed borrowers with steady, provable cash flow who don’t yet have a strong credit file.

5. MoneyView — Best for Tier-2/Tier-3 Self-Employed Borrowers

MoneyView is frequently the first recommendation for salaried applicants outside metro cities and for self-employed or gig workers who want minimal paperwork. It’s positioned between the small-ticket apps and the larger NBFC lenders, with loan amounts up to around ₹10 lakh and rates generally in the low-to-mid double digits for stronger profiles, rising for thinner files — broadly comparable to KreditBee’s range, though it’s often described as steadier on collection practices in user reviews. 

Best for: borrowers outside major metros who want a mid-sized loan without a Tier-1-city credit profile.

6. mPokket — Best for Students and Thin-File Gig Workers

mPokket is built specifically for people the traditional system ignores entirely — students and gig workers with little or no credit history. Loan sizes are smaller than the others on this list, aimed at short-term, small-amount needs like covering a bill or a temporary cash gap rather than a big-ticket expense. It shouldn’t be treated as a recurring source of funds — the sizes and terms make it best suited to occasional, short-duration borrowing. 

Best for: students or new-to-credit gig workers who need a small amount and have nowhere else to turn.

Read More 👉 How to Start a Mineral Water Business: Complete Guide

How To Get an Instant Personal Loan Through Paytm, PhonePe, GPay, and Bhim

The same apps you use to split a dinner bill or pay your electricity bill can also get you a loan — often within minutes. Here’s how each one actually works:

Paytm

Open the Paytm app, head to the “Loans & Credit Cards” section, and tap “Personal Loan.” Paytm lets you apply anytime for an instant loan online in about two minutes, with a fully digital process and loan amounts ranging from ₹5,000 to ₹15 lakh, flexible tenure, and the option to foreclose anytime. 

Paytm doesn’t lend the money itself — it partners with RBI-regulated NBFCs and banks who actually underwrite and disburse the loan. You’ll go through PAN and Aadhaar-based KYC either way.

PhonePe

Same idea, different app. PhonePe doesn’t hand out loans directly — it has partnered with various banks and NBFCs to offer instant loans, so you can apply without ever leaving the app.  Loan amounts go up to ₹5 lakh, repayable over tenures of up to 60 months, at rates starting around 13% per annum, with the approved amount transferred straight to your bank account.  Most lenders here look for a stable income and a credit score around 650 or higher.

Google Pay

Google Pay follows the same partner-lending model as Paytm and PhonePe — it doesn’t lend directly but connects you to its NBFC and bank partners for a pre-approved or application-based personal loan inside the app, with KYC handled digitally via Aadhaar and PAN.

BHIM

This one surprises people, since BHIM is best known as NPCI’s bare-bones UPI app. But it’s expanded: BHIM now lets you explore a personal loan without leaving the app, again through its network of lending partners rather than lending in-house.

How to Check an App Isn’t a Scam Before You Apply

RBI does not license individual apps — it regulates the bank or NBFC behind them. That distinction is the entire safety check:

  • Find the named NBFC or bank. A legitimate app discloses its lending partner clearly in the app, on the Play Store listing, or in the loan agreement. If you can’t find a specific company name, stop.
  • Verify that name on rbi.org.in or the RBI’s Digital Lending Apps directory before you submit any documents.
  • Never pay upfront. Processing fees, “insurance,” or “security deposits” requested before disbursal are the single most common fraud pattern. Legitimate lenders deduct fees from the loan amount after approval, not before.
  • Check what permissions it wants. A real KYC process needs your camera for a selfie and basic identity/banking access — not your full contact list, photo gallery, SMS logs, or call history. Apps that demand those are usually building leverage for harassment-based recovery later, not assessing creditworthiness.
  • Look for a Key Fact Statement (KFS). RBI’s digital lending rules require one before disbursal, listing the all-in APR, not just a headline interest rate. A “1% per month” rate can look harmless until the APR reveals fees stacked on top.
  • Confirm a named grievance officer with a phone number and email — not just a generic contact form.

If two or more of these are missing, treat the app as a red flag regardless of its Play Store rating, which is not proof of regulatory legitimacy. Because the best app to get instant loan doesn’t mean every app is trustworthy.

Advertising Rate Is Always Different From Actual Amount You Receive in Your Account

Headline interest rates on these apps are quoted per annum, but the real cost shows up in the APR, once processing fees and GST on those fees are added in. A concrete example: on a KreditBee loan disbursed at roughly ₹1 lakh, one published breakdown shows a ₹4,000 processing fee (4%), ₹720 GST on that fee, and ₹10 in documentation charges — pushing the effective APR to 29.66%, even though the headline rate for that borrower’s tier read lower. 

The amount that actually lands in the bank account was around ₹95,270, not the full ₹1 lakh. This is exactly what the Key Fact Statement is meant to expose, and it’s why comparing apps on their advertised “starting from” rate alone is close to useless — always ask for the APR and the net disbursal amount before accepting an offer, not just the interest rate.

Read More 👉 How to Apply for an Education Loan Online

Which App Should You Consider For Instant Personal Loan?

  • If you’re a gig worker or freelancer with no credit history and need a small amount fast, start with KreditBee or Fibe. 
  • If you’re self-employed with steady bank statements and want a lower rate on a bigger amount, check Navi or MoneyView first and let your CIBIL score decide between them. 
  • If you’re a student or new to credit entirely, mPokket is built for exactly that gap, but treat it as a short-term bridge, not a repeat solution. 

Conclusion

Whichever  Best App To Get Instant Loan Without Salary Slip you land on, run it through the RBI-verification checklist above before you type in your PAN — that two-minute check is what separates a fair loan from a very expensive mistake.

The absence of a salary slip requirement is a documentation shortcut, not a signal that the loan is free of risk. A ₹20,000 loan at 28% p.a. with a 4% upfront fee still needs to be repaid on schedule, and missed EMIs on these apps report to CIBIL just like a bank loan would. 

Borrow the amount you need for the problem in front of you, not the maximum the app is willing to approve — the higher your sanctioned limit looks, the more tempting it is to take more than the situation actually calls for.

Note: Rates, loan limits, and fees above reflect published figures as of mid-2026 and change frequently based on lender policy and individual credit profile — confirm current terms in-app before applying.

How to Crack State PSC Exams in First Attempt: Strategy & Resources

Govt. jobs are undoubtedly one of the most safe and respected career options in India and passing the State Public Service Commission (PSC) exam in first attempt is a dream for many aspirants. As the competition is rising and the syllabus is vast, it sometimes feels like a difficult mountain to scale. But, with the right approach, intelligent study techniques, and diligent efforts, passing the exam is not an impossible dream. The crux is to understand the syllabus in depth, follow the right resources and adhere to a disciplined schedule that would cover both prelims & mains preparation.

Quick Thoughts Gathering to Begin With

  1. Download official syllabus + all past papers of 8 years.
  2. Make a list of books you own/need (start with NCERTs).
  3. Select optional subject.
  4. Put together a weekly schedule you can live with.
  5. Create a one-pager daily current affairs file.
  6. Enroll in test series / good coaching (online/offline) and commit to weekly mocks.
  7. Start your NCERTs (goal: 2–3 chapters/day).

Big-picture study strategy (what to study & why)

Build bedrock knowledge first: NCERTs (6–12) for History, Geography, Economics, and Pol. These give a clean conceptual base.

Proceed to standard books for each subject (more below). Read for understanding, not rote.

Current affairs daily — newspaper + short notes. Link events to static syllabus.

Notes + revision cycle — Make short revision notes (1–2 pages) per topic; revise them frequently.

Practice smartly: MCQs for prelims + answer writing under time pressure for mains. Mains wins jobs — practice answer structure & linking facts to syllabus keywords.

Mocks & feedback: Do full length mocks and get answers evaluated (peer/mentor) and you improve your answer style and technique of scoring.

Recommended core resources (common, high-utility) 

(You will need to add in your state-specific books / local history that you must have from your state board / PSC Recommended Readings)

  1. Cover Basics 

NCERTs 6–12 — History, Geography, Pol. Science, Economics (start here).

Indian Polity — M. Laxmikanth (efficient + concise for governance & state-centred comparative questions).

Modern Indian History — Spectrum’s A Brief History of Modern India / Bipin Chandra (for depth).

Indian Economy — Ramesh Singh or any good concise economy book, supplemented with RBI / Economic Survey summaries.

Geography — Certificate Physical & Human Geography (G.C. Leong) or equivalent concise books.

Environment & Ecology — normal environment compendium/ class notes, track Recent Events.

State-specific history & polity — whatever books your PSC cites, in addition to local gazetteers and state government documents.

  1. Current affairs & general reading

One daily national newspaper (The Hindu / Indian Express) or their summaries. Government releases: Press Information Bureau (PIB), state government portals, official reports (for schemes and facts). Monthly magazines or current affairs compendiums (good for revision).

  1. Practice

Collection of previous years’ PSC papers (must have). A good questionbank or mock test series (free/paid) for practicing in time bound manner. Answer writing notebooks (keep one for mains answers). 

Sample schedules — choose according to the time you have

If you have 12 months

1st to 4th month: complete NCERTs + standard books for GS I–III fundamentals; decide optional & finish fundamentals.

Months 5 to 8: Complete other standard books + begin consolidating notes; begin on PYQs.

9th and 10th months: High-intensity test series – full-length prelim mock test every week; augments revision of weak topics.

Months 11–12: Final run through + daily PYQs + last-mile current affairs. Mains answer practice (if prelim cleared).

If you have 6 months

1st month: Preparation for NCERTs + syllabus mapping + optional selection.

2nd to 4th month: Read standard books, prepare short notes, solve MCQs and PYQs.

Month 5: Rigorous mock tests (prelim-benchmarked); Time management to be calibrated.

Month 6: Re-visit everything + frequent mock tests + current affairs wrap-up.

If you have three months

  • Fast NCERT reading + priority standard book chapters on some important subjects.
  • Study 7-10 hours a day: current affairs in the morning, theory in bulk in mid-day, MCQs + past papers in the evening.
  • Mocks repeatedly at intervals of 3-4 days Analyze each. 

Prelims strategy (objective test)

A good preparation strategy would be to start with the NCERTs along with one standard book per subject to establish a strong base. While learning content, same importance should be given to speed and accuracy by daily practicing MCQs gradually going to 500 – 1000 in a week. To gain maximum returns in minimum time, concentrate on high-yield topics such as Polity, the Constitution, Economy (primarily basic indices), Geography (with emphasis on map work), Environment, and Current Affairs. The Previous Year Questions (PYQs should be backbone of your preparation as it helps you to identify the areas/themes which the exam repeatedly tests). 

Also Read : Top 10 List of Exams Conducted by UPSC After Graduation in 2025

Mains strategy (subjective / descriptive)

Start writing answers from the early days of preparation, while upgrading yourself with the ability to write a good structured answer that has an introduction, a well-structured body (with headings or bullet points, if necessary) and a brief conclusion or way forward. Static knowledge and linking current affairs with theoretical knowledge need to be a part of answers as they give depth and relevance to answers. At the mid-stage of your preparation, doing a full answer paper every week – both essays and GS papers — is useful in developing regularity and you can increase the frequency as the exam comes closer. Regular assessment or peer review also is necessary, as it improves presentation as well as the density of content, leading to more effective answers. 

Interview / personality test

Prepare short biographical stories related to: accomplishments, academic projects, work experience and expertise in optional subjects. Stay informed on regional issues and national affairs. Conduct mock interviews with mentors or peers, concentrate on clear communication, serenity, and concise responses. 

Common Mistakes to Avoid

  • Learning everything superficially diminishes its utility; depth is much more valuable than breadth across different fields at surface level isn’t very rewarding.
  • Disregarding previous years’ papers is the biggest blunder as these papers bring out the themes that repeat, the patterns of questions and the areas to be concentrated.
  • Not timing yourself while you practise MCQs or while writing answers results in bad speed and poor accuracy in the exam.
  • Too many resources create noise and confusion, while focusing one’s attention on too few resources creates blind spots. A small set of high quality, reliable resources is the best bet for clarity and retention.
  • Avoiding regular revision destroys the power of retention; one should revise systematically and at frequenter intervals to be able to recite confidently and be assured of long term recall. 

Conclusion

How to Study Smart for First Attempt State PSC (Public Service Commission) Exam It is not about studying for countless hours, but it is about studying smart by keeping focus and being consistent. This trip requires a very clear mind, discipline, and a problem-solving attitude. Candidates with the right resources and guidance, along with consistent practice and revision, can not only cram for the exam but gain the confidence to ace at the Interview round. Wait for it… Success in the competitive exam is for those who start early, prepare strategically and have a firm belief till last that they will pass the exam. 

Collateral vs No Collateral Loan Amount Where Collateral Starts Making Financial Sense

Collateral vs No Collateral Loan

Ask most people whether a secured loan beats an unsecured one, and they’ll say yes without blinking — lower interest rate, obviously better. That’s the assumption. It’s also where the math quietly falls apart, because a lower rate on paper doesn’t always mean a lower cost in your pocket. Don’t get confused about Collateral vs No Collateral Loan, understand where it matters.

Whether collateral actually saves you money depends on how much you’re borrowing, and more specifically, on what kind of asset you’re pledging to get that lower rate.

This isn’t a “secured is always cheaper” point. It’s about the exact moment moves depending on the collateral where the interest-rate discount stops being eaten alive by fees, valuation costs, and paperwork.

What Changes When You Add Collateral to a Loan

A collateral loan amount decision comes down to three things shifting at once, not just the rate.

The interest rate drops, because the lender’s risk drops. If you default, they recover the loan by selling or auctioning the pledged asset. As of late 2026, unsecured personal loans in India typically run 11–18% per year for a reasonably qualified borrower, and unsecured business loans usually start closer to 16%. Gold loans from banks price between roughly 8.5% and 12%, and loans against property (LAP) generally fall between 8.5% and 14%, though NBFC gold loans for weaker profiles can climb well past 20%.

Fixed costs show up that don’t exist on an unsecured loan. Asset valuation, legal verification, mortgage registration, sometimes insurance on the pledged asset. These are flat charges — they don’t scale down for a small loan the way percentage-based interest does.

Your money moves slower, and your asset stops being liquid. A personal loan can land in your account same-day. A property-backed loan needs valuation, title checks, and registration, which can take one to three weeks. During that time, and for the life of the loan, that asset is off the table if you need to sell it, gift it, or use it as collateral again elsewhere.

That third point is the one people underweight, and it matters more as the loan amount grows, not less which is part of why there’s no single “collateral is worth it above this number” answer.

The Real Threshold Depends on Which Asset You’re Pledging

The breakeven point isn’t one number in Collateral vs No Collateral Loan. It’s a different number for every type of collateral, because the fixed costs attached to each one are wildly different.

Gold or fixed-deposit collateral has almost no fixed-cost floor. A gold loan can be sanctioned in under an hour, valuation is done on the spot, and processing fees run 0.25–1% of the loan amount — often just a few hundred rupees on a small ticket. Because there’s barely any fixed cost to clear, a gold loan can make financial sense on amounts as small as ₹50,000–₹1 lakh. The rate gap versus an unsecured loan (often 4–8 percentage points) starts saving you money almost immediately.

Property as collateral (LAP) is the opposite case. Valuation fees, legal verification, and mortgage registration or stamp duty typically add up to somewhere between ₹15,000 and ₹30,000, depending on the state and lender — and that’s before you factor in the two-to-three-week processing time. On a small loan, that fixed cost can wipe out most or all of the interest savings. LAP generally only starts making financial sense somewhere in the ₹5–8 lakh range, and it becomes clearly worthwhile above ₹10 lakh, where the fixed costs shrink to a rounding error against the total interest saved.

Vehicle or equipment-backed business loans sit in between — moderate valuation costs, faster processing than property, and a breakeven point that usually lands somewhere in the ₹2–4 lakh range.

A Quick Numbers Comparison 

Here’s a simplified comparison over a 3-year tenure, using a representative unsecured rate of 15–16% against a representative secured rate of 10% (gold loan) or 10% (LAP), before fixed costs:

Loan AmountInterest Paid Unsecured (~16%)Interest Paid Secured (~10%)Raw Interest SavedTypical LAP Fixed CostsNet Saving After Fixed Costs
₹1,00,000~₹25,000~₹16,000~₹9,000N/A (use gold loan, not LAP)Gold loan: still net positive
₹2,00,000~₹53,000~₹32,000~₹21,000~₹20,000Roughly breakeven
₹5,00,000~₹1,33,000~₹81,000~₹52,000~₹20,000~₹32,000 saved
₹15,00,000~₹3,98,000~₹2,42,000~₹1,56,000~₹25,000~₹1,31,000 saved

Note: these are illustrative figures based on representative rate bands, reducing-balance EMI math, and typical fee ranges reported by Indian lenders as of August 2026. 

The pattern holds regardless of the exact numbers: 

On a ₹1 lakh loan, a gold loan wins easily because there’s almost no fixed cost standing between you and the rate discount. On a ₹2 lakh loan taken as a property-backed loan specifically, the fixed costs and the interest savings roughly cancel out — which is exactly why lenders rarely push LAP that small in the first place. By ₹5 lakh and above, the fixed cost stops mattering and the rate gap does all the work.

When Collateral Still Doesn’t Make Sense, Even Above the Threshold

Crossing the breakeven number doesn’t automatically make collateral the right call. A few situations flip the decision back toward unsecured, even at a large loan amount and you started searching for  Collateral vs No Collateral Loan.

  • You need the money in days, not weeks. An unsecured personal loan can disburse within 24–48 hours. A property loan’s valuation and registration process can eat two to three weeks — a real cost if the need is urgent (medical, a time-bound business opportunity, an admission deadline).
  • The asset has a use you’d lose access to. Gold jewelry you might need to sell or gift, or a property you’re planning to sell within the loan tenure, becomes harder to move once it’s pledged. Foreclosure and part-release processes add time and fees of their own.
  • Your income is genuinely unstable. Secured loans still get called in on default — the lender auctions the asset. If repayment is uncertain, adding “losing the collateral” on top of “damaged credit score” is a worse outcome than an unsecured default alone, all else equal.
  • The rate gap has shrunk. RBI rate cuts through 2025 and 2026 have compressed the spread between top-tier unsecured personal loans (some starting near 10%) and secured options in certain cases. Always compare Collateral vs No Collateral Loan live quotes — a hypothetical rate gap on a post isn’t the rate you’ll actually be offered.

Which One Should You Pick Between Collateral vs No Collateral Loan?

Match the collateral type to the loan size, not the other way round:

  • Borrowing under ₹2 lakh and you own gold or have a fixed deposit sitting idle? Pledge it — the fixed-cost floor is low enough that it almost always wins over an unsecured loan.
  • Borrowing ₹2–5 lakh? Run the actual numbers from at least two lenders before deciding. This is the genuine grey zone where fees can cancel out the rate advantage.
  • Borrowing ₹5 lakh or more and you have a property or a high-value asset to pledge? Collateral almost always wins on cost, provided you can tolerate the slower disbursal and the asset being locked up for the tenure.
  • Need the money within a week, regardless of amount? Unsecured is usually the only realistic option, and the speed premium is worth paying for.

The rate on the sanction letter is only half the decision. The other half is whether your loan amount is big enough to make the fixed costs of pledging that asset disappear into the background — and that number changes depending on what you’re pledging, not just how much you’re borrowing.

Read More 👉 Your Credit Score Ignores 90% of Your Financial Life — What Your First Credit Card Changes 

Conclusion

Collateral doesn’t automatically make a loan cheaper if you understand at what point it financially makes sense then you won’t get confused ever. The loan amount, the asset you pledge, and the rate difference all have to work in your favour. 

Which kind of loan you are seeking is also a matter, Gold or FD-backed loans can make sense even at smaller amounts because their upfront costs are low, while other higher loans such as property-backed loans usually need a much larger ticket before the interest savings outweigh valuation, legal, and registration costs.

Collateral vs No Collateral Loan is not a big confusion, there is no universal ₹5 lakh or ₹10 lakh cutoff where collateral suddenly becomes worth it. So you must understand where your interest savings finally outweigh the real cost and inconvenience of pledging the asset. 

Top Government Jobs for Medical Students in 2025 You Shouldn’t Miss!

Top Government Jobs for Medical Students in 2025

Choosing a government job after a medical degree is a wise option for your career. Find top government jobs for medical students and stay updated on the recruitment notification. The competition is high, and it’s not easy to get a job in the medical field. The selection process might be difficult with a lot of competition but keep focus on preparation. With the right preparation, you can be a medical officer in defense or other public sectors.

Medical Officer

Becoming a Medical Officer is worth the MBBS degree. Many MBBS graduates prefer to become a Medical Officer in a government hospital rather than in any private hospital. The role requires the responsibility to provide healthcare services, manage the hospital, and treat patients.

Government hospitals recruit medical officers through examinations such as the State Public Service Commission, the Union Public Service Commission, and the National Health Missions.
This post allows you to diagnose patients, manage hospitals, and lead junior staff. Rural areas require such types of public services for health care.

Eligibility: You must have an MBBS degree and valid registration in any medical council.
Salary range: The starting salary is 50,000 and rises to 100,000/month. Government hospitals pay the doctors according to their experience and location.
Selection Process: The recruitment for this job starts with the written exam, and then the shortlisted candidates are called for an interview. After these processes, candidates will be selected for a medical officer position if they clear the interview.

Armed Forces Medical Services

If you want your future to be a little more adventurous, join the Armed Forces Medical Services. It provides medical services to the Army, Navy, and Air Force medical units to heal them during national emergencies. If you are physically and medically fit then this post is a good match for you. It’s a respectable post and has a great pay-scale. After clearing the examination, you will be called for an interview and then a medical examination. You must meet the medical standards of this position even if you passed all the stages.

Eligibility: MBBS graduate and valid certification from MCI.
Salary range: Medical officers in the army have starting salaries of 75,000, plus additional benefits. The salary will increase with experience and performance.
Selection Process: Candidates shortlisted for the interview are given a level of commissioned officer.

Combined Medical Services

MBBS graduates can work with the central government agencies UPSC CMS exam. Combined Medical Services gives roles like General Duty Medical Officer (GDMO), etc. The work depends on the job role but mostly involves outpatient care, emergency, and administration. These roles are assigned in organizations like the Railway, Municipal Corporations, and the Central Health Services.
The recruitment process happens each year, and candidates should have prepared well to clear the exam and achieve their goals. These roles offer a stable career, respect, and a chance to secure long-term benefits.

Eligibility: Graduate with MBBS with valid registration from MCI.
Salary range: 56,100 to 1,77,500 per month, salary range varies on the candidate’s experience.
Selection process: After clearing the UPSC exam, candidates are shortlisted for the interview and selected for their role.

AIIMS and Other Central Government Institutes

JIPMER, AIIMS, and PGIMER are the exam-conducting bodies that recruit medical professionals for roles like Junior Resident, Senior Resident, and Medical Officers. These jobs are well-paid and reputed jobs for Indian doctors.

Working with these research centers is the best chance to improve practical skills and exposure to medical research.

Posts: Doctor, healthcare professional, research scientist, administrative.
Eligibility: MBBS or MD graduates with medical certificate.
Salary range: These posts give a huge pay scale once you get experience. Candidate’s starting salary is 35,000 then rise to 1,77,500 with additional benefits.
Selection process: Written Exam, Interview for the respective post.

Indian Council of Medical Research

If you want to go into the research and public health field not just clinical practice then explore various opportunities by ICMR. It has a big role playing in biomedical research. If you’re interested in epidemiology, clinical trials can step into this role. You can apply for roles like Research Officer, Project Associate, or Scientist but it offers a promotion with more experience.

You have to focus and study hard to be able to beat this competition and secure a role for your lifetime stability.

Posts: Scientists B/C/D, Research (Junior, Senior), Administrator.
Salary range: These posts have a good pay-scale. Candidate’s starting salary is 35,000 and with experience it will increase to 1,77,500 per month.
Selection process: Screening test, Interview.

State Health Services

There are several health departments in India that frequently announce vacancies for doctors, dentists, and practitioners. Some states often offer posts including Community Health, Rural Medical Officer, or District Medical Officer. Recruitment for these roles is through state PSCs. If you wish to have a good salary and job security, you can consider applying for this role after MBBS.

Posts: Medical Officer, District Medical Officer
Salary range: Candidate’s starting salary is 50,000 and with performance, it will increase to 1,00,000 per month.
Selection process: The candidates are recruited through exams then they are shortlisted for an interview.

Public Sector Undertakings (PSUs)

Not just engineers but PSUs also recruit for medical field candidates where companies like Coal India, ONGC, BHEL, NTPC, and GAIL give the posts according to the interview base. Many students score well in MBBS so they’re recruited directly by PSUs but interview is mandatory for these roles. If you’re seeking a less hectic medical career then this is the perfect role for you. The pay scale is highly impressive and also has additional perks.

Posts: The work involves implementing government schemes for healthcare and other initiatives.
Salary range: The salary ranges between 40,000 to 1,20,000 per month.
Selection process: Recruited by public health sectors like NTPC or BHEL.

Conclusion

Working in government organizations after a medical degree is a great deal of pride. You serve the nation whether as an army medical officer or just in a government hospital. People who can’t afford private hospital expenses come to the government hospital. Your work directly affects public health, especially for the rural people. However, it is difficult to secure a government job in the medical field but you can achieve it with the right preparation and stay updated for the latest jobs. Keep an eye on recruitment notifications on official websites to apply for government jobs.

Best Courses for Business Analyst: Learn, Certify & Grow

Best Courses for Business Analysts

There are various courses for Business Analyst that will help you understand what Business Analyst is and why it is used in today’s changing world. This field is profitable for those who are interested in numbers and understand insights because analysing data and making strategic decisions to grow a company or business on a higher level is a responsibility of a Business Analyst.

Why Business Analysts Are in Demand Right Now

The numbers tell the story. It is witnessing a high compound annual growth rate (CAGR) of 35.8% during the forecast period of 2025 to 2030 The booming market for the Indian data analytics in 2025 The expanding Indian data analytics market in 2025. The U.S. Bureau of

 Labor Statistics, which projects a growth rate of 11% for business analyst jobs through 2032, is significantly higher than the average growth rate for all occupations. Simply put, there are more positions for business analysts open than there are qualified professionals to fill them. 

this is not only a matter of having jobs. It’s about how much you can make and whether you enjoy your work. In India, the average salary for a business analyst starts from ₹3–7 lakhs per year for freshers and can go up to ₹25–40 lakhs per annum for senior professionals. The average business analyst salary in the US is about $109k a year, with top money earners moving beyond $132k in tech hubs such as San Francisco. These are not small numbers—to the contrary, they represent real, stable, good-paying career opportunities and all that sort of thing. 

Understanding What a Business Analyst Actually Does

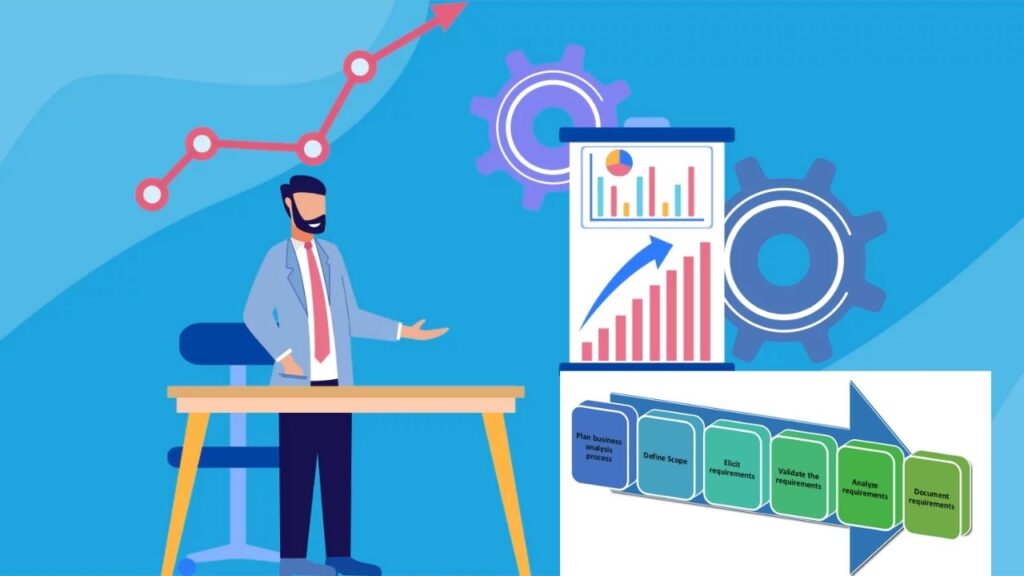
Before you start taking courses, you should have a clear sense of what this job is about. Business analysts are, at their core, the intermediary between business challenges and technology solutions. They are also professional problem solver where they day by day activities are getting requirements from stakeholders, analyze the business procedures, find inefficiencies, recommend solutions based on data to enhance the performance of a business.

On any given day, a business analyst might be:

  • Performing deep-dive stakeholder interviews to gain a clear view of the business needs and requirements
  • Querying and analyzing data with tools like Excel, Power BI, Tableau to uncover trends and insights
  • Building reports, presentations, dashboards, flow charts to share findings
  • Working with IT teams to delivery and support technical solutions
  • Delivering insight and recommendations on courses of action to senior leaders and key decisions makers  

The position commands a unique blend of technical knowledge and business acumen along with soft skills. You need to know about data analysis and databases, but you also need to talk to non-technical stakeholders. And it’s the ability to do all three that makes the role so valuable — and so in demand. 

Best Bachelor’s Degrees to Become a Business Analyst

Bachelor’s degree is required by most business analyst jobs. The good part is that the degree doesn’t have to be exactly the one in business analysis. Companies are flexible when it comes to your educational background as long as you have proven your knowledge and skills in the relevant fields. 

Bachelor’s degree with relevant field of study includes:

  • Business Administration or Management
  • Finance or Accounting
  • Economics
  • Information Technology (IT) or Computer Science (CS)
  • Data Analytics or Data Science
  • Statistics

If you have a bachelor’s in any of these subjects or even a ballpark related one—you’re already halfway there. A good number of individuals move into business analyst positions from related professions such as finance and data analysis, as well as project management.

For those seeking to make their mark at the senior level or as a business analytics leader, a master’s degree is often a big help. Dozens of professionals get their MBA, MBA in Business Analytics, or attend a specialized Master program in Data Analytics or Business Intelligence. These higher level qualifications will give you the technical know-how and open doors to more lucrative positions and quicker career advancement. 

Short-Term Certification Courses For Business Analyst

If you want to get into the field fast without spending years on a master’s degree, certification courses are your golden ticket. These courses are designed for business analysis practitioners and usually last between 6 weeks and 6 months, covering business analysis tools and techniques. 

IMS Proschool – Business Analytics Course is one of the leading analytics institute in India. They are known for effectively bridging the gap between theory and application and are well established with levels of comprehensive training with Excel, Power BI, SQL, and statistical analysis. They focus on hands-on learning so you work on real projects you can show to employers.

Simplilearn’s Business Analyst Course is IIBA (the International Institute of Business Analysis, the gold standard in the industry) compliant. They provide for everything: Excel, Power BI dashboarding, requirement analysis and agile methodologies. This course contains CBAP and CCBA exam prep, which are internationally recognized certificates. 

Short-Term Certification Courses
Image credit: Simplilearn

ExcelR – Business Analyst Certification Training is known for providing a good mix of theory and practical knowledge. The curriculum incorporates real case studies and projects, so you’ll finish the program with a portfolio that gets the attention of potential employers.

Techcanvass – Business Analyst Certification is best for if you are looking for IIBA aligned training. They provide a comprehensive learning path for ECBA (Entry Certificate in Business Analysis), CCBA (Certification of Competency in Business Analysis) and CBAP (Certified Business Analysis Professional) with weekend classes that are suitable for working professionals.

EdX – Business Analysis Professional Certificate (Lehigh University) is an excellent choice if you want a globally recognized credential from a good university. This is excellent if you want something internationally recognized and that too without leaving India. 

Mastering the Essential Tools and Skills

Perhaps the most compelling feature of contemporary business analyst training is the fact that you get taught the precise tools that companies want you to have. Here’s what you’ll typically cover:

Data Analysis and Visualization Tools:

  • Excel: Functions, pivot tables, Power Query, and VBA automation
  • Power BI enables users to connect to their data sources, transform the raw data into meaningful information, and then build interactive dashboards to visualize data. 
  • Tableau is also a great tool to create colorful visualizations and strategic dashboards that can be very informative in decisions making. 
  • Also, SQL is necessary if you want to query and work with databases directly, or perform any significant data manipulation, as it allows you to efficiently extract and manage your data. 

With these tools, you can analyze and visualize your data with great impact. 

Business Analysis Methodologies:

  • Gathering and writing requirements
  • Process mapping, business process improvement,
  • Stakeholder management and communication
  • Agile and Scrum methodologies
  • Strategic planning and SWOT analysis 

Soft Skills Development:

  • Critical thinking and problem-solving
  • Effective business communication
  • Project management fundamentals
  • Data storytelling and presentation skills

Global Recognition for Your Skills

If you want to be taken seriously in the industry, getting certified can help. These are not just nice to have, they are increasingly expected by current and future employers particularly for mid-level and senior roles.

IIBA Certifications (International Standard)

The International Institute of Business Analysis provides a tiered pathway for certification. IIBA certifications demonstrate to employers your dedication and skill in the field. Certified Professionals with these designations consistently report increased salaries and more job opportunities. The salaries of business analyst in India is also quite good, those who are CBAP certified can earn a lot more than their uncertified counterparts with the same years of experience.

ECBA (Entry Certificate in Business Analysis): Designed for novices and individuals looking to break into the field of business analysis. At least 900 hours of business analysis work must be verified. This certification attests that you are familiar with basic business analysis principles.

CCBA (Certification of Competency in Business Analysis): The intermediate level, which requires 3000 hours of business analysis within the last 5 years. It demonstrates the capability to apply business analysis techniques and concepts. 

CBAP (Certified Business Analysis Professional): The highest level certification, for which 7,500 hours of business analysis work experience in the prior ten years is required. It’s an industry best practice and that’s typically what translates into higher salaries, more leadership roles. 

Read More :- Top AI & ML Colleges in Delhi: Courses, Eligibility Fees & Placements

Salary Progression and Career Growth

In India, the starting salary of a business analyst is ₹3–7 LPA. This depends on your degree, certifications, city of work & Industry.

This is a genuine salary escalates in India:

Newbie (0–2 years): ₹3–7 lakhs per annum

Mid-level (3–5 years): ₹8–15 lakhs per year

Experienced (6+ years): 17–38.5+ lakhs per annum

But a paycheck isn’t just earned with experience. It’s much more to do with specialization and skills. Business analysts with experience in financial services (banks, insurance companies, investment firms), technology, or consulting industries tend to earn 10-20% more than those in other industries. Similarly, skills such as Python, R, advanced SQL, machine learning knowledge can supercharge your income. 

Average US Business Analyst salary: Entry level or beginner Business Analyst salaries ranged from $70,000 to $80,000 in 2014.41 Mid-career Business Analysts could expect to earn between $100,000 to $120,000 in the United States. Senior Business Analyst or Specialist pay is typically $138,000+. Location is also important; San Francisco, New York City, and Seattle pay much more than smaller cities.  

The Roadmap For Business Analyst

Phase 1: Foundation (Month 1-3)

Sign up for a business analyst certification training. Select one that best fits your learning style and schedule. Learn enough about Excel, the basics of business analysis and SQL to get started.

Phase 2: Specialization (Month 4-6)

Get your certification. Learn Power BI or Tableau. In case of a cream applicant is probably serious about the domain of the field you want to pursue an ECBA certification. Develop 2–3 projects from your course to create a portfolio.

The Roadmap For Business Analyst

Phase 3: Entry Level Role (6-12 months)

Apply for junior business analyst or business analyst associate roles. I will add: You don’t have to have perfect experience at this point – companies will train you on methodologies and domain knowledge. Go start earning experience in the field.

Stage 4: Growth (second and third years)

Go for the CCBA certification. Get more specialized in your niche. Progress to more complex assignments with more stakeholders to manage. You should expect your pay to escalate to ₹8-12 lakhs in India or $80,000-$95,000 in the U.S.

Step 5: Senior Role (Years 4+)

Get the CBAP qualification if it is upward career mobility you are seeking for. Progress to senior analyst positions, manage teams, or focus in fields such as product management, strategy, or technical business analysis. Senior positions will pay a lot more and have a wider impact on the rest of the company. 

Conclusion

The business analyst sector is growing rapidly, and with good reason. It’s mentally stimulating, well-paid, and ever more essential to the success of an organization. Take the short certificate course, a master’s degree or a combination of the two – whatever form of business analyst education you decide to invest in, the payoff will be well worth it.

Start the key is to. Don’t get analysis paralysis. Choose a good program, learn the core tools and concepts, and start building a portfolio with real projects if you want to get hired. The skills are important, but it’s your demonstrated ability to use those skills with real work that gets you hired. 

The business analyst position is ideal for a person who enjoys problem solving and working with data and who wants to have an influence in an organization’s decision making. If that describes you, take that first step today. The job prospects, the salary and the intellectual gratification at the end of it are more than worth it. 

Scroll to Top